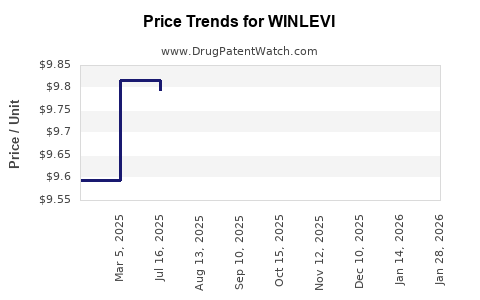
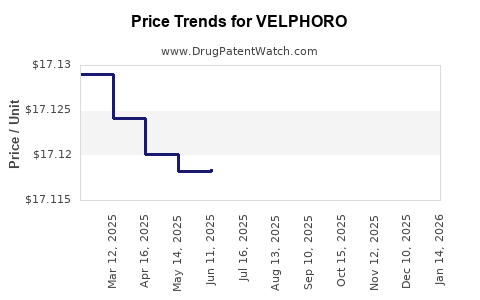
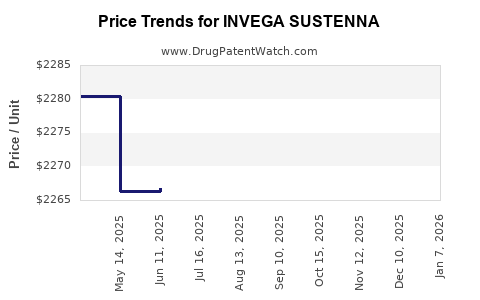
Last updated: October 11, 2026
Finland is a regulated, price-sensitive pharmaceutical market with strong generic substitution, centralized reimbursement controls, high digitalization, and substantial public-sector purchasing. Market opportunities are strongest in hospital generics, biosimilars, specialty medicines, orphan drugs, shortage mitigation, and products with clear clinical or budget impact. Commercial challenges include low reimbursement prices, reference pricing, pharmacy substitution, parallel trade, national language requirements, and lengthy evidence requirements for premium pricing.
What is the size and structure of the Finnish pharmaceutical market?
Finland has a relatively small population of approximately 5.6 million, but it has mature pharmaceutical infrastructure, high prescription-drug access, and a well-developed public reimbursement system. The market is divided into:
| Segment |
Main buyers or decision-makers |
Principal commercial characteristics |
| Community pharmacy medicines |
Patients, pharmacies, Kela reimbursement system |
Generic substitution, reference pricing, pharmacy margins, parallel imports |
| Hospital medicines |
Wellbeing services counties and hospital pharmacies |
Competitive tenders, regional procurement, clinical and budget criteria |
| OTC medicines |
Consumers and pharmacies |
Self-care positioning, pharmacist recommendation, advertising restrictions |
| Specialty medicines |
Hospitals, specialists, reimbursement authorities |
High evidence requirements, managed access, budget-impact scrutiny |
| Biosimilars |
Hospitals, pharmacies, prescribers, Kela |
Increasing uptake, tender-driven competition, substitution policy |
| Orphan medicines |
Hila, hospitals, specialist centers |
Small patient populations and high per-patient costs |
Prescription medicines are distributed mainly through community pharmacies and hospital pharmacies. Finland has one of Europe’s most digitalized healthcare systems, with electronic prescriptions and extensive use of national health data infrastructure. The principal public reimbursement administrator is the Social Insurance Institution of Finland, known as Kela. The Pharmaceuticals Pricing Board, or Hila, decides whether a medicine receives reimbursement and whether its price is considered reasonable. Fimea is Finland’s national medicines agency and supervises medicinal products, pharmacies, pharmacovigilance, and regulatory compliance. [1-4]
How does FDA-equivalent marketing authorization work in Finland?
Finland is an EU member state, so most prescription medicines enter through the EU regulatory framework rather than a purely national approval route.
Which regulatory routes are available?
A company may use:
- Centralized EU authorization through the European Medicines Agency, resulting in authorization across EU and European Economic Area markets.
- Decentralized procedure, where Finland is selected as a concerned member state.
- Mutual recognition procedure, based on an existing national authorization in another EU member state.
- National authorization, mainly for products limited to Finland and outside mandatory centralized categories.
Generic and hybrid medicines generally rely on abbreviated EU applications under Article 10 of Directive 2001/83/EC. Hybrid products may require additional clinical or nonclinical evidence where the product differs from the reference medicine in formulation, strength, route of administration, or therapeutic indication.
Finland requires product information, packaging, and patient materials in Finnish and Swedish. This creates translation, artwork, serialization, and supply-chain requirements that are material for smaller generic companies. [2,5]
What FDA regulatory status equivalent applies to generics?
There is no Finnish equivalent of the U.S. Orange Book. Generic applicants instead rely on the EU marketing authorization system, national product information, the European Commission authorization database, and national reimbursement and substitution decisions.
Patent status is not a formal prerequisite for authorization. Finland generally does not have U.S.-style patent linkage between marketing authorization and patent enforcement. A generic may seek approval before patent expiry, subject to applicable patent exemptions and commercial launch restrictions.
What reimbursement and pricing rules affect branded and generic drugs?
Finland uses a two-level access model: regulatory approval permits marketing, but public reimbursement requires a separate decision.
How does Hila determine reimbursement?
Hila evaluates:
- Therapeutic value and clinical evidence
- Existing treatment alternatives
- Cost-effectiveness and budget impact
- Proposed wholesale price
- International price comparisons
- Reimbursement categories
- The size and characteristics of the patient population
A company seeking reimbursement normally submits an application for a reasonable wholesale price and reimbursement status. Reimbursement may be general, limited, or restricted to defined clinical criteria. Hila can impose conditions, request additional evidence, and reassess pricing after a specified period.
A product can therefore obtain EU or Finnish marketing authorization but have limited commercial access if Hila rejects reimbursement or approves a price that does not support the proposed launch strategy.
How does generic substitution work in Finland?
Finnish pharmacies generally substitute a prescribed product with the least expensive interchangeable product or another product within the applicable price range, unless substitution is medically prohibited or the patient declines substitution and pays the resulting price difference.
The reference price system groups interchangeable medicines and establishes a reimbursement ceiling. Products priced above the applicable reference price can expose patients to additional out-of-pocket costs unless an exception applies. This places direct pressure on originator and generic list prices.
For generic companies, inclusion in the substitution system is critical. Regulatory approval alone does not guarantee meaningful volume. The product must be recognized as interchangeable, priced competitively, supplied reliably, and listed in the relevant reimbursement and pharmacy systems.
What opportunities exist in the Finnish branded drug market?
Which branded products have the strongest market opportunities?
Branded companies are most likely to succeed where they offer measurable clinical differentiation, a new mechanism, improved adherence, or a delivery system that reduces healthcare utilization.
Priority areas include:
- Oncology and hematology
- Immunology and inflammatory diseases
- Diabetes and obesity
- Neurology and rare diseases
- Advanced therapies and cell and gene therapy
- Hospital anti-infectives
- Long-acting injectables
- Digital or adherence-enabled delivery systems
- Medicines addressing national shortages
High-priced specialty products face strict reimbursement scrutiny. A positive clinical profile is not enough. Companies need a Finnish market-access plan that links outcomes to budget impact, identifies the eligible population, and anticipates Hila’s price expectations.
What commercial strategies improve branded access?
Branded manufacturers can improve access through:
- Early engagement with Finnish clinical experts and payers
- Local budget-impact models
- Risk-sharing or managed-entry agreements where permitted
- Patient-access programs consistent with Finnish rules
- Hospital tender participation
- Local evidence generation
- Forecasting and shortage-prevention commitments
- Separate strategies for community and hospital channels
The commercial value of a Finnish launch is often strategic rather than purely volume-driven. Finland can provide an evidence-generating reference market for Nordic negotiations, but low prices may affect external reference pricing in other countries.
What opportunities exist in the Finnish generic and biosimilar markets?
Which generic segments are attractive?
Generic opportunities are concentrated in products with:
- High prescription volume
- Imminent loss of exclusivity
- Multiple interchangeable competitors
- Reliable API supply
- Simple reimbursement positioning
- Hospital demand
- Limited manufacturing complexity
Injectables, inhaled products, modified-release formulations, sterile products, ophthalmics, and complex generics can offer better barriers to entry than standard oral solid products. These products require greater development and manufacturing capability, reducing the number of credible competitors.
Is Finland attractive for biosimilars?
Finland is a credible biosimilar market, particularly in hospital procurement and high-cost biologic categories. Biosimilar uptake depends on:
- Hospital tender design
- Prescriber confidence
- National and regional substitution policy
- Procurement continuity
- Product-specific clinical guidance
- Supply reliability
- Pricing relative to the originator
Biosimilar companies should separate the regulatory opportunity from the procurement opportunity. EU authorization can support market entry, but winning hospital tenders and achieving substitution or prescribing volume requires local commercial execution.
What formulation patents protect generic opportunities?
Formulation and device patents can delay or complicate generic entry even when the active-ingredient patent has expired. Key risk areas include:
- Extended-release matrices
- Inhaler devices
- Injectable delivery systems
- Autoinjectors
- Depot formulations
- Salt and polymorph claims
- Particle-size specifications
- Combination products
- Manufacturing processes
- Stability and packaging systems
A Finnish freedom-to-operate review should cover Finnish national patents, European patents validated in Finland, unitary patents, supplementary protection certificates, and pending applications. Companies must assess both product claims and process claims because a generic may avoid a composition claim but still face manufacturing or device allegations.
When do Finnish drugs lose exclusivity?
There is no single Finnish exclusivity date. The relevant timeline can include regulatory data protection, marketing protection, patents, SPCs, pediatric extensions, orphan exclusivity, and formulation or method-of-use rights.
| Protection |
Typical legal effect |
| Regulatory data protection |
Restricts reliance on the reference dossier during the EU data-protection period |
| EU marketing protection |
Delays commercial marketing after the data-protection period |
| Basic patent |
Usually expires 20 years from filing, subject to national validation and procedural issues |
| SPC |
Can extend protection for eligible medicinal products, generally up to five additional years |
| Pediatric extension |
May add six months to eligible patent or SPC protection |
| Orphan exclusivity |
Can limit approval of similar products for the protected indication, subject to EU rules |
| Method-of-use patent |
May cover a specific indication, dosage regimen, or patient population |
| Device or formulation patent |
May remain relevant after active-ingredient exclusivity expires |
Patent expiration must be confirmed patent by patent. The relevant date may differ between the active ingredient, formulation, device, process, and indication. European patents validated in Finland and unitary patents can create overlapping protection.
What patent litigation and Paragraph IV risks exist in Finland?
Finland does not use the U.S. Paragraph IV certification system. A Finnish generic company does not file a Paragraph IV certification with a Finnish equivalent of the FDA.
The practical European equivalent is a combination of:
- Patent validity and infringement analysis
- Pre-launch opposition or revocation proceedings
- National invalidity or infringement litigation
- Declaratory actions
- Regulatory filings based on the Bolar exemption
- Launch planning after expiry or under a non-infringement position
The Unified Patent Court has jurisdiction over participating European patents and unitary patents. Finland participates in the UPC system and has a Helsinki local division. National Finnish courts remain relevant for patents outside UPC jurisdiction and for national procedural matters. [6-8]
What does the Finnish Bolar exemption allow?
Finnish and EU law generally permit acts necessary to obtain marketing authorization before patent expiry. This allows generic development, testing, and regulatory preparation before the patent term ends. The exemption does not generally authorize commercial sale or stockpiling for commercial launch before enforceable patent rights expire.
A generic launch plan should distinguish:
- Regulatory development date
- Marketing authorization date
- Reimbursement application date
- Patent expiry date
- SPC expiry date
- Commercial inventory date
- First lawful sale date
Which companies compete in Finland?
The market includes multinational originators, European generic groups, Nordic suppliers, specialty manufacturers, and local or regional distributors. Competitive intensity is high in standard oral products and lower in complex dosage forms, sterile products, biosimilars, and hospital medicines.
Relevant competitor categories include:
- Originator companies defending premium brands
- Large European generic manufacturers
- Nordic distributors and parallel importers
- Contract manufacturers
- Biosimilar specialists
- Hospital tender suppliers
- Pharmacy-channel OTC companies
The leading commercial differentiator is often supply continuity rather than nominal price. Finnish pharmacies and hospitals are sensitive to shortages, substitution availability, delivery performance, and product information accuracy.
What regulatory and market-access challenges face drug companies?
Which operational barriers are most important?
The main barriers are:
- Finnish and Swedish labeling requirements
- EU variation and lifecycle-management compliance
- Reimbursement price negotiations
- Reference-price compression
- Pharmacy substitution
- Parallel imports
- Small absolute market size
- Regional hospital procurement
- Medicine shortages
- Pharmacovigilance and serialization obligations
- Data and evidence requirements for premium reimbursement
Finland has experienced medicine shortages affecting both branded and generic products. Companies with diversified manufacturing, safety stock, and transparent shortage communication can gain procurement credibility. Supply failures can lead to pharmacy substitution, loss of prescriber confidence, and tender penalties.
How do hospital tenders differ from community pharmacy sales?
Hospital products are frequently assessed through procurement processes involving wellbeing services counties, hospital districts, and procurement organizations. Price is important, but tender criteria can also include:
- Delivery reliability
- Packaging and logistics
- Product usability
- Training
- Continuity of supply
- Environmental requirements
- Clinical support
- Total cost of care
Community pharmacy products depend more heavily on substitution status, reimbursement classification, wholesale price, pharmacy availability, and patient cost exposure.
How does Finland compare with Sweden and Denmark?
| Issue |
Finland |
Sweden |
Denmark |
| Regulatory basis |
EU framework with Fimea oversight |
EU framework with Swedish Medical Products Agency |
EU framework with Danish Medicines Agency |
| Reimbursement authority |
Hila and Kela |
TLV and regional systems |
Danish Medicines Agency and regional procurement |
| Generic substitution |
Strong pharmacy substitution |
Strong substitution and tender influence |
Strong substitution and pharmacy price competition |
| Hospital procurement |
Regional wellbeing services and hospitals |
Regions |
Regions and hospital procurement bodies |
| Language requirement |
Finnish and Swedish |
Swedish |
Danish |
| Commercial profile |
Small, digital, price-sensitive, reimbursement-driven |
Larger Nordic reference market |
Highly competitive and procurement-focused |
Finland is usually easier to enter through an existing EU authorization than through a standalone national development program. Sweden may offer greater scale, while Denmark may provide stronger procurement leverage in hospital products. Finland’s bilingual packaging and reimbursement process create additional localization work relative to Denmark.
What licensing and partnership opportunities exist?
Licensing opportunities are strongest where a company has:
- EU rights but no Finnish commercial infrastructure
- A complex generic or biosimilar
- A hospital product requiring tender access
- A shortage-sensitive medicine
- A specialty medicine requiring local reimbursement expertise
- A Nordic portfolio suitable for regional distribution
Potential partners include Nordic distributors, specialty pharmaceutical companies, hospital tender specialists, and local market-access advisers. Agreements should define responsibility for:
- Hila submissions
- Fimea contacts
- Finnish and Swedish packaging
- Pharmacovigilance
- Shortage notifications
- Tender participation
- Price approvals
- Parallel import management
- Patent and launch risk
- Inventory ownership
A Finland-only license may be inefficient for products requiring Nordic scale. Regional agreements covering Finland, Sweden, Denmark, and Norway can improve supply economics, but they must preserve country-specific pricing and reimbursement control.
What is the outlook for revenue exposure and generic entry?
Revenue exposure depends on the product’s channel and exclusivity profile.
| Product profile |
Revenue risk at loss of exclusivity |
Likely Finnish entry pattern |
| High-volume oral tablet |
High |
Rapid substitution and multiple generic entrants |
| Complex injectable |
Moderate |
Fewer entrants, tender competition |
| Hospital biologic |
Moderate to high |
Biosimilar tender displacement |
| Orphan medicine |
Variable |
Limited direct generic competition, reimbursement pressure |
| Inhaled product |
Moderate |
Device and formulation barriers may delay entry |
| OTC brand |
Moderate |
Brand loyalty and pharmacy positioning matter |
| Combination product |
Variable |
Patent and regulatory complexity can limit entrants |
A likely generic-entry scenario is rapid price reduction after the first interchangeable competitor obtains reimbursement and pharmacy listing. A second scenario is delayed entry caused by patent, device, formulation, or manufacturing barriers. A third is limited practical entry where the product receives authorization but lacks sufficient supply, reimbursement, or tender access.
How strong is the Finnish pharmaceutical patent estate?
Patent strength should be assessed as a European portfolio rather than as a purely Finnish asset. The most important variables are:
- Remaining patent term
- SPC availability and validity
- Claim scope
- Opposition history
- EPO appeal status
- Unitary patent coverage
- UPC opt-out status
- National validation in Finland
- Patent owner or licensee standing
- Evidence supporting infringement
- Availability of non-infringing alternatives
Active-ingredient patents usually provide the strongest exclusionary position. Secondary patents can be commercially important but face greater validity and design-around risk. Method-of-use patents may be less effective where physicians can lawfully prescribe for non-patented indications and product information can be carved out, although enforcement remains fact-specific.
Key Takeaways
- Finland is an EU-regulated market overseen nationally by Fimea, Hila, and Kela.
- There is no Finnish Orange Book and no U.S.-style Paragraph IV certification.
- Generic entry depends on EU authorization, interchangeability, reimbursement, pricing, supply, and patent clearance.
- Reference pricing and pharmacy substitution create substantial price pressure.
- Hospital tenders are central to biosimilar and injectable-product access.
- Finnish and Swedish product information is required for many products.
- Patent analysis must include Finnish validations, European patents, SPCs, unitary patents, formulation claims, device claims, and manufacturing rights.
- The strongest opportunities are in complex generics, biosimilars, specialty medicines, shortage-sensitive products, and hospital products.
- The main commercial risks are reimbursement rejection, low approved prices, parallel imports, shortages, and secondary patent litigation.
- Finland is strategically useful for Nordic market access but rarely supports a high-price, standalone launch model without strong clinical differentiation.
FAQs
Does Finland have an Orange Book for pharmaceutical patents?
No. Finland does not maintain a U.S.-style Orange Book linking marketing authorization to listed patents. Companies must conduct independent patent and regulatory-status reviews.
Can a generic company obtain Finnish approval before patent expiry?
Yes. EU and Finnish Bolar-type exemptions generally permit regulatory development and submission activities before patent expiry. Commercial launch remains subject to enforceable patent, SPC, and other exclusivity rights.
Are biosimilars automatically substituted in Finnish pharmacies?
No. Biosimilar substitution and prescribing practice depend on product-specific Finnish rules, pharmacy policy, clinical guidance, and hospital procurement arrangements.
Which authority approves Finnish drug prices?
Hila, the Pharmaceuticals Pricing Board, decides whether a medicine has a reasonable wholesale price and qualifies for reimbursement. Kela administers reimbursement to patients and pharmacies.
Is Finland a good launch market for complex generics?
Finland can be attractive for complex generics because competition is narrower than for standard tablets and hospital demand can support volume. The market remains price-sensitive, and successful entry requires EU regulatory approval, reimbursement access, local-language compliance, reliable supply, and patent clearance.
References
- Finnish Medicines Agency. (2024). Fimea: Tasks and responsibilities. https://www.fimea.fi
- European Medicines Agency. (2024). Human medicines. https://www.ema.europa.eu
- Pharmaceuticals Pricing Board. (2024). Reimbursement and reasonable wholesale price. https://www.hila.fi
- Social Insurance Institution of Finland. (2024). Reimbursements for medicines. https://www.kela.fi
- European Commission. (2024). EudraLex, Volume 2: Pharmaceutical legislation. https://health.ec.europa.eu
- Unified Patent Court. (2024). Court divisions and jurisdiction. https://www.unifiedpatentcourt.org
- European Patent Office. (2024). Unitary Patent and Unified Patent Court. https://www.epo.org
- EUR-Lex. (2001). Directive 2001/83/EC on the Community code relating to medicinal products for human use. https://eur-lex.europa.eu