Last Updated: November 16, 2026

Expiring Drug Patents Cheat Sheet
We analyse the patents covering drugs in 134 countries and quickly give you the likely loss-of-exclusivity/generic entry date

➤ Get the Full List

Chile: These 17 Drugs Face Patent Expirations and Generic Entry From 2026 - 2027

The content of this page is licensed under a Creative Commons Attribution 4.0 International License. Creative Commons License

Preferred citation:
Friedman, Yali, "Chile: These 17 Drugs Face Patent Expirations and Generic Entry From 2026 - 2027" DrugPatentWatch.com thinkBiotech, 2026 www.drugpatentwatch.com/p/expiring-drug-patents-generic-entry/.
Media collateral
These estimated drug patent expiration dates and generic entry opportunity dates are calculated from analysis of known patents covering drugs. Many factors can influence early or late generic entry. This information is provided as a rough estimate of generic entry potential and should not be used as an independent source. The methodology is described in this blog post.
When can SIRTURO (bedaquiline fumarate) generic drug versions launch in Chile?

Generic name: bedaquiline fumarate
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: December 05, 2026
Generic Entry Controlled by: Chile Patent 2,007,003,472

SIRTURO is a drug marketed by Janssen Therap. There are two patents protecting this drug.

See drug price trends for SIRTURO.

The generic ingredient in SIRTURO is bedaquiline fumarate. Additional details are available on the bedaquiline fumarate profile page.

When can ZYKADIA (ceritinib) generic drug versions launch in Chile?

Generic name: ceritinib
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: December 08, 2026
Generic Entry Controlled by: Chile Patent 2,007,003,552

ZYKADIA is a drug marketed by Novartis. There are eight patents protecting this drug.

See drug price trends for ZYKADIA.

The generic ingredient in ZYKADIA is ceritinib. Additional details are available on the ceritinib profile page.

When can NESINA (alogliptin benzoate) generic drug versions launch in Chile?

Generic name: alogliptin benzoate
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: February 01, 2027
Generic Entry Controlled by: Chile Patent 2,008,000,280
Patent Title: COMPOSICION FARMACEUTICA EN FORMA DE COMPRIMIDO QUE CONTIENE UN GRANULO QUE COMPRENDE UN PRINCIPIO ACTIVO QUE INDUCE FACILMENTE A UN PROBLEMA EN LA COMPRESION Y CELULOSA MICROCRISTALINA Y UN AUXILIAR DE COMPRESION QUE CONTIENE ESTEARATO DE MAGNESIO Y
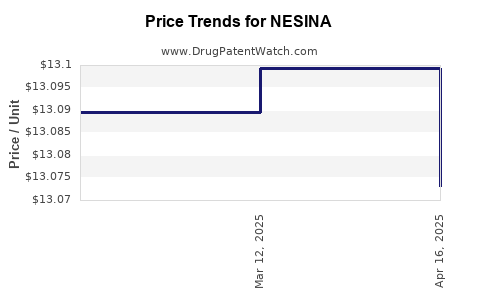
Drug Price Trends for NESINA
NESINA is a drug marketed by Takeda Pharms Usa. There are two patents protecting this drug and one Paragraph IV challenge. Two tentatively approved generics are ready to enter the market. There has been litigation on patents covering NESINA

See drug price trends for NESINA.

The generic ingredient in NESINA is alogliptin benzoate. Additional details are available on the alogliptin benzoate profile page.

When can OSENI (alogliptin benzoate; pioglitazone hydrochloride) generic drug versions launch in Chile?

Generic name: alogliptin benzoate; pioglitazone hydrochloride
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: February 01, 2027
Generic Entry Controlled by: Chile Patent 2,008,000,279

Drug Price Trends for OSENI
OSENI is a drug marketed by Takeda Pharms Usa. There are two patents protecting this drug. There has been litigation on patents covering OSENI

See drug price trends for OSENI.

The generic ingredient in OSENI is alogliptin benzoate; pioglitazone hydrochloride. Additional details are available on the alogliptin benzoate; pioglitazone hydrochloride profile page.

When can EDARBI (azilsartan kamedoxomil) generic drug versions launch in Chile?

Generic name: azilsartan kamedoxomil
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: March 28, 2027
Generic Entry Controlled by: Chile Patent 2,008,000,868
Patent Title: COMPOSICION FARMACEUTICA SOLIDA QUE COMPRENDE UN COMPUESTO DERIVADO DE BENZIMIDAZOL Y UN AGENTE DE CONTROL DE PH; METODO DE ESTABILIZACION Y DE MEJORAMIENTO DE LA DISOLUCION; USO DE UN AGENTE DE CONTROL DE PH.
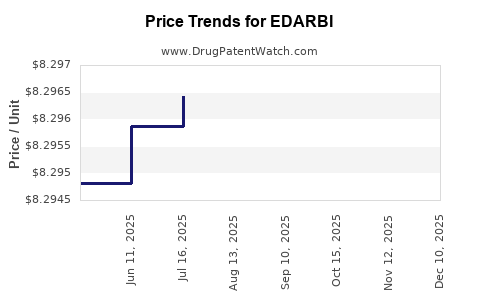
Drug Price Trends for EDARBI
EDARBI is a drug marketed by Azurity. There is one patent protecting this drug. There has been litigation on patents covering EDARBI

See drug price trends for EDARBI.

The generic ingredient in EDARBI is azilsartan kamedoxomil. Additional details are available on the azilsartan kamedoxomil profile page.

When can PROMACTA (eltrombopag olamine) generic drug versions launch in Chile?

Generic name: eltrombopag olamine
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: May 03, 2027
Generic Entry Controlled by: Chile Patent 2,007,002,242

PROMACTA is a drug marketed by Novartis. There is one patent protecting this drug and two Paragraph IV challenges. There has been litigation on patents covering PROMACTA

See drug price trends for PROMACTA.

The generic ingredient in PROMACTA is eltrombopag olamine. Additional details are available on the eltrombopag olamine profile page.

When can SIGNIFOR LAR (pasireotide pamoate) generic drug versions launch in Chile?

Generic name: pasireotide pamoate
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: May 24, 2027
Generic Entry Controlled by: Chile Patent 2,008,001,509

SIGNIFOR LAR is a drug marketed by Recordati Rare. There are three patents protecting this drug.

See drug price trends for SIGNIFOR LAR.

The generic ingredient in SIGNIFOR LAR is pasireotide pamoate. Additional details are available on the pasireotide pamoate profile page.

When can FARYDAK (panobinostat lactate) generic drug versions launch in Chile?

Generic name: panobinostat lactate
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: June 11, 2027
Generic Entry Controlled by: Chile Patent 2,007,001,689

FARYDAK is a drug marketed by Secura. There are two patents protecting this drug. There has been litigation on patents covering FARYDAK

See drug price trends for FARYDAK.

The generic ingredient in FARYDAK is panobinostat lactate. Additional details are available on the panobinostat lactate profile page.

When can KYBELLA (deoxycholic acid) generic drug versions launch in Chile?

Generic name: deoxycholic acid
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: June 19, 2027
Generic Entry Controlled by: Chile Patent 2,008,001,783
Patent Title: Acido desoxicolico (dca); composicion farmaceutica que lo comprende; procedimiento de preparacion de acido desoxicolico; compuestos intermediarios, utiles en la preparacion de un medicamento para remover depositos de grasa.

KYBELLA is a drug marketed by Abbvie. There are fourteen patents protecting this drug and one Paragraph IV challenge. There has been litigation on patents covering KYBELLA

The generic ingredient in KYBELLA is deoxycholic acid. Additional details are available on the deoxycholic acid profile page.

When can TEKTURNA HCT (aliskiren hemifumarate; hydrochlorothiazide) generic drug versions launch in Chile?

Generic name: aliskiren hemifumarate; hydrochlorothiazide
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: June 22, 2027
Generic Entry Controlled by: Chile Patent 2,007,001,837
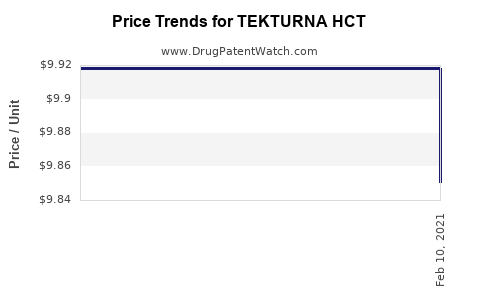
Drug Price Trends for TEKTURNA HCT
TEKTURNA HCT is a drug marketed by Noden Pharma. There is one patent protecting this drug and one Paragraph IV challenge. There has been litigation on patents covering TEKTURNA HCT

See drug price trends for TEKTURNA HCT.

The generic ingredient in TEKTURNA HCT is aliskiren hemifumarate; hydrochlorothiazide. Additional details are available on the aliskiren hemifumarate; hydrochlorothiazide profile page.

When can BYDUREON (exenatide synthetic) generic drug versions launch in Chile?

Generic name: exenatide synthetic
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: June 28, 2027
Generic Entry Controlled by: Chile Patent 2,007,001,915
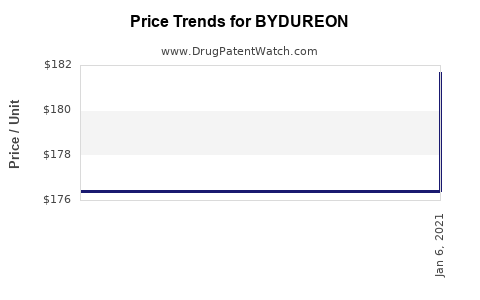
Drug Price Trends for BYDUREON
BYDUREON is a drug marketed by Astrazeneca Ab. There are seven patents protecting this drug. There has been litigation on patents covering BYDUREON

See drug price trends for BYDUREON.

The generic ingredient in BYDUREON is exenatide synthetic. Additional details are available on the exenatide synthetic profile page.

When can FARXIGA (dapagliflozin) generic drug versions launch in Chile?

Generic name: dapagliflozin
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: June 28, 2027
Generic Entry Controlled by: Chile Patent 2,007,001,915
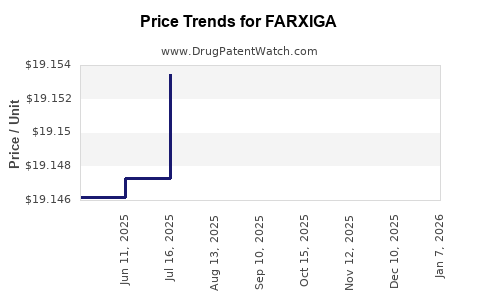
Drug Price Trends for FARXIGA
FARXIGA is a drug marketed by Astrazeneca Ab. There are seventeen patents protecting this drug and one Paragraph IV challenge. Fifteen tentatively approved generics are ready to enter the market. There has been litigation on patents covering FARXIGA

See drug price trends for FARXIGA.

The generic ingredient in FARXIGA is dapagliflozin. Additional details are available on the dapagliflozin profile page.

When can QTERN (dapagliflozin; saxagliptin hydrochloride) generic drug versions launch in Chile?

Generic name: dapagliflozin; saxagliptin hydrochloride
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: June 28, 2027
Generic Entry Controlled by: Chile Patent 2,007,001,915
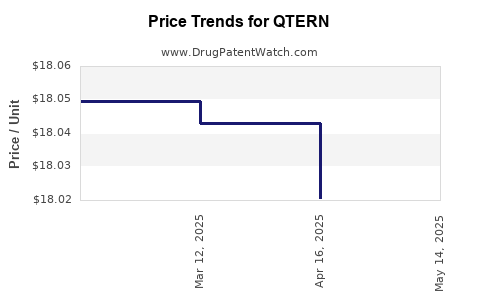
Drug Price Trends for QTERN
QTERN is a drug marketed by Astrazeneca Ab. There are seven patents protecting this drug and one Paragraph IV challenge. There has been litigation on patents covering QTERN

See drug price trends for QTERN.

The generic ingredient in QTERN is dapagliflozin; saxagliptin hydrochloride. Additional details are available on the dapagliflozin; saxagliptin hydrochloride profile page.

When can BRILINTA (ticagrelor) generic drug versions launch in Chile?

Generic name: ticagrelor
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: August 20, 2027
Generic Entry Controlled by: Chile Patent 2,007,002,421
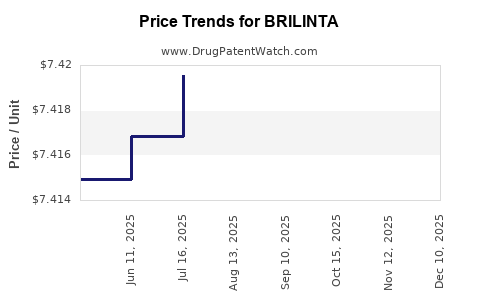
Drug Price Trends for BRILINTA
BRILINTA is a drug marketed by Astrazeneca. There are two patents protecting this drug and two Paragraph IV challenges. One tentatively approved generic is ready to enter the market. There has been litigation on patents covering BRILINTA

See drug price trends for BRILINTA.

The generic ingredient in BRILINTA is ticagrelor. Additional details are available on the ticagrelor profile page.

When can DUZALLO (allopurinol; lesinurad) generic drug versions launch in Chile?

Generic name: allopurinol; lesinurad
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: November 27, 2027
Generic Entry Controlled by: Chile Patent 2,008,003,529

Drug Price Trends for DUZALLO
DUZALLO is a drug marketed by Ironwood Pharms Inc. There are eight patents protecting this drug. There has been litigation on patents covering DUZALLO

See drug price trends for DUZALLO.

The generic ingredient in DUZALLO is allopurinol; lesinurad. Additional details are available on the allopurinol; lesinurad profile page.

When can DUZALLO (allopurinol; lesinurad) generic drug versions launch in Chile?

Generic name: allopurinol; lesinurad
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: November 27, 2027
Generic Entry Controlled by: Chile Patent 2,012,000,594

Drug Price Trends for DUZALLO
DUZALLO is a drug marketed by Ironwood Pharms Inc. There are eight patents protecting this drug. There has been litigation on patents covering DUZALLO

See drug price trends for DUZALLO.

The generic ingredient in DUZALLO is allopurinol; lesinurad. Additional details are available on the allopurinol; lesinurad profile page.

When can ZURAMPIC (lesinurad) generic drug versions launch in Chile?

Generic name: lesinurad
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: November 27, 2027
Generic Entry Controlled by: Chile Patent 2,008,003,529

ZURAMPIC is a drug marketed by Ironwood Pharms Inc. There are eight patents protecting this drug. There has been litigation on patents covering ZURAMPIC

See drug price trends for ZURAMPIC.

The generic ingredient in ZURAMPIC is lesinurad. Additional details are available on the lesinurad profile page.

When can ZURAMPIC (lesinurad) generic drug versions launch in Chile?

Generic name: lesinurad
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: November 27, 2027
Generic Entry Controlled by: Chile Patent 2,012,000,594

ZURAMPIC is a drug marketed by Ironwood Pharms Inc. There are eight patents protecting this drug. There has been litigation on patents covering ZURAMPIC

See drug price trends for ZURAMPIC.

The generic ingredient in ZURAMPIC is lesinurad. Additional details are available on the lesinurad profile page.

When can ALIQOPA (copanlisib dihydrochloride) generic drug versions launch in Chile?

Generic name: copanlisib dihydrochloride
DrugPatentWatch® Estimated Key Patent Expiration / Generic Entry Date: December 05, 2027
Generic Entry Controlled by: Chile Patent 2,007,003,508
Patent Title: COMPUESTOS DERIVADOS DE 2,3-DIHIDROIMIDAZOL[1,2-C]QUINAZOLINA; COMPOSICION FARMACEUTICA QUE COMPRENDE A DICHOS COMPUESTOS; Y SU USO PARA TRATAR ENFERMEDADES Y TRASTORNOS HIPERPROLIFERATIVOS ASOCIADOS A LA ANGIOGENESIS, TALES COMO INFLAMACION, ENFERME

ALIQOPA is a drug marketed by Bayer Healthcare. There are three patents protecting this drug.

See drug price trends for ALIQOPA.

The generic ingredient in ALIQOPA is copanlisib dihydrochloride. Additional details are available on the copanlisib dihydrochloride profile page.

Chile Branded and Generic Drug Market Assessment: Regulation, Patents, Opportunities and Challenges

Last updated: October 13, 2026

Chile is a high-income Latin American pharmaceutical market with strong private-sector purchasing, a large public procurement channel, expanding generic substitution, and a comparatively mature regulatory framework. Market access depends on registration with the Instituto de Salud Pública de Chile (ISP), compliance with bioequivalence requirements where applicable, procurement strategy, pricing economics, and protection under Chilean patent law.

The principal opportunities are generic medicines, biosimilars, hospital products, chronic-care therapies, specialty medicines, and public tenders through the Central de Abastecimiento del Sistema Nacional de Servicios de Salud (CENABAST). The main challenges are price competition, reference-pricing pressure, lengthy public procurement cycles, mandatory or expanding bioequivalence requirements, local regulatory execution, and relatively limited data exclusivity compared with the United States and European Union.

How large is the Chilean branded and generic drug market?

Chile has one of Latin America’s most developed pharmaceutical distribution systems. The market is divided between:

Segment Main purchasers Commercial characteristics
Private retail Pharmacy chains, independent pharmacies, private clinics, ISAPRE-linked patients Strong brand recognition, self-pay exposure and price sensitivity
Public outpatient FONASA beneficiaries, public hospitals, municipal health centers Procurement-driven, generic-heavy and budget constrained
Institutional and hospital Public hospitals, private hospitals and specialty centers Tender pricing, technical specifications and supply reliability
Government procurement CENABAST and public entities Large-volume contracts, centralized purchasing and strict delivery obligations
Specialty and high-cost medicines FONASA, hospitals and special coverage programs Reimbursement and clinical-evidence barriers

Chile’s retail pharmacy sector is concentrated. Cruz Verde, Salcobrand and Farmacias Ahumada have historically held substantial market share, while CENABAST has increased its role in public and, through negotiated programs, certain retail channels. The pharmacy sector has also faced competition-law scrutiny and enforcement relating to coordination and pricing practices.[1]

Branded medicines remain important in private retail and specialty care. Generics dominate many public tenders and are increasingly relevant in private channels because Chilean consumers pay a meaningful share of outpatient medicine costs directly. The commercial distinction between branded, generic and “similar” products is material: Chilean consumers and physicians may associate a branded generic with higher quality, while the public system generally emphasizes registration, bioequivalence, price and supply.

What is the regulatory pathway for medicines in Chile?

The ISP is Chile’s principal medicines regulator. A pharmaceutical product generally requires sanitary registration before commercialization. The core framework is established by the Código Sanitario and Decreto Supremo No. 3 of 2010, as amended.[2]

Registration categories

The ISP evaluates products through registration procedures that address:

  • Safety and efficacy;
  • Pharmaceutical quality;
  • Manufacturing standards;
  • Stability;
  • Labeling and packaging;
  • Therapeutic equivalence where required;
  • Pharmacovigilance obligations;
  • Importation and distribution controls.

Applications typically require a Chilean regulatory representative or local operational structure. Foreign manufacturers commonly work through a Chilean marketing authorization holder, distributor or regulatory-services provider.

For generic products, the submission usually relies on published scientific information, quality data and, where mandated, therapeutic-equivalence evidence. Innovator products require a more extensive clinical and pharmaceutical dossier unless an applicable abridged pathway is available.

FDA or EMA approval does not automatically authorize Chilean sales

Chile recognizes foreign regulatory information, but approval by the U.S. Food and Drug Administration or European Medicines Agency does not itself create a Chilean marketing authorization. The applicant must satisfy ISP requirements, submit the required dossier and comply with local labeling, administrative and post-market obligations.

The ISP has developed reliance and accelerated mechanisms for some products and regulatory situations, but the applicable pathway depends on product type, origin, public-health significance and current ISP rules.

What are Chile’s generic drug requirements?

Chile distinguishes medicines by pharmaceutical equivalence, therapeutic equivalence and branding. A generic product must be registered and must comply with applicable quality and equivalence requirements. The name “generic” does not remove the need for ISP authorization.

Bioequivalence requirements

Chile has progressively expanded bioequivalence requirements. The ISP identifies products and active ingredients subject to therapeutic-equivalence demonstration through official resolutions and technical standards. Depending on the active ingredient and dosage form, the applicant may need:

  • In vivo bioequivalence studies;
  • In vitro comparative dissolution;
  • Biowaiver evidence;
  • Comparative pharmaceutical equivalence;
  • Reference-product data;
  • A validated analytical method.

The requirement is particularly important for oral immediate-release products with active ingredients included in Chile’s therapeutic-equivalence program. Applicants must confirm the applicable product-specific standard before investing in development or registration.

Bioequivalence can create a meaningful barrier for smaller manufacturers because studies, comparator sourcing, analytical work and dossier preparation increase time and cost. It also creates an opportunity for manufacturers with established contract research and regulatory capabilities.

Generic substitution and pharmacy economics

Chile’s policy has moved toward greater use of interchangeable medicines, but the practical effect depends on:

  • Whether the product has demonstrated therapeutic equivalence;
  • How the prescription is written;
  • Pharmacy substitution practices;
  • Physician and patient confidence;
  • Reimbursement and retail pricing;
  • Availability of the product at the point of sale.

Products with an ISP-recognized therapeutic-equivalence designation have a stronger position in substitution-driven channels than registered products without such designation.

What is the Chilean patent framework for pharmaceutical products?

Chile grants patents under Law No. 19,039 on Industrial Property, administered by the Instituto Nacional de Propiedad Industrial (INAPI).[3]

Core patent terms

Issue Chilean position
Standard patent term 20 years from the filing date
Patent examination Substantive examination by INAPI
Pharmaceutical compounds Patentable if novelty, inventive step and industrial applicability are met
Formulations Patentable when statutory requirements are satisfied
Manufacturing processes Patentable when novel and inventive
Polymorphs and salts Potentially patentable, subject to patentability standards
Medical treatment methods Restricted or excluded in the conventional form
Second medical uses Can be protected through accepted claim formats, subject to Chilean practice
Patent linkage No U.S.-style automatic Orange Book linkage
Patent term extension Limited mechanisms may apply in cases of unjustified administrative delay, subject to statutory requirements

Chile is a Patent Cooperation Treaty member. International applications can enter the Chilean national phase, generally subject to the applicable national-phase deadline and local prosecution requirements.

Pharmaceutical patent strategies

Patent holders commonly evaluate protection for:

  • Active pharmaceutical ingredients;
  • Polymorphs, salts and crystalline forms;
  • Formulations and dosage forms;
  • Controlled-release systems;
  • Combination products;
  • Manufacturing processes;
  • Purification methods;
  • Specific dosing regimens;
  • Patient subpopulations;
  • Second medical uses;
  • Devices and drug-delivery systems.

Patent strength depends on claim scope, prosecution history, enablement, written support, prior-art exposure and the availability of commercially relevant alternatives. A compound patent with broad claims usually creates the strongest barrier. Formulation and method-of-use patents can be commercially important but are more vulnerable to invalidity or non-infringement arguments.

Does Chile have an Orange Book or Paragraph IV system?

Chile does not operate a direct equivalent of the U.S. FDA Orange Book. The ISP does not maintain a U.S.-style public listing that automatically links each generic application to all patents asserted against an innovator product.

Chile also does not use the U.S. Paragraph IV certification framework. A Chilean generic applicant generally does not obtain an automatic regulatory stay by challenging an innovator patent, and patent certification is not structured around the U.S. abbreviated new drug application model.

Patent disputes are handled through Chilean industrial-property and civil procedures. Regulatory approval and patent enforcement are separate legal issues. A generic product may obtain sanitary registration while still facing patent infringement risk if it is commercialized before relevant patent rights expire.

When do Chilean drug patents lose exclusivity?

The standard patent term is 20 years from filing, not 20 years from grant. The practical exclusivity date therefore depends on:

  1. The earliest Chilean or priority filing date;
  2. Whether the relevant patent entered through the PCT system;
  3. Whether a patent term adjustment or compensation mechanism applies;
  4. Whether related patents cover the same commercial product;
  5. Whether regulatory approval or reimbursement creates additional non-patent barriers.

Chile has data-protection rules for undisclosed test data relating to new chemical entities. Under Chile’s trade and regulatory framework, undisclosed safety and efficacy data may receive protection for a limited period, commonly five years for pharmaceutical products, subject to statutory conditions and exceptions.[4] Data protection is separate from patent protection. It does not extend an expired compound patent and may not prevent approval based on an independent regulatory dossier.

Exclusivity timeline

Protection Typical legal or commercial duration Principal barrier
Patent 20 years from filing Patent infringement
Pharmaceutical data protection Commonly five years for qualifying new chemical entities Reliance on protected undisclosed data
Regulatory registration No fixed market exclusivity by itself ISP authorization
Therapeutic-equivalence designation No fixed exclusivity period Supports substitution and procurement
Public procurement contract Contract-specific Tender terms and supply obligations
Trademark Renewable periods under Chilean law Brand and source identification

What patent litigation affects branded and generic medicines in Chile?

Chile does not have the same volume of pharmaceutical patent litigation as the United States. Disputes can nevertheless affect high-value products, particularly biologics, oncology therapies, specialty medicines and products with secondary patents.

Principal litigation routes

Patent disputes can involve:

  • Civil infringement actions;
  • Invalidity proceedings before INAPI;
  • Appeals before the Industrial Property Court;
  • Further review before the Supreme Court;
  • Preliminary injunction applications;
  • Customs or border measures in appropriate cases;
  • Unfair competition or trade-secret claims;
  • Regulatory and procurement challenges.

Patent validity can be challenged before INAPI. The challenger may argue lack of novelty, lack of inventive step, insufficient disclosure, lack of support, improper claim scope or other statutory defects.

Litigation and launch planning

A generic manufacturer should conduct a Chile-specific freedom-to-operate review before:

  • Filing the commercial registration;
  • Importing active pharmaceutical ingredient;
  • Manufacturing validation batches;
  • Participating in a public tender;
  • Advertising or launching the product.

Registration does not immunize a manufacturer from patent liability. Conversely, an unexpired patent does not automatically prevent the ISP from processing or granting a sanitary registration. This separation makes early patent review important.

What biosimilar risks exist in Chile?

Chile has a developing biosimilar market. The principal risks for reference-product manufacturers arise from:

  • Biosimilar registration under an abridged or comparative pathway;
  • Tender-driven substitution;
  • Hospital procurement;
  • Interchangeability expectations;
  • Price reductions;
  • Manufacturing and supply competition;
  • Limited differentiation between reference biologics and biosimilars in public purchasing.

Biosimilar developers face higher technical barriers than conventional generic manufacturers. They must establish comparability through analytical, nonclinical and clinical evidence appropriate to the product and applicable ISP requirements. Manufacturing consistency, immunogenicity control, cold-chain management and pharmacovigilance are central regulatory issues.

Reference-product companies retain opportunities through device differentiation, clinical-service programs, manufacturing reliability, additional indications, formulation changes and contracting. Those strategies do not replace patent analysis. Biologic patents may cover the molecule, formulation, production process, dosing regimen and delivery device.

What are the main regulatory opportunities in Chile?

Generic and branded-generic medicines

Opportunities are strongest in products with:

  • High out-of-pocket costs;
  • Large FONASA utilization;
  • Multiple manufacturers but weak supply reliability;
  • Expired or soon-to-expire compound patents;
  • Established bioequivalence pathways;
  • Chronic use and predictable demand;
  • CENABAST or hospital tender potential.

Chronic cardiovascular, metabolic, central nervous system and gastrointestinal products can offer volume, but competition is usually intense. Margin depends on procurement scale, local distribution and manufacturing cost.

Specialty and hospital medicines

Specialty medicines can command higher prices but face reimbursement and evidence barriers. Opportunities include oncology, rare diseases, immunology, hematology, hospital injectables and complex formulations. Public access may depend on FONASA coverage, GES benefits, Ley Ricarte Soto mechanisms or hospital budgets.[5]

Local manufacturing and contract operations

Chile is attractive as a regional commercial platform, but its domestic manufacturing base is smaller than Brazil’s, Mexico’s or Argentina’s. Local opportunities include:

  • Secondary packaging;
  • Quality-control laboratories;
  • Pharmaceutical distribution;
  • Cold-chain logistics;
  • Regulatory representation;
  • Contract manufacturing;
  • Pharmacovigilance services;
  • Clinical and bioequivalence operations.

Local production may improve tender competitiveness and supply resilience, but it does not automatically create preferential access in all procurement procedures.

What are the main commercial and regulatory challenges?

Public procurement and price pressure

CENABAST and public hospitals use competitive purchasing mechanisms that can produce substantial price compression. Winning a tender requires more than a low price. Suppliers must meet:

  • Delivery schedules;
  • Minimum shelf-life requirements;
  • Technical specifications;
  • Serialization or traceability obligations where applicable;
  • Recall and pharmacovigilance procedures;
  • Financial and performance guarantees.

Supply interruption can create contractual, reputational and regulatory consequences.

Concentrated distribution

Retail access is influenced by pharmacy-chain purchasing, shelf placement, substitution practices and promotional economics. A product with regulatory approval may still struggle without a local commercial partner or a reliable distribution strategy.

Registration and post-market compliance

Companies must manage:

  • Registration renewals and amendments;
  • Site changes;
  • Manufacturing changes;
  • Labeling updates;
  • Import permits;
  • Pharmacovigilance;
  • Product recalls;
  • Advertising restrictions;
  • Good manufacturing practice inspections.

Regulatory delays can affect launch timing, especially where the dossier requires bioequivalence, local administrative corrections or complex manufacturing documentation.

Advertising and promotion

Prescription-medicine promotion is subject to restrictions under Chilean health law. Promotional claims must remain consistent with the approved product information. Consumer-facing promotion is more constrained for prescription products than for non-prescription medicines.

How does Chile compare with other Latin American pharmaceutical markets?

Factor Chile Brazil Mexico Colombia
Regulatory authority ISP ANVISA COFEPRIS INVIMA
Patent term 20 years from filing 20 years from filing 20 years from filing 20 years from filing
Market structure Private retail plus strong public procurement Very large, complex and locally regulated Large retail and institutional market Strong public and private channels
Generic pressure High High High High
Regulatory complexity Moderate High Moderate to high Moderate
Public procurement role Significant through CENABAST and hospitals Significant, including centralized purchasing Significant Significant
Patent linkage No direct U.S.-style Orange Book system No direct U.S.-style system No direct U.S.-style system No direct U.S.-style system
Market-entry advantage Smaller, stable and commercially transparent Scale Scale and manufacturing base Andean regional access potential

Chile offers lower absolute market scale than Brazil or Mexico, but it can provide clearer commercial planning, relatively strong institutions and a credible test market for regional launches.

Which companies are challenging branded-drug exclusivity?

Generic and biosimilar competition comes from Chilean laboratories, multinational generic manufacturers, regional groups and imported products. Important local and regional participants have included Laboratorio Chile, Recalcine, Saval, Andrómaco, Bagó, Mintlab and other manufacturers and importers. Competitive intensity varies by molecule and channel.

For a branded product, the relevant competitor set should be assessed by:

  • ISP-registered products;
  • Therapeutic-equivalence status;
  • Active ingredient and dosage form;
  • CENABAST awards;
  • Hospital tender participation;
  • Pharmacy-chain availability;
  • Patent status;
  • Manufacturing source;
  • Reimbursement position.

A product count based only on registered names can overstate effective competition. Several registrations may be inactive, unavailable, or commercially insignificant.

What licensing and partnering models are used in Chile?

The dominant models are:

  • Exclusive local distribution;
  • Non-exclusive import and distribution;
  • Marketing authorization transfer;
  • Co-promotion;
  • Local manufacturing under license;
  • Contract packaging;
  • Regional licensing covering Chile and neighboring markets;
  • Tender-specific supply arrangements.

Licensing agreements are generally private and are not comprehensively disclosed in a centralized public database. Commercial diligence should focus on control of the Chilean registration, ownership of trademarks, responsibility for pharmacovigilance, manufacturing-change rights, tender authority, minimum purchase commitments and termination provisions.

Key Takeaways

  • Chile is a mature but price-sensitive pharmaceutical market with strong public procurement and concentrated private pharmacy distribution.
  • The ISP is the central regulator, and foreign approval does not replace Chilean sanitary registration.
  • Generic competition is strongest where products have therapeutic-equivalence recognition, high public utilization and expired compound patents.
  • Chile has no direct equivalent of the U.S. Orange Book or Paragraph IV certification system.
  • Pharmaceutical patents generally last 20 years from filing, with separate and limited data-protection rights for qualifying new chemical entities.
  • Formulation, process, dosage-regimen and second-use patents can materially affect generic launch timing.
  • Biosimilar competition is developing, with public tenders and hospital purchasing as major access channels.
  • CENABAST creates volume opportunities but imposes significant price, delivery and compliance pressure.
  • Local regulatory representation, pharmacovigilance capability and distribution execution are central to market access.
  • The highest-value opportunities are likely to involve complex generics, hospital products, biosimilars, chronic-care medicines and products with reliable supply advantages.

Frequently Asked Questions

Does Chile require generic medicines to prove bioequivalence?

Yes, when the active ingredient and product fall within the ISP’s therapeutic-equivalence requirements. The evidence may involve in vivo studies, in vitro testing, comparative dissolution or an accepted biowaiver.

Can a generic obtain Chilean registration before a patent expires?

Regulatory approval and patent rights are separate. The ISP may process or grant registration, but commercial launch before patent expiry can create infringement risk.

Is Chilean data exclusivity longer than U.S. data exclusivity?

No. Chile generally provides a shorter period for qualifying pharmaceutical data protection than the standard five-year U.S. new-chemical-entity period, although the legal mechanisms are not identical and must be analyzed under Chilean law.

Are biosimilars automatically interchangeable in Chile?

No. Registration, therapeutic equivalence and substitution are distinct issues. Interchangeability depends on applicable ISP requirements, product status and prescribing or procurement rules.

Does CENABAST purchase medicines for all Chilean patients?

No. CENABAST is a major public procurement and distribution institution, but medicines also move through public hospitals, municipal health services, private pharmacies, clinics and other channels.

References

  1. Fiscalía Nacional Económica. (2020). Estudio de mercado sobre medicamentos. Government of Chile. https://www.fne.gob.cl
  2. Instituto de Salud Pública de Chile. (2010). Decreto Supremo N° 3: Reglamento del Sistema Nacional de Control de los Productos Farmacéuticos de Uso Humano. Government of Chile. https://www.ispch.cl
  3. Instituto Nacional de Propiedad Industrial. (2006). Ley N° 19.039 de Propiedad Industrial, as amended. Government of Chile. https://www.inapi.cl
  4. World Trade Organization. (1994). Agreement on Trade-Related Aspects of Intellectual Property Rights. https://www.wto.org
  5. Ministerio de Salud de Chile. (2015). Ley N° 20.850, sistema de protección financiera para diagnósticos y tratamientos de alto costo. Government of Chile. https://www.minsal.cl

More… ↓

⤷  Start Trial

DrugPatentWatch cited by CNN, NEJM, Nature Journals, and more …

Make Better Decisions: Try a trial or see plans & pricing

Drugs may be covered by multiple patents or regulatory protections. All trademarks and applicant names are the property of their respective owners or licensors. Although great care is taken in the proper and correct provision of this service, thinkBiotech LLC does not accept any responsibility for possible consequences of errors or omissions in the provided data. The data presented herein is for information purposes only. There is no warranty that the data contained herein is error free. We do not provide individual investment advice. This service is not registered with any financial regulatory agency. The information we publish is educational only and based on our opinions plus our models. By using DrugPatentWatch you acknowledge that we do not provide personalized recommendations or advice. thinkBiotech performs no independent verification of facts as provided by public sources nor are attempts made to provide legal or investing advice. Any reliance on data provided herein is done solely at the discretion of the user. Users of this service are advised to seek professional advice and independent confirmation before considering acting on any of the provided information. thinkBiotech LLC reserves the right to amend, extend or withdraw any part or all of the offered service without notice.
