Last updated: August 30, 2026
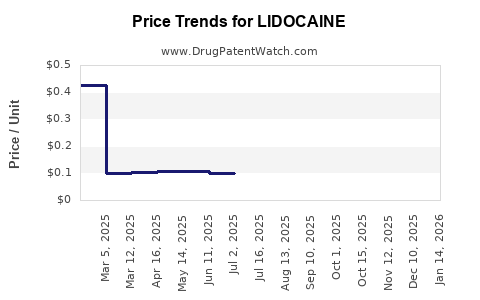
Lidocaine is a mature, globally marketed local anesthetic with a fragmented financial profile. Generic injectable, topical, dental, ophthalmic, and antiarrhythmic products generate high unit volume but limited pricing power. Commercial value is concentrated in differentiated delivery systems, including prescription patches, branded topical products, combination creams, and hospital formulations with supply or convenience advantages. The market has no single consolidated revenue base because lidocaine is sold across thousands of products, dosage forms, manufacturers, and countries.
How large is the lidocaine market?
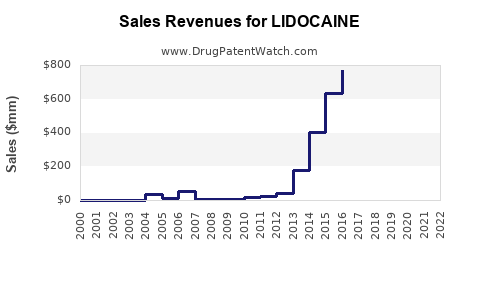
Lidocaine revenue is distributed across several product categories rather than reported as one pharmaceutical market.
| Segment |
Principal use |
Market structure |
Pricing profile |
Financial outlook |
| Injectable lidocaine |
Local anesthesia, nerve blocks, cardiac applications |
Generic and hospital-supply market |
Low to moderate |
Stable volume; periodic shortage-driven pricing |
| Topical creams, gels, ointments |
Dermatology, minor procedures, pain relief |
OTC and prescription |
Low to moderate |
Mature; brand differentiation matters |
| Transdermal patches |
Postherpetic neuralgia and localized pain |
Branded and generic products |
Higher than commodity generics |
More attractive specialty segment |
| Dental cartridges |
Dental anesthesia |
Dental suppliers and generic manufacturers |
Moderate |
Stable procedure-linked demand |
| Lidocaine/prilocaine creams |
Dermal anesthesia |
Branded and generic combination products |
Moderate |
Defensible through formulation and labeling |
| Antiarrhythmic injection |
Ventricular arrhythmias |
Hospital and specialty injectable suppliers |
Low |
Small but clinically important |
| Ophthalmic products |
Surface anesthesia |
Institutional and specialty markets |
Moderate |
Procedure-driven and regulated |
Public pharmaceutical companies generally do not report lidocaine as a standalone revenue line. Product sales are often combined with other local anesthetics, hospital injectables, dermatology products, or pain medicines. Commercial estimates from syndicated market-research providers therefore vary materially according to whether they include OTC products, dental products, combination formulations, and hospital sales.
The economically relevant distinction is between commodity lidocaine and differentiated lidocaine. Commodity products compete mainly on manufacturing cost, supply reliability, and distribution. Differentiated products can command higher prices through delivery technology, dosing convenience, prescription positioning, or formulation patents.
What is the financial trajectory for lidocaine?
The base market is mature and volume-driven. Financial growth is more likely to come from mix shift than from broad molecule-level expansion.
Commodity lidocaine
Injectable vials, topical gels, creams, ointments, and dental cartridges are largely generic. Their financial trajectory is characterized by:
- Low barriers to formulation entry.
- Multiple approved suppliers.
- Reimbursement and hospital purchasing pressure.
- Limited opportunity for sustained price increases.
- Revenue sensitivity to manufacturing interruptions and shortages.
- High importance of sterile manufacturing capacity.
Generic lidocaine can produce recurring revenue because it is embedded in routine medical, dental, emergency, and procedural care. The trade-off is low average selling price and intense procurement competition.
Specialty lidocaine
Specialty products have stronger revenue potential because they address convenience, adherence, tolerability, or targeted delivery. Prescription lidocaine patches are the clearest example. A patch can command a substantially higher price than an equivalent commodity topical product, although generic competition and payer controls limit long-term margins.
The financial trajectory for specialty lidocaine depends on three variables:
- Whether the product has a differentiated FDA-approved indication.
- Whether patents protect the formulation, adhesive, delivery profile, or manufacturing process.
- Whether the manufacturer can preserve formulary access against lower-cost generics.
Supply-driven revenue
Lidocaine periodically benefits from shortages affecting injectable anesthetics or hospital products. FDA shortage records have identified lidocaine products at different points in the supply chain, often because of manufacturing constraints, raw-material issues, or demand changes. Shortage conditions can increase revenue for available suppliers, but the benefit is generally temporary and can be offset by regulatory scrutiny, allocation requirements, and subsequent price normalization.
Which companies manufacture and commercialize lidocaine?
The competitive field includes multinational pharmaceutical companies, generic manufacturers, hospital-supply companies, dental suppliers, and specialty-product developers.
| Company or group |
Relevant position |
| Fresenius Kabi |
Hospital injectable and anesthetic products |
| Pfizer and legacy Hospira operations |
Injectable hospital medicines, including local anesthetic products in selected markets |
| Hikma Pharmaceuticals |
Generic injectable portfolio and hospital products |
| Sagent Pharmaceuticals |
Institutional injectable products |
| Eugia Pharma Specialities and other generic manufacturers |
Injectable and topical supply |
| Scilex Holding |
ZTlido prescription lidocaine topical system |
| AstraZeneca and legacy branded operations |
EMLA-related historical commercial position in some markets |
| Taro Pharmaceutical and dermatology manufacturers |
Topical prescription and OTC products |
| Dental-product suppliers |
Lidocaine cartridges and dental anesthetic formulations |
| Regional generic manufacturers |
Broad topical, injectable, and dental supply |
Company participation varies by jurisdiction and product. A company may hold a marketing authorization in one country while relying on a contract manufacturer in another. Manufacturer concentration is usually higher for sterile injectable products than for topical products.
What FDA regulatory status applies to lidocaine?
Lidocaine is an FDA-approved active ingredient used in multiple regulatory categories:
- Prescription drugs.
- Over-the-counter topical products under applicable monographs and labeling requirements.
- Generic injectable products approved through abbreviated new drug applications.
- Combination products, including lidocaine/prilocaine.
- Drug-device or delivery-system products, depending on the product design.
- Medical and dental products supplied for professional use.
The regulatory pathway depends on dosage form and indication. A conventional generic injection generally follows the ANDA pathway. A novel topical delivery system may require an abbreviated pathway if it can demonstrate pharmaceutical equivalence and bioequivalence, or a more complex approval strategy if the product differs materially from the reference product.
The FDA Orange Book identifies approved prescription products and patent or exclusivity information where applicable. Lidocaine’s broad generic availability means that molecule-level regulatory exclusivity has largely expired. Commercial protection therefore depends on product-specific approvals, patents, manufacturing capability, and market access rather than basic active-ingredient exclusivity. (U.S. Food and Drug Administration, 2024a)
What patents protect lidocaine products?
The core lidocaine compound is long off patent. The relevant patent landscape covers product design rather than the active ingredient.
Formulation patents
Potential formulation claims include:
- Adhesive matrices for transdermal patches.
- Controlled-release systems.
- Crystallization control.
- Solubilization and penetration-enhancement systems.
- Lidocaine/prilocaine combinations.
- Low-irritation topical vehicles.
- Stable injectable compositions.
- Preservative systems.
- Particle-size and suspension characteristics.
Formulation patents can delay direct substitution when the FDA-approved product has a distinct dosage form or delivery profile. Their commercial value depends on whether a generic applicant can design around the claims or challenge them through Paragraph IV certification.
Method-of-use patents
Method-of-use claims may cover:
- Treatment of postherpetic neuralgia.
- Localized neuropathic pain.
- Procedural anesthesia.
- Specific dosing schedules.
- Use in defined patient populations.
- Application to particular anatomical sites.
Method-of-use patents have limited blocking power when physicians can prescribe the drug for non-patented uses. Their value is higher when the patented indication drives a substantial share of product sales and when labeling restrictions are enforceable.
Delivery-system patents
Delivery patents are commercially important for products such as lidocaine patches, topical sprays, and controlled-release systems. Claims may cover the composition, backing layer, adhesive, drug loading, release rate, or manufacturing sequence.
A delivery-system patent estate is stronger when it includes multiple claim categories and when the product demonstrates clinically relevant performance that is difficult to reproduce with a simple formulation change.
When does lidocaine lose exclusivity?
Lidocaine as an active ingredient has already lost basic compound exclusivity. Generic competition is established across injections, topical products, dental formulations, and several combination products.
The remaining exclusivity timeline is product-specific:
| Product type |
Compound exclusivity |
Remaining protection |
| Conventional lidocaine injection |
Expired |
Formulation, process, supply, and regulatory approval considerations |
| Generic topical cream or gel |
Expired |
Limited formulation or brand protection |
| Lidocaine/prilocaine cream |
Expired at the active-ingredient level |
Product-specific patents, trademarks, and formulation differentiation |
| Prescription lidocaine patch |
Expired at the molecule level |
Delivery-system patents, method-of-use patents, and regulatory listings |
| OTC lidocaine product |
No meaningful compound exclusivity |
Brand, packaging, monograph compliance, and distribution |
| Novel combination or delivery system |
May have later product protection |
Patents and regulatory exclusivity tied to the specific product |
Patent expiration cannot be assigned to "lidocaine" as one date. Each product requires review of FDA Orange Book listings, issued patents, terminal disclaimers, patent-term adjustments, pediatric extensions, and litigation outcomes. (U.S. Food and Drug Administration, 2024a)
What is the Orange Book status of lidocaine?
The Orange Book status is product-specific. Conventional lidocaine products may have no active listed patents, while branded delivery systems can have one or more patents listed against the approved product.
For commercial diligence, the relevant review should distinguish:
- Active ingredient.
- Strength.
- Dosage form.
- Route of administration.
- Reference listed drug.
- Listed patents.
- Pediatric exclusivity.
- Labeling restrictions.
- Approved generic applicants.
- Therapeutic-equivalence codes.
A patent listed for a patch does not automatically block a generic cream or injectable product. Conversely, a generic patch applicant may face both formulation patents and method-of-use patents even though the underlying lidocaine compound is unprotected.
Which companies are challenging branded lidocaine products?
Generic challenges are most relevant to branded delivery systems, particularly prescription patches and combination products. A Paragraph IV challenge can assert that a listed patent is invalid, unenforceable, or not infringed. The commercial effect depends on the timing of the filing, the sponsor’s litigation response, any 30-month stay, and whether the generic applicant receives approval.
For conventional lidocaine products, generic competition is already established and Paragraph IV litigation has less strategic importance. For differentiated patches, the first approved generic can materially reduce price and market share, particularly when the product has limited clinical differentiation.
FDA approval of an ANDA does not itself resolve patent infringement. The applicant’s certification and any resulting litigation determine whether commercial launch can proceed before patent expiration or settlement.
What patent litigation and settlements affect lidocaine?
Lidocaine litigation is concentrated in differentiated products rather than commodity injections. Common disputes involve:
- Whether a patch or topical product is a complex dosage form.
- Whether the proposed generic has the same drug release profile.
- Whether adhesive or backing-layer claims are infringed.
- Whether a method-of-use patent can block a labeled generic use.
- Whether a patent was properly listed in the Orange Book.
- Whether a settlement delays generic entry.
Settlement economics depend on the branded product’s remaining sales, the strength of the asserted claims, the number of potential generic entrants, and the date of permitted launch. An authorized generic can reduce the value of a settlement by increasing price competition before independent generic entry.
No single litigation outcome determines the market for lidocaine because most sales occur outside the litigated product category.
Is there biosimilar risk for lidocaine?
There is no biosimilar risk for lidocaine. Lidocaine is a small-molecule drug, not a biologic. Competitive risk comes from:
- ANDA-approved generics.
- Authorized generics.
- 505(b)(2) products.
- OTC substitutes.
- Alternative local anesthetics.
- Non-drug delivery systems.
- Hospital purchasing substitutions.
The closest therapeutic competitors include bupivacaine, ropivacaine, mepivacaine, prilocaine, chloroprocaine, and tetracaine. Substitution depends on duration of action, toxicity profile, onset, procedure type, physician preference, and institutional protocols.
How does lidocaine compare with competing local anesthetics?
| Attribute |
Lidocaine |
Bupivacaine |
Ropivacaine |
Mepivacaine |
Prilocaine |
| Onset |
Rapid |
Slower |
Slower |
Rapid |
Moderate |
| Duration |
Short to intermediate |
Long |
Long |
Intermediate |
Intermediate |
| Primary advantage |
Versatility and familiarity |
Long anesthesia |
Long duration with differentiated safety profile |
Dental and procedural utility |
Combination topical use |
| Generic competition |
Extensive |
Extensive |
Extensive |
Extensive |
Extensive |
| Pricing power |
Low for commodity products |
Low to moderate |
Moderate in specialty use |
Low |
Low to moderate |
| Main commercial barrier |
Supply and manufacturing |
Institutional preference |
Clinical differentiation |
Mature generic market |
Formulation and combination products |
Lidocaine remains difficult to displace because it is familiar, inexpensive, rapidly acting, and available in many dosage forms. Competitors can take share in procedures requiring longer duration or different pharmacokinetic characteristics.
What manufacturing and intellectual-property barriers exist?
Sterile injectable manufacturing is the most significant operational barrier. Requirements include validated aseptic processing, container-closure integrity, particulate control, stability data, and reliable supply of active pharmaceutical ingredient and packaging components. A company may hold an approved product but remain commercially vulnerable if it lacks redundant manufacturing capacity.
Topical products have lower manufacturing barriers but can still require complex development work when the reference product has a specialized delivery system. Generic equivalence may require comparative adhesion, release, irritation, sensitization, and performance testing.
The strongest commercial positions combine:
- An approved product with established demand.
- Reliable manufacturing capacity.
- Multiple suppliers for key materials.
- Product-specific patent protection.
- A differentiated label or delivery system.
- Hospital, dental, or specialty distribution access.
How much revenue exposure is at risk from generic entry?
Revenue exposure varies sharply by product type.
| Revenue source |
Generic-entry exposure |
Expected impact |
| Commodity injectable |
Already exposed |
Price pressure and contract losses |
| OTC cream or gel |
High |
Brand erosion and retailer substitution |
| Dental cartridge |
Moderate to high |
Tender and distributor competition |
| Branded patch |
High after first generic approval |
Rapid price and share erosion |
| Combination cream |
Moderate |
Depends on formulation complexity |
| Shortage-constrained injectable |
Temporarily lower |
Supply availability can support pricing |
| Novel delivery system |
Delayed |
Patent and regulatory complexity can extend differentiation |
A branded patch can experience a steep decline after multiple generic entrants because payers use substitution rules and pharmacy benefit controls. The decline may be slower when the brand has strong physician recognition, a favorable formulary position, or a delivery system that generic applicants cannot easily reproduce.
What licensing deals matter for lidocaine?
Lidocaine licensing is usually product-specific rather than molecule-wide. Relevant deal structures include:
- Licensing of transdermal delivery technology.
- Regional commercialization rights.
- Contract manufacturing and supply agreements.
- Co-promotion of prescription patches.
- Acquisition of branded topical portfolios.
- Licensing of combination formulations.
The economic value of a licensing transaction depends on patent life, approval status, manufacturing requirements, and the ability to maintain reimbursement. A license covering ordinary generic lidocaine has limited strategic value unless it includes manufacturing capacity, a protected formulation, or an established distribution channel.
What generic launch scenarios exist for lidocaine?
Scenario 1: Commodity continuation
Generic injections and topical products continue to sell at low prices. Revenue remains stable through procedural demand, but margins depend on manufacturing efficiency and supply reliability.
Scenario 2: Patch erosion
A first generic lidocaine patch enters after patent resolution or settlement. The branded product loses volume and faces price reductions. The rate of decline accelerates when additional ANDA applicants launch.
Scenario 3: Supply disruption
A manufacturing interruption reduces market supply. Competitors with available inventory gain temporary share and may receive higher realized prices. FDA intervention and new supplier approvals later restore competition.
Scenario 4: Specialty reformulation
A manufacturer develops a new delivery system, combination product, or patient-use format. Revenue shifts from commodity pricing toward specialty pricing, but regulatory and patent-development costs increase.
What is the geographic outlook for lidocaine?
North America and Europe have mature generic markets. Growth is more likely to come from procedure volumes, hospital procurement changes, specialty patches, and emerging-market access than from compound exclusivity.
Geographic economics differ:
- United States: strong generic substitution, complex patent procedures, payer pressure, and periodic injectable shortages.
- Europe: national tendering, reference pricing, and fragmented market authorizations.
- Japan: regulated pricing and established local suppliers.
- China: volume-based procurement can sharply compress generic prices.
- Emerging markets: higher growth potential but lower prices, local manufacturing competition, and registration barriers.
Manufacturers with regional regulatory approvals and local distribution can outperform companies relying on a single market.
How strong is the lidocaine patent estate?
The overall lidocaine patent estate is weak at the molecule level and variable at the product level.
| Estate category |
Strength |
| Core compound |
None of practical commercial significance |
| Conventional injection |
Low |
| Basic topical products |
Low |
| Combination formulations |
Moderate, depending on claims |
| Transdermal patches |
Moderate to strong for surviving, well-drafted claims |
| Manufacturing processes |
Moderate if difficult to design around |
| Method-of-use claims |
Variable and indication-dependent |
| Trademarks and brand assets |
Useful commercially but not equivalent to patent protection |
The highest-value claims are those that cover a commercially necessary delivery profile and cannot be bypassed through a simple vehicle, adhesive, dose, or labeling change.
Key Takeaways
- Lidocaine is a mature, genericized local anesthetic with broad clinical use and fragmented revenue.
- Commodity injections, creams, gels, and dental products have limited pricing power.
- Prescription patches and specialized delivery systems carry the strongest commercial economics.
- Lidocaine has no meaningful biosimilar risk because it is a small-molecule drug.
- Generic entry risk is highest for branded patches and other higher-priced differentiated products.
- Sterile manufacturing capacity and supply reliability are major competitive assets.
- The core lidocaine compound is no longer protected; remaining exclusivity is product-specific.
- Orange Book and patent analysis must be performed by product, dosage form, strength, and indication.
- Financial growth is more likely to come from specialty formulations, geographic expansion, and supply availability than from molecule-level innovation.
- A branded lidocaine product’s revenue can decline rapidly after the first therapeutically substitutable generic enters.
FAQs
Is lidocaine still profitable for pharmaceutical companies?
Yes, but profitability depends on the product category. Commodity lidocaine generally produces low margins and relies on scale. Branded patches, combination creams, and specialized delivery systems can generate higher margins before generic entry.
Does lidocaine have patent protection in the United States?
The active ingredient does not have meaningful remaining compound protection. Certain lidocaine products may have formulation, delivery-system, manufacturing, or method-of-use patents.
Can a generic lidocaine patch launch before all patents expire?
It may launch after a patent challenge, settlement, licensing agreement, court decision, or other legally permitted pathway. FDA approval and patent clearance are separate issues.
Which lidocaine product has the greatest commercial differentiation?
Prescription transdermal systems generally have greater differentiation than standard injections, creams, or gels because they incorporate adhesive, release, dosing, and delivery characteristics.
Are lidocaine shortages likely to increase prices?
Shortages can temporarily increase prices or shift demand to available suppliers. The effect depends on inventory, alternative suppliers, hospital contracts, and the duration of the disruption.
References
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/orange-book-data-files
-
U.S. Food and Drug Administration. (2024b). Drug shortages. https://www.fda.gov/drugs/drug-safety-and-availability/drug-shortages
-
U.S. Food and Drug Administration. (2024c). Generic drugs. https://www.fda.gov/drugs/buying-using-medicine-safely/generic-drugs
-
U.S. Food and Drug Administration. (2024d). Approved drug products. Drugs@FDA. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (2024e). Approved drug product labels. DailyMed. https://dailymed.nlm.nih.gov/dailymed/
-
U.S. Patent and Trademark Office. (2024). Patent term adjustment and patent term extension resources. https://www.uspto.gov/patents/laws/patent-term-calculator
-
U.S. Securities and Exchange Commission. (2024). Company filings and financial disclosures. EDGAR. https://www.sec.gov/edgar/search/