Esomeprazole magnesium - Generic Drug Details
✉ Email this page to a colleague
What are the generic sources for esomeprazole magnesium and what is the scope of patent protection?
Esomeprazole magnesium
is the generic ingredient in five branded drugs marketed by Alkem Labs Ltd, Amneal Pharms Ny, Aurobindo Pharma Ltd, Cipla, Cisen, Cspc Ouyi, Dr Reddys, Ethypharm, Glenmark Speclt, Granules, Graviti Pharms, Guangzhou Novaken, Hec Pharm, Hetero Labs Ltd Iii, Indchemie Health, Lannett Co Inc, Macleods Pharms, Mylan, Prinston Inc, Sun Pharm, Torrent, Zhejiang Yongtai, Zydus Pharms, Astrazeneca, Aurobindo Pharma, Guardian Drug, Marksans Pharma, Perrigo R And D, Pharmobedient, Astrazeneca Lp, P And L, Dexcel, Actavis Labs Fl Inc, Ajanta Pharma Ltd, Sciegen Pharms, and Horizon, and is included in sixty-one NDAs. There are two patents protecting this compound and two Paragraph IV challenges. Additional information is available in the individual branded drug profile pages.One hundred and fifteen suppliers are listed for this compound. There is one tentative approval for this compound.
Summary for esomeprazole magnesium
| International Patents: | 4 |
| US Patents: | 2 |
| Tradenames: | 5 |
| Applicants: | 36 |
| NDAs: | 61 |
| Finished Product Suppliers / Packagers: | 113 |
| Raw Ingredient (Bulk) Api Vendors: | 1 |
| Clinical Trials: | 24 |
| Patent Applications: | 2,819 |
| Drug Prices: | Drug price trends for esomeprazole magnesium |
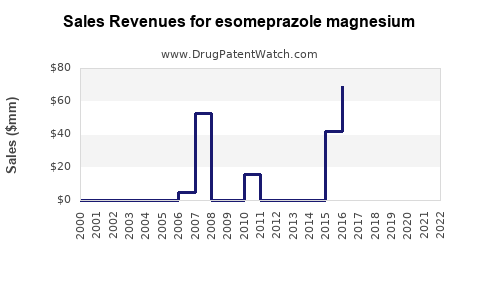
| Drug Sales Revenues: | Drug sales revenues for esomeprazole magnesium |
| Patent Litigation and PTAB cases: | See patent lawsuits and PTAB cases for esomeprazole magnesium |
| What excipients (inactive ingredients) are in esomeprazole magnesium? | esomeprazole magnesium excipients list |
| DailyMed Link: | esomeprazole magnesium at DailyMed |

Recent Clinical Trials for esomeprazole magnesium
Identify potential brand extensions & 505(b)(2) entrants
| Sponsor | Phase |
|---|---|
| Jiangsu Sinorda Biomedicine Co., Ltd | PHASE1 |
| Livzon Pharmaceutical Group Inc. | PHASE3 |
| Bio-innova Co., Ltd | PHASE1 |
Generic filers with tentative approvals for ESOMEPRAZOLE MAGNESIUM
| Applicant | Application No. | Strength | Dosage Form |
| ⤷ Start Trial | ⤷ Start Trial | EQ 20MG BASE;500MG | TABLET, DELAYED RELEASE;ORAL |
| ⤷ Start Trial | ⤷ Start Trial | EQ 20MG BASE;375MG | TABLET, DELAYED RELEASE;ORAL |
The 'tentative' approval signifies that the product meets all FDA standards for marketing, and, but for the patents / regulatory protections, it would approved.
Pharmacology for esomeprazole magnesium
| Drug Class | Proton Pump Inhibitor |
| Mechanism of Action | Cytochrome P450 2C19 Inhibitors Proton Pump Inhibitors |
Anatomical Therapeutic Chemical (ATC) Classes for esomeprazole magnesium
Paragraph IV (Patent) Challenges for ESOMEPRAZOLE MAGNESIUM
| Tradename | Dosage | Ingredient | Strength | NDA | ANDAs Submitted | Submissiondate |
|---|---|---|---|---|---|---|
| NEXIUM | Delayed-release for Oral Suspension | esomeprazole magnesium | 2.5 mg and 5 mg | 021957 | 1 | 2018-09-24 |
| NEXIUM | Delayed-release for Oral Suspension | esomeprazole magnesium | 10 mg | 022101 | 1 | 2018-07-06 |
| NEXIUM 24HR | Delayed-release Capsules | esomeprazole magnesium | 20 mg | 204655 | 2014-04-24 | |
| NEXIUM | Delayed-release for Oral Suspension | esomeprazole magnesium | 20 mg and 40 mg | 021957 | 1 | 2013-08-01 |
| NEXIUM | Delayed-release Capsules | esomeprazole magnesium | 20 mg and 40 mg | 021153 | 1 | 2005-08-05 |
US Patents and Regulatory Information for esomeprazole magnesium
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | TE | Type | RLD | RS | Patent No. | Patent Expiration | Product | Substance | Delist Req. | Exclusivity Expiration |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Graviti Pharms | ESOMEPRAZOLE MAGNESIUM | esomeprazole magnesium | CAPSULE, DELAYED REL PELLETS;ORAL | 213486-001 | Mar 19, 2021 | AB | RX | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Aurobindo Pharma Ltd | ESOMEPRAZOLE MAGNESIUM | esomeprazole magnesium | TABLET, DELAYED RELEASE;ORAL | 214473-001 | Jul 12, 2023 | OTC | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| Sun Pharm | ESOMEPRAZOLE MAGNESIUM | esomeprazole magnesium | CAPSULE, DELAYED RELEASE;ORAL | 212866-001 | May 4, 2020 | OTC | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >TE | >Type | >RLD | >RS | >Patent No. | >Patent Expiration | >Product | >Substance | >Delist Req. | >Exclusivity Expiration |
Expired US Patents for esomeprazole magnesium
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | Patent No. | Patent Expiration |
|---|---|---|---|---|---|---|---|
| Astrazeneca | NEXIUM | esomeprazole magnesium | CAPSULE, DELAYED REL PELLETS;ORAL | 021153-001 | Feb 20, 2001 | 4,255,431 | ⤷ Start Trial |
| Astrazeneca | NEXIUM | esomeprazole magnesium | CAPSULE, DELAYED REL PELLETS;ORAL | 021153-002 | Feb 20, 2001 | 4,508,905 | ⤷ Start Trial |
| Astrazeneca | NEXIUM | esomeprazole magnesium | CAPSULE, DELAYED REL PELLETS;ORAL | 021153-002 | Feb 20, 2001 | 4,636,499 | ⤷ Start Trial |
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >Patent No. | >Patent Expiration |
International Patents for esomeprazole magnesium
| Country | Patent Number | Title | Estimated Expiration |
|---|---|---|---|
| Australia | 2017285390 | Stable orally disintegrating pharmaceutical compositions | ⤷ Start Trial |
| European Patent Office | 3471708 | COMPOSITIONS PHARMACEUTIQUES STABLES À DÉSINTÉGRATION ORALE (STABLE ORALLY DISINTEGRATING PHARMACEUTICAL COMPOSITIONS) | ⤷ Start Trial |
| European Patent Office | 3932396 | COMPOSITIONS PHARMACEUTIQUES STABLES À DÉSINTÉGRATION ORALE (STABLE ORALLY DISINTEGRATING PHARMACEUTICAL COMPOSITIONS) | ⤷ Start Trial |
| >Country | >Patent Number | >Title | >Estimated Expiration |
Supplementary Protection Certificates for esomeprazole magnesium
| Patent Number | Supplementary Protection Certificate | SPC Country | SPC Expiration | SPC Description |
|---|---|---|---|---|
| 1411900 | 2011/016 | Ireland | ⤷ Start Trial | PRODUCT NAME: NAPROXEN AND ESOMEPRAZOLE MODIFIED-RELEASE TABLETS; NAT REGISTRATION NO/DATE: PA0970/060/001 20101221; FIRST REGISTRATION NO/DATE: PL17901/0263-0001 20101105 |
| 0984957 | 2012/048 | Ireland | ⤷ Start Trial | PRODUCT NAME: A COMBINATION PRODUCT COMPRISING ASPIRIN AND ESOMEPRAZOLE MAGNESIUM TRIHYDRATE; NAT REGISTRATION NO/DATE: PA 970/063/001 20120831; FIRST REGISTRATION NO/DATE: 5402359; 5402367 5402375 20110812 |
| 1411900 | 2011C/016 | Belgium | ⤷ Start Trial | PRODUCT NAME: NAPROXENE ET ESOMEPRAZOLE (SOUS LA FORME D'ESOMEPRAZOLE MAGNESIUM TRIHYDRATE); AUTHORISATION NUMBER AND DATE: BE382505 20101214 |
| >Patent Number | >Supplementary Protection Certificate | >SPC Country | >SPC Expiration | >SPC Description |
ESOMEPRAZOLE MAGNESIUM: Market dynamics and financial trajectory by channel, pricing, and exclusivity risk
More… ↓
Make Better Decisions: Try a trial or see plans & pricing
Drugs may be covered by multiple patents or regulatory protections. All trademarks and applicant names are the property of their respective owners or licensors. Although great care is taken in the proper and correct provision of this service, thinkBiotech LLC does not accept any responsibility for possible consequences of errors or omissions in the provided data. The data presented herein is for information purposes only. There is no warranty that the data contained herein is error free. We do not provide individual investment advice. This service is not registered with any financial regulatory agency. The information we publish is educational only and based on our opinions plus our models. By using DrugPatentWatch you acknowledge that we do not provide personalized recommendations or advice. thinkBiotech performs no independent verification of facts as provided by public sources nor are attempts made to provide legal or investing advice. Any reliance on data provided herein is done solely at the discretion of the user. Users of this service are advised to seek professional advice and independent confirmation before considering acting on any of the provided information. thinkBiotech LLC reserves the right to amend, extend or withdraw any part or all of the offered service without notice.
ISSN: 2162-2639

Privacy and Cookies
Terms & Conditions
Site Map
DrugPatentWatch Alternatives
LOE / Major Patent Expirations 2026 - 2027
NCE-1 Patent Challenge Dates 2026 - 2027
Friedman, Yali. "DrugPatentWatch" DrugPatentWatch, thinkBiotech, 2026, www.DrugPatentWatch.com.
See Primary Research Papers Citing DrugPatentWatch