Share This Page
Drug Sales Trends for esomeprazole magnesium
✉ Email this page to a colleague
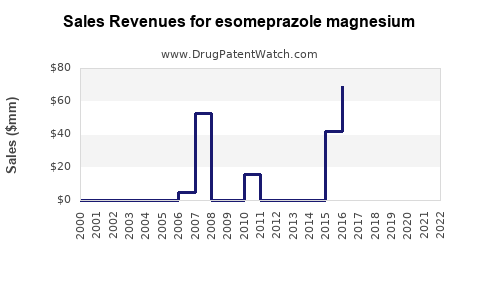
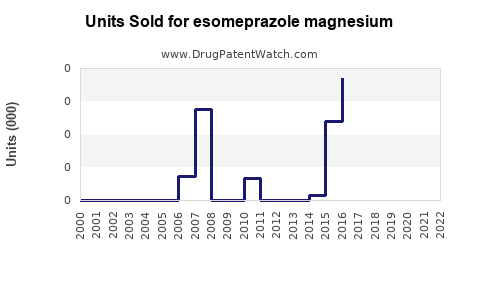
Annual Sales Revenues and Units Sold for esomeprazole magnesium
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ESOMEPRAZOLE MAGNESIUM | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ESOMEPRAZOLE MAGNESIUM | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ESOMEPRAZOLE MAGNESIUM | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ESOMEPRAZOLE MAGNESIUM | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ESOMEPRAZOLE MAGNESIUM | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Esomeprazole Magnesium Market Analysis, Sales Forecast, Patent Status, and Generic Competition
Esomeprazole magnesium is a mature proton-pump inhibitor marketed primarily as Nexium and through multiple generic and OTC products. The U.S. prescription product lost effective market exclusivity years ago, and competition is driven by generic price erosion, retail OTC distribution, formulation economics, and brand recognition rather than by patent protection. Global branded and generic sales are likely to remain substantial because esomeprazole is widely used for gastroesophageal reflux disease, erosive esophagitis, peptic-ulcer disease, and Helicobacter pylori eradication regimens.
The base-case market outlook is low-single-digit annual unit growth with declining average selling prices in prescription channels. A reasonable global sales estimate for esomeprazole magnesium products across prescription, OTC, and institutional channels is approximately $1.2 billion to $1.8 billion in 2024, with a modeled market value of $1.0 billion to $1.6 billion by 2029. The range reflects limited public disclosure of generic sales and the difficulty of separating esomeprazole magnesium from broader esomeprazole and PPI reporting.
What is esomeprazole magnesium and how is it used?
Esomeprazole magnesium is the magnesium salt of esomeprazole, the S-isomer of omeprazole. It suppresses gastric acid secretion by inhibiting the gastric H+/K+-ATPase proton pump in parietal cells.
| Attribute | Details |
|---|---|
| Active ingredient | Esomeprazole magnesium |
| Pharmacological class | Proton-pump inhibitor |
| Primary brand | Nexium |
| Main indications | GERD, erosive esophagitis, maintenance of healing, pathological hypersecretory conditions, H. pylori combination therapy |
| Common dosage forms | Delayed-release capsules, delayed-release tablets, oral granules, injectable esomeprazole formulations |
| Common strengths | 20 mg and 40 mg |
| Primary channels | Retail prescription, OTC retail, hospitals, mail order, e-commerce |
| Originator | AstraZeneca |
| FDA status | Approved prescription and OTC products |
| Generic status | Multiple generic approvals and commercial products |
The magnesium product is generally formulated as an enteric-coated delayed-release dosage form because esomeprazole is acid-labile. Formulation performance depends on protection from gastric degradation, release in the duodenum, particle size, salt form, coating composition, and bioequivalence.
How large is the esomeprazole magnesium market?
The market is fragmented across branded OTC products, generic prescription products, hospital purchasing, and private-label retail products. Public company reports usually disclose broader gastrointestinal or regional categories rather than esomeprazole magnesium revenue alone.
Estimated 2024 market structure
| Segment | Estimated 2024 value | Market characteristics |
|---|---|---|
| U.S. OTC esomeprazole | $350 million-$550 million | Brand, store-brand, and e-commerce demand |
| U.S. prescription generic | $150 million-$300 million | High volume, low price, payer substitution |
| International branded and generic | $600 million-$950 million | Greater brand retention in some markets |
| Hospital and institutional | $100 million-$200 million | Includes oral and injectable PPI purchasing |
| Total estimated market | $1.2 billion-$1.8 billion | Includes overlapping channel estimates |
These figures are analytical estimates rather than reported consolidated sales. Nexium prescription sales fell sharply after generic entry, while OTC Nexium retained consumer value through brand recognition and retail placement. AstraZeneca reported Nexium sales of more than $5 billion at its peak before patent expiry and generic erosion materially reduced the product’s contribution [1].
What are the sales projections for esomeprazole magnesium?
The most likely outlook is stable volume with lower revenue per unit. The product has broad clinical familiarity, but the PPI class is mature and faces substitution from omeprazole, lansoprazole, pantoprazole, rabeprazole, vonoprazan in selected markets, and nonprescription antacid products.
Global esomeprazole magnesium sales forecast
| Year | Bear case | Base case | Upside case |
|---|---|---|---|
| 2024 | $1.2B | $1.5B | $1.8B |
| 2025 | $1.1B | $1.5B | $1.8B |
| 2026 | $1.0B | $1.4B | $1.8B |
| 2027 | $0.9B | $1.4B | $1.8B |
| 2028 | $0.9B | $1.3B | $1.7B |
| 2029 | $0.8B | $1.3B | $1.7B |
| 2024-2029 CAGR | -7.7% | -2.9% | -1.1% |
The base case assumes:
- Prescription volume remains broadly stable.
- Generic price deflation continues at approximately 3% to 7% annually.
- OTC volume grows by 1% to 3% annually in nominally stable markets.
- Brand Nexium retains a smaller premium segment.
- No major new patent-protected delivery system captures a material share.
- Public reimbursement increasingly favors lower-cost PPI alternatives.
The upside case requires stronger OTC pricing, higher retail demand, successful premium formulations, or increased use in markets where esomeprazole has a brand advantage over generic omeprazole and pantoprazole. The bear case reflects aggressive generic substitution, reduced PPI utilization, and continued pharmacy reimbursement pressure.
When did esomeprazole lose exclusivity?
Esomeprazole lost practical U.S. prescription exclusivity in the mid-2010s. AstraZeneca’s principal composition and formulation patent protections expired or became commercially ineffective before the current market period, allowing generic manufacturers to enter.
The key commercial events were:
| Date | Event |
|---|---|
| 2001 | FDA approval of prescription Nexium delayed-release capsules |
| 2002 | FDA approval of Nexium delayed-release tablets |
| 2008 | FDA approval of injectable Nexium |
| 2014 | FDA approval of Nexium 24HR OTC delayed-release capsules |
| 2015 onward | Broad generic prescription competition developed |
| Current market | Generic, OTC, private-label, and institutional competition |
Exact exclusivity treatment depended on the product, dosage form, patent listing, pediatric extensions, and regulatory pathway. FDA regulatory exclusivity is distinct from patent protection. The FDA Orange Book identifies listed patents and exclusivity information for approved prescription products, but an expired patent does not prevent competition from other formulation or method-of-use products if separate enforceable rights remain [2].
What patents protect esomeprazole magnesium?
The original esomeprazole estate included patents directed to the optically pure S-isomer, salts, pharmaceutical compositions, delayed-release formulations, and therapeutic uses. Important historical U.S. patent families associated with omeprazole and esomeprazole included:
| Patent | Historical subject matter | Commercial relevance |
|---|---|---|
| U.S. Patent No. 5,714,504 | Optically pure omeprazole-related compounds and salts | Core stereochemical protection |
| U.S. Patent No. 6,369,085 | Pharmaceutical formulation technology | Delayed-release and product protection |
| U.S. Patent No. 6,875,872 | Esomeprazole-related formulation protection | Historical product lifecycle management |
Patent scope and enforceability varied by claim construction, terminal disclaimers, prosecution history, and jurisdiction. The central commercial barrier has expired. Current value is concentrated in manufacturing know-how, coating technology, regulatory approvals, supply reliability, trademarks, and retail distribution rather than in the original composition patent estate.
How strong is the current patent estate?
The current estate is weak for ordinary esomeprazole magnesium delayed-release capsules and tablets because the core product has long been genericized. Patent strength can still be meaningful for:
- New combinations with other gastrointestinal agents.
- Modified-release profiles.
- Pediatric granules and sprinkle formulations.
- Device-assisted delivery.
- Specific injectable presentations.
- Manufacturing processes that reduce impurities or improve yield.
- Narrow method-of-use claims.
These rights generally provide narrower protection than the original product patents. They are more exposed to design-around strategies and may not prevent generic entry into conventional 20 mg and 40 mg oral products.
What is the Orange Book status of esomeprazole magnesium?
Prescription Nexium products and approved generic equivalents have been subject to FDA Orange Book listing practices. The Orange Book identifies approved drug products, therapeutic-equivalence evaluations, patents submitted by reference-listed-drug sponsors, and applicable regulatory exclusivity [2].
For ordinary esomeprazole magnesium delayed-release capsules, the commercial market is consistent with an off-patent, therapeutically substitutable product category. Generic manufacturers typically seek approval under an abbreviated new drug application and demonstrate bioequivalence to the relevant reference product.
An Orange Book listing does not establish that every listed patent is valid or infringed. It records the sponsor’s patent certification and FDA’s regulatory listing. Litigation risk depends on the specific patent, asserted claims, ANDA filing date, paragraph IV notice, and court outcome.
Which companies compete with esomeprazole magnesium?
Competition comes from both esomeprazole manufacturers and other acid-suppression products.
Esomeprazole competitors
Major competitive groups include:
- AstraZeneca, through Nexium and related commercial rights.
- Viatris, Teva, Dr. Reddy’s, Sandoz, Hikma, Cipla, Sun Pharma, and other generic suppliers, depending on market.
- Private-label retailers and contract manufacturers supplying OTC esomeprazole.
- Hospital suppliers selling injectable or oral esomeprazole products.
Therapeutic competitors
| Product | Competitive position |
|---|---|
| Omeprazole | Often lower-cost; extensive generic availability |
| Pantoprazole | Strong institutional and prescription presence |
| Lansoprazole | OTC and generic competition |
| Rabeprazole | Smaller but established prescription segment |
| Vonoprazan | Newer potassium-competitive acid blocker in selected indications |
| Famotidine | H2-receptor antagonist alternative |
| Antacids and alginates | Short-duration symptom relief |
Esomeprazole maintains a commercial position through physician familiarity, perceived potency, consumer recognition, and OTC brand equity. Those advantages are weaker in formularies that prioritize acquisition cost.
What generic entry risks exist?
Generic entry risk is already realized for conventional prescription esomeprazole magnesium. The relevant business risk is further price compression and share migration rather than a first generic launch.
The highest-risk products are:
- Standard 20 mg and 40 mg delayed-release capsules.
- Standard delayed-release tablets with established bioequivalence pathways.
- Retail private-label OTC products.
- Institutional oral products where therapeutic substitution is routine.
Lower-risk areas include products with complex coating systems, pediatric granules, differentiated packaging, combination regimens, and sterile injectable manufacturing. These products face higher development, quality, and supply-chain requirements.
What manufacturing and formulation barriers remain?
Esomeprazole magnesium is chemically manageable but formulation-sensitive. Key barriers include:
- Maintaining chemical stability during processing.
- Protecting the active ingredient from gastric acid.
- Controlling enteric-coating performance.
- Matching dissolution profiles across pH conditions.
- Managing polymorphism, salt characteristics, and particle size.
- Demonstrating bioequivalence for delayed-release products.
- Controlling impurities and degradation products.
- Maintaining consistent supply of active pharmaceutical ingredient.
- Meeting FDA current good manufacturing practice requirements.
The manufacturing barrier is moderate for standard capsules and higher for sterile products, multiparticulate granules, and advanced modified-release systems. Because many suppliers have established processes, manufacturing alone is unlikely to support durable premium pricing without regulatory, quality, or supply advantages.
What litigation and Paragraph IV activity affect esomeprazole?
The principal litigation cycle occurred during the period when generic manufacturers challenged AstraZeneca’s patents covering Nexium. Paragraph IV certifications notified the sponsor that an ANDA applicant believed listed patents were invalid, unenforceable, or not infringed. These disputes shaped the timing of generic entry and settlements.
The litigation value of the original Nexium estate has declined because the relevant patents have expired or no longer block ordinary generic products. Current disputes, if any, are more likely to concern narrow formulations, manufacturing methods, labeling, or specific combination products than the basic esomeprazole magnesium molecule.
Settlement agreements in legacy pharmaceutical litigation can contain launch dates, licenses, supply provisions, or restrictions. The commercial significance of historical settlements is now limited for standard esomeprazole products because multiple generic and OTC suppliers have established market access.
How does esomeprazole compare with omeprazole and pantoprazole?
| Factor | Esomeprazole | Omeprazole | Pantoprazole |
|---|---|---|---|
| Core market status | Mature generic and OTC | Mature generic and OTC | Mature generic, strong institutional use |
| Brand strength | High through Nexium | High through Prilosec history | Moderate |
| Price pressure | High | Very high | High |
| Prescription differentiation | Limited | Limited | Formulary and hospital familiarity |
| OTC presence | Strong | Strong | More limited in some markets |
| Patent strength | Weak for standard products | Weak for standard products | Weak for standard products |
| Growth outlook | Flat to declining value | Flat to declining value | Stable institutional demand |
Esomeprazole can command a modest premium over omeprazole in some retail and physician segments, but that premium is vulnerable when payers or consumers compare active ingredients on a cost basis.
What is the FDA regulatory status?
FDA-approved esomeprazole products include prescription delayed-release capsules, delayed-release tablets, oral granules, and injectable products, as well as OTC delayed-release capsules marketed for frequent heartburn. OTC products are subject to labeling, dosing, self-selection, and consumer-use requirements that differ from prescription products.
Regulatory risk is concentrated in:
- Labeling compliance.
- Product quality and dissolution.
- Manufacturing inspection findings.
- OTC monograph or application requirements.
- Bioequivalence for complex delayed-release products.
- Supply interruptions or recalls.
No biosimilar pathway applies to esomeprazole magnesium because it is a chemically synthesized small molecule, not a biologic. The relevant approval pathways are abbreviated new drug applications, 505(b)(2) applications for certain differentiated products, and conventional applications for new formulations or combinations.
What is the commercial outlook and revenue exposure?
AstraZeneca’s historical Nexium revenue exposure was material, but current exposure is substantially lower because the product is no longer a primary patent-protected growth asset. Generic manufacturers face a different profile: low unit margins, large tender volumes, manufacturing scale, and potential supply volatility.
The most attractive commercial opportunities are:
- Private-label OTC supply.
- Reliable low-cost API and finished-dose manufacturing.
- Pediatric or multiparticulate formulations.
- Hospital injectable supply.
- Combination products with distinct regulatory value.
- Markets where branded esomeprazole retains physician or consumer preference.
The least attractive opportunity is an undifferentiated standard delayed-release capsule competing solely on price.
Key Takeaways
- Esomeprazole magnesium is a mature, off-patent small-molecule market.
- Nexium created a multibillion-dollar franchise before generic erosion.
- Current global market value is reasonably estimated at $1.2 billion to $1.8 billion.
- Base-case market value is projected to decline from approximately $1.5 billion in 2024 to $1.3 billion in 2029.
- Standard 20 mg and 40 mg products face intense generic and private-label competition.
- Patent protection is weak for conventional delayed-release products.
- Remaining IP value is concentrated in formulations, manufacturing processes, combinations, and selected delivery systems.
- OTC brand equity and retail distribution are more important than patent exclusivity.
- Esomeprazole has no biosimilar risk because it is a chemically synthesized small molecule.
- Differentiated formulations and reliable manufacturing offer the strongest commercial opportunities.
FAQs
Is esomeprazole magnesium still profitable for generic manufacturers?
Yes, but profitability depends on production scale, API costs, manufacturing reliability, and contract or institutional volume. Standard prescription products generally have limited pricing power.
Will esomeprazole magnesium sales grow through 2030?
Unit demand may remain stable or increase modestly, but total market value is more likely to decline because generic price erosion is expected to exceed volume growth.
Does Nexium still have patent protection?
The original patent protection that supported Nexium’s prescription exclusivity has expired or ceased to block standard generic entry. Narrower formulation or method patents may exist for specific products, but they do not recreate the original market barrier.
Can a company obtain FDA approval for a new esomeprazole formulation?
Yes. A differentiated formulation may proceed through an ANDA, 505(b)(2) application, or another appropriate FDA pathway, depending on the product’s relationship to an approved reference product and the nature of the claimed change.
What is the largest threat to esomeprazole magnesium revenue?
The largest threat is continued substitution by lower-cost generic PPIs, particularly omeprazole and pantoprazole, combined with pharmacy reimbursement pressure and consumer movement toward store-brand OTC products.
References
-
AstraZeneca PLC. (2001-2017). Annual reports and financial results. AstraZeneca.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book. FDA.
-
U.S. Food and Drug Administration. (2014). Nexium 24HR approval and labeling materials. FDA.
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. FDA.
-
U.S. Patent and Trademark Office. (1998). U.S. Patent No. 5,714,504: Optically pure salts of omeprazole. USPTO.
-
U.S. Patent and Trademark Office. (2002). U.S. Patent No. 6,369,085: Pharmaceutical formulations containing esomeprazole. USPTO.
-
U.S. Patent and Trademark Office. (2005). U.S. Patent No. 6,875,872: Esomeprazole pharmaceutical compositions. USPTO.
More… ↓
