Last updated: October 18, 2026
Risperidone is a mature antipsychotic with a two-tier market. Oral tablets, orally disintegrating tablets, and oral solution are largely genericized and price competitive. Long-acting injectable formulations retain commercial value through delivery technology, dosing convenience, and differentiated product positioning. The original Risperdal franchise generated multibillion-dollar revenue before U.S. generic entry, but current growth is concentrated in newer injectable products, including Uzedy, Rykindo, and Perseris.
What is the current risperidone market structure?
Risperidone is a second-generation antipsychotic approved for schizophrenia, bipolar mania or mixed episodes, and irritability associated with autistic disorder in pediatric patients, depending on the formulation and label.
| Product or form |
Sponsor or major supplier |
Route |
Market position |
| Risperdal |
Janssen, Johnson & Johnson |
Oral |
Original branded product; mature and largely genericized |
| Generic risperidone |
Multiple manufacturers |
Oral, solution, ODT |
Dominant U.S. volume segment |
| Risperdal Consta |
Janssen |
Intramuscular long-acting injection |
Established depot product |
| Perseris |
Indivior |
Subcutaneous long-acting injection |
Monthly schizophrenia treatment |
| Rykindo |
Luye Pharma |
Intramuscular long-acting injection |
U.S. monthly depot product |
| Uzedy |
Teva and MedinCell |
Subcutaneous long-acting injection |
Monthly or every-two-month treatment |
| Risperidone microsphere and other regional products |
Regional manufacturers |
Injectable |
Commercially important outside the U.S. |
The market divides into low-cost oral volume and higher-value long-acting injectable revenue. Oral risperidone competes primarily on price, formulary access, and manufacturing reliability. Injectable products compete on adherence, injection frequency, administration setting, tolerability, device or depot technology, and payer economics.
The principal clinical alternatives are aripiprazole, paliperidone, olanzapine, quetiapine, ziprasidone, and haloperidol. Paliperidone is the closest branded franchise comparator because it is the active metabolite of risperidone and is marketed in oral and long-acting injectable forms by Janssen as Invega and Invega Sustenna, Trinza, and Hafyera.
How has risperidone revenue changed over time?
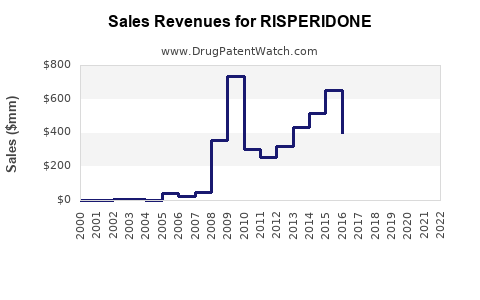
Risperidone revenue followed a classic small-molecule lifecycle: rapid growth after launch, peak sales before generic erosion, a sharp decline in oral revenue after loss of U.S. exclusivity, and partial value preservation through depot formulations.
Johnson & Johnson reported global Risperdal sales of approximately $4.1 billion in 2007. Sales declined to about $3.0 billion in 2008 and approximately $2.2 billion in 2009 as generic competition expanded in the United States and branded prescribing shifted toward competing antipsychotics [1][2]. The exact reporting treatment varied by year and may have included different formulation or regional groupings.
| Period |
Financial trajectory |
Main driver |
| 1990s |
Rapid adoption |
Broad schizophrenia and bipolar use; limited atypical-antipsychotic competition |
| Early to mid-2000s |
Peak commercial period |
Global branded pricing and expanding clinical use |
| 2008 onward |
Steep oral decline |
U.S. generic entry and price compression |
| 2010s |
Mature generic market |
Persistent prescription volume but limited brand pricing power |
| 2020s |
Injectable-led value recovery |
New depot products and expansion of long-acting treatment options |
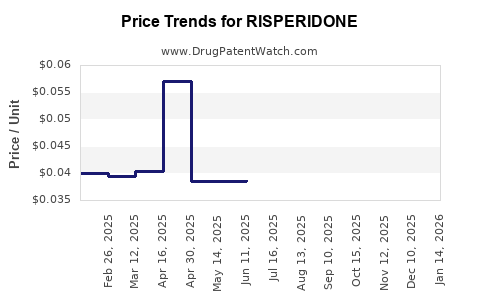
No single public source provides a standardized current global revenue figure for all risperidone products. Manufacturer disclosures report individual products, regional sales, or broader portfolios rather than a consolidated active-ingredient market total. The commercial trend is clear: oral risperidone is a high-volume, low-margin generic; long-acting injectable risperidone is the principal route to differentiated revenue.
When did risperidone lose exclusivity?
The core U.S. compound patent for risperidone, U.S. Patent No. 4,804,663, expired in 2008, subject to the effects of patent-term calculations, pediatric exclusivity, and jurisdiction-specific rules. FDA-approved generic risperidone products subsequently entered the market in tablets, oral solution, and orally disintegrating tablets [3][4].
The original oral franchise no longer has meaningful U.S. compound-level exclusivity. Remaining commercial protection depends on formulation, delivery technology, regulatory exclusivity, manufacturing complexity, and brand or device differentiation.
What is the Orange Book status of Risperdal and Risperdal Consta?
Risperdal oral products are not protected by a commercially significant active U.S. compound patent. FDA Orange Book records remain the controlling source for listed patents, exclusivity codes, and approval status for each dosage form and sponsor [3].
Risperdal Consta is materially different. Its microsphere depot technology, manufacturing process, dosing system, and formulation create a more complex competitive barrier than oral tablets. Patent expiration dates for injectable products must be assessed by product and patent family rather than inferred from the 2008 expiration of the core risperidone patent. Orange Book listings and FDA approval records should be reviewed separately for each dosage form and sponsor.
What formulations are protected by risperidone patents?
Risperidone formulation and delivery protection has historically focused on:
- Long-acting microsphere depots
- Extended-release injectable suspensions
- Subcutaneous delivery systems
- Polymer composition and drug-release kinetics
- Particle size, encapsulation, and manufacturing processes
- Stabilizers, excipients, and reconstitution systems
- Dosing intervals and administration protocols
Risperidone oral tablets and oral solutions are relatively easy for generic manufacturers to reproduce. Long-acting injectables require validated particle engineering, sterile manufacturing, release testing, injection-site tolerability data, and consistent pharmacokinetics. Those requirements increase the cost and time required for market entry even when core compound patents have expired.
Perseris uses a monthly subcutaneous delivery system. Rykindo uses a long-acting intramuscular depot approach. Uzedy uses MedinCell’s subcutaneous BEPO technology, which supports monthly and every-two-month dosing. These products compete through delivery and adherence attributes rather than new active ingredients [5][6][7].
What is the FDA regulatory status of risperidone products?
The FDA approved Risperdal in 1993. It later approved orally disintegrating and liquid formulations, followed by long-acting injectable products.
| FDA milestone |
Product |
Commercial implication |
| 1993 |
Risperdal oral formulation |
Established risperidone as a major atypical antipsychotic |
| 1997 |
Risperdal M-Tab |
Added orally disintegrating delivery |
| 2003 |
Risperdal Consta |
Created the first major long-acting risperidone franchise |
| 2018 |
Perseris |
Added monthly subcutaneous delivery |
| 2023 |
Rykindo |
Added a competing monthly injectable |
| 2023 |
Uzedy |
Added monthly and every-two-month subcutaneous dosing |
FDA approval of Rykindo and Uzedy materially changed the competitive landscape. The market shifted from a single established depot product toward multiple injectable platforms. That expands treatment choice but also increases payer negotiation and switching pressure.
Risperidone is a small molecule, so biosimilar approval is not applicable. Competitive risk comes from ANDA generics, complex generic or hybrid applications, 505(b)(2) products, and competing branded long-acting injectables.
Which companies are challenging the risperidone market?
The competitive field has four groups.
Generic oral manufacturers
Generic manufacturers compete in tablets, oral solution, and orally disintegrating tablets. These products have low development risk because the active ingredient is well characterized and clinical efficacy is established. Price erosion is strongest where several approved suppliers compete for pharmacy and wholesaler contracts.
Janssen and Johnson & Johnson
Janssen established the category with Risperdal and Risperdal Consta. Its broader paliperidone franchise remains commercially relevant because Invega long-acting products compete for many of the same schizophrenia patients and healthcare budgets.
Teva and MedinCell
Teva commercializes Uzedy under a partnership with MedinCell. The product’s subcutaneous route and flexible monthly or two-month dosing provide differentiation against older intramuscular depot products [5].
Luye Pharma
Luye Pharma commercializes Rykindo in the United States. The product gives Luye an entry into the U.S. long-acting antipsychotic market and provides an alternative to Janssen’s Consta and Teva’s Uzedy [6].
Indivior
Indivior commercializes Perseris, a monthly subcutaneous risperidone product. Its market position depends on access, prescriber familiarity, reimbursement, and the ability to demonstrate practical advantages over other depot products [7].
What generic entry risks exist for risperidone?
Oral risperidone
Oral generic entry is no longer a future risk. It is the established market condition. Key consequences include:
- Low average selling prices
- Multiple approved suppliers
- Limited brand retention
- Low switching costs for pharmacies
- Periodic supply risk if manufacturers exit
- Greater sensitivity to procurement contracts than clinical differentiation
The main commercial risk is not additional generic launch but further price compression and loss of manufacturing capacity.
Long-acting injectable risperidone
Injectable competition presents a different risk profile. A follow-on product must address formulation equivalence, release characteristics, injection-site performance, sterile manufacturing, and regulatory requirements. Market entry may occur through an ANDA, 505(b)(2) application, or a branded reformulation pathway, depending on the product and formulation.
A generic or follow-on Consta product would face meaningful technical barriers. Competing branded products can enter sooner by using a distinct delivery platform, as demonstrated by Perseris, Rykindo, and Uzedy.
What patent litigation and Paragraph IV risks affect risperidone?
Historical litigation focused on the original risperidone compound, oral formulations, and later depot products. Paragraph IV risk was most significant before the 2008 expiration of the core U.S. patent, when ANDA applicants could challenge listed patents and trigger the Hatch-Waxman litigation process.
For the oral market, the major patent dispute phase has passed. Current risk centers on:
- Patents listed for long-acting injectable formulations
- Patent term and pediatric exclusivity calculations
- Orange Book listing strategy
- Patent litigation against complex generic applicants
- Regulatory exclusivity for newer injectable products
- Manufacturing and process patents that may not block approval but can increase litigation exposure
Settlement agreements historically affected the timing of generic risperidone entry. The commercial value of additional oral settlements is now limited because the market is mature. Injectable settlements could have greater economic impact if they delay a first follow-on depot product, but public deal terms and launch dates must be evaluated product by product.
How strong is the risperidone patent estate?
The patent estate is weak for the original oral product and stronger for newer depot technologies.
| Segment |
Patent strength |
Main protection |
| Oral risperidone |
Low |
Core compound exclusivity expired; generic competition established |
| Oral solution and ODT |
Low to moderate |
Formulation and dosage-form claims, where active |
| Risperdal Consta |
Moderate |
Microsphere formulation, manufacturing, and depot delivery |
| Perseris |
Moderate |
Subcutaneous depot technology and formulation claims |
| Rykindo |
Moderate |
Depot formulation and manufacturing technology |
| Uzedy |
Moderate to strong relative to oral products |
Subcutaneous BEPO delivery platform and product-specific claims |
Patent strength does not equal launch protection. Injectable products may retain practical barriers after patent expiration because a competitor still needs specialized sterile manufacturing, clinical or bioequivalence support, supply scale, and payer access.
What licensing deals shape the risperidone market?
The most commercially important current collaboration is the Teva-MedinCell relationship for Uzedy. MedinCell supplies the BEPO delivery technology, while Teva contributes development, regulatory, manufacturing, and commercial infrastructure [5].
Luye’s Rykindo program reflects the use of proprietary depot technology to expand a regional pharmaceutical company into the U.S. market [6]. Perseris was developed and commercialized through Indivior’s specialty-pharmaceutical platform [7].
These arrangements show the market’s strategic shift. Value is moving from ownership of risperidone itself to control of delivery technology, regulatory execution, injection manufacturing, and payer distribution.
What is the geographic coverage of risperidone products?
Risperidone oral products are broadly available across North America, Europe, Asia, and other regulated and emerging markets. Generic supply is highly fragmented by jurisdiction.
Long-acting injectable availability is less uniform. Risperdal Consta has historically had the broadest international presence. Perseris, Rykindo, and Uzedy are more concentrated in the United States or selected markets. Product labels, approved dosing intervals, patent status, and reimbursement differ by country.
Geographic commercial expansion depends on local regulatory classification, depot manufacturing capacity, hospital and clinic procurement, and national reimbursement policy. U.S. launch economics are more attractive because branded injectable reimbursement can support higher prices than mature oral generic markets.
What is the outlook for risperidone revenue?
The oral market should remain stable in prescription volume but structurally weak in pricing. Revenue growth is unlikely without supply disruptions, a new formulation, or a major change in treatment guidelines.
Long-acting injectable revenue has the stronger outlook. Growth drivers include:
- Persistent adherence problems in schizophrenia
- Greater use of maintenance injections
- Monthly and every-two-month dosing
- Clinic-based administration
- Reduced reliance on daily oral adherence
- Product differentiation through subcutaneous delivery
- Expansion of specialty-pharmacy and behavioral-health services
Constraints include injection-site reactions, patient acceptance, prior authorization, administration costs, competition from paliperidone and aripiprazole LAIs, and payer preference for lower-cost generic oral therapy.
The financial trajectory is therefore bifurcated: mature generic oral risperidone produces durable volume with limited margin, while newer injectable products offer higher revenue per patient but face substantial commercial competition and launch costs.
Key Takeaways
- Risperidone oral exclusivity ended with expiration of the core U.S. patent in 2008.
- Generic tablets, oral solution, and ODT products dominate oral volume.
- Janssen’s historical Risperdal franchise exceeded $4 billion in annual sales before generic erosion.
- Long-acting injectables are the principal source of differentiated current value.
- Risperdal Consta, Perseris, Rykindo, and Uzedy compete through depot and delivery technology.
- Risperidone has no biosimilar risk because it is a small molecule.
- Current patent risk is concentrated in injectable formulations, manufacturing, and delivery platforms.
- Teva-MedinCell’s Uzedy has increased competitive pressure through monthly and every-two-month dosing.
- Oral revenue should remain low-margin and mature; injectable revenue has the better growth profile.
- Generic entry risk is largely exhausted for oral products but remains relevant for complex long-acting formulations.
FAQs
Is risperidone still a profitable pharmaceutical product?
Oral risperidone is generally a low-margin generic product. Profitability is higher for branded long-acting injectables because they command higher prices and require specialized manufacturing.
Does risperidone have biosimilar competition?
No. Risperidone is a chemically synthesized small molecule. Its competitors are generics, complex generics, 505(b)(2) products, and alternative branded injectables.
Which risperidone product has the strongest commercial differentiation?
Uzedy has strong delivery differentiation through subcutaneous administration and monthly or every-two-month dosing. Rykindo and Perseris also differentiate through depot technology, while Consta benefits from long market experience and established clinical use.
Can a generic company launch a copy of Risperdal Consta?
A company would need to address formulation equivalence, release kinetics, sterile manufacturing, regulatory pathway, and any remaining patent claims. A simple oral-style ANDA strategy is unlikely to remove all practical barriers.
What drugs compete most directly with long-acting risperidone?
The closest competitors are paliperidone palmitate products, including Invega Sustenna, Invega Trinza, and Invega Hafyera, along with aripiprazole long-acting injectables such as Abilify Maintena and Aristada.
References
-
Johnson & Johnson. (2008). 2007 annual report. Johnson & Johnson.
-
Johnson & Johnson. (2010). 2009 annual report. Johnson & Johnson.
-
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: Risperdal and risperidone product records. FDA.
-
Teva Pharmaceutical Industries Ltd. (2023). FDA approves UZEDY (risperidone) extended-release injectable suspension for the treatment of schizophrenia in adults. Teva.
-
Luye Pharma Group Ltd. (2023). FDA approves Rykindo for the treatment of schizophrenia and bipolar disorder. Luye Pharma.
-
Indivior PLC. (2018). FDA approves PERSERIS, the first and only once-monthly risperidone injection for the treatment of schizophrenia in adults. Indivior.