Last updated: August 18, 2026
Carbamazepine is a mature, low-cost anticonvulsant with broad generic availability, limited remaining intellectual-property protection, and stable demand from chronic epilepsy treatment. Its commercial value has shifted from branded product sales to high-volume generic supply, extended-release formulations, pediatric products, and pharmaceutical-grade active ingredient manufacturing. Standalone global revenue is not publicly disclosed by most manufacturers, so the financial trajectory is best assessed through market structure, prescription demand, pricing, and competitive substitution rather than branded sales growth.
What is carbamazepine used for, and how large is the addressable market?
Carbamazepine is an oral sodium-channel blocker used primarily for epilepsy and trigeminal neuralgia. U.S. labeling covers partial seizures, generalized tonic-clonic seizures, mixed seizure patterns, and trigeminal neuralgia. Some products and jurisdictions also recognize bipolar disorder-related manic or mixed episodes. [1]
The addressable market has three main components:
| Market segment |
Commercial characteristics |
| Epilepsy |
Chronic treatment, recurring prescriptions, high generic penetration |
| Trigeminal neuralgia |
Smaller patient population, long treatment duration |
| Bipolar disorder and other off-label uses |
Limited commercial differentiation and substantial competition |
Carbamazepine remains clinically relevant because it is effective, inexpensive, and available in multiple oral dosage forms. Its use has declined in some treatment algorithms because of drug interactions, enzyme induction, hyponatremia risk, hematologic toxicity, and the availability of newer antiseizure medicines.
The epilepsy market itself continues to grow with population, diagnosis, and treatment access. Carbamazepine has not captured most of that growth because newer agents such as levetiracetam, lamotrigine, and oxcarbazepine have taken share in many prescribing settings. Its demand is more closely tied to the installed base of chronic users and price-sensitive health systems.
How has the carbamazepine market evolved?
Carbamazepine was developed by Geigy and commercialized under the Tegretol brand. The U.S. Food and Drug Administration approved Tegretol in 1968. [2] The product moved through the normal pharmaceutical life cycle:
- Branded launch and neurologist adoption.
- Expansion into additional seizure types and neuralgia.
- Introduction of chewable, suspension, and extended-release products.
- Generic substitution following loss of market exclusivity.
- Long-term commoditization with multiple manufacturers.
The original branded value proposition was clinical familiarity and formulation reliability. That advantage weakened after generic immediate-release and extended-release products became widely available.
Today, carbamazepine competes primarily on:
- Wholesale acquisition cost and reimbursement status.
- Product availability.
- Manufacturing consistency.
- Extended-release performance.
- Pediatric and liquid formulation access.
- Pharmacy supply reliability.
- Regulatory compliance and pharmacovigilance.
The market is therefore less sensitive to conventional brand promotion than it was during the Tegretol growth period.
What formulations are protected by carbamazepine patents?
Carbamazepine is available in immediate-release tablets, chewable tablets, oral suspension, extended-release tablets, and extended-release capsules. Tegretol-XR and other modified-release products were designed to reduce peak-to-trough concentration changes and simplify dosing. [1,3]
| Formulation |
Commercial role |
Competitive position |
| Immediate-release tablet |
Core low-cost product |
Highly commoditized |
| Chewable tablet |
Pediatric and swallowing-challenged patients |
Smaller volume, differentiated by usability |
| Oral suspension |
Pediatric and dose-flexibility segment |
Supply and formulation consistency matter |
| Extended-release tablet |
Reduced dosing frequency and smoother exposure |
More defensible than immediate release but largely generic |
| Extended-release capsule |
Alternative modified-release presentation |
Generic competition in selected markets |
The principal formulation opportunity is not broad patent exclusivity. It is regulatory execution and reliable bioequivalence. Modified-release carbamazepine products can require more complex formulation development than standard tablets because release characteristics affect plasma concentration, seizure control, and tolerability.
Historical patents covering Tegretol and modified-release delivery systems expired many years ago. Current commercial products generally do not rely on a live, high-value composition-of-matter patent. The practical barriers are formulation know-how, manufacturing validation, bioequivalence studies, and regulatory approval.
When did carbamazepine lose exclusivity?
Carbamazepine lost meaningful branded exclusivity decades ago. The active ingredient is now available from numerous generic manufacturers in the United States and internationally.
| Exclusivity category |
Current position |
| Composition-of-matter protection |
Expired |
| Original Tegretol product exclusivity |
Expired |
| Immediate-release generic entry |
Established for decades |
| Extended-release formulation protection |
Historical protections have expired or no longer create a broad market barrier |
| Pediatric exclusivity |
No current commercial significance |
| Orphan exclusivity |
Not a current basis for market protection |
| Biologic exclusivity |
Not applicable |
The FDA Orange Book lists approved drug products and patent information for eligible products. Carbamazepine products do not have a current exclusivity profile comparable with recently launched small-molecule medicines. [4]
What is the Orange Book status of carbamazepine?
Carbamazepine is an approved small-molecule drug with multiple abbreviated new drug application products. Tegretol and Tegretol-XR established the reference-product framework for generic competition. FDA-approved products include several dosage forms and strengths, although availability varies by manufacturer and time. [4,5]
The commercial significance of Orange Book listings is limited because:
- The foundational patents are expired.
- Generic versions have been approved for many years.
- No active patent estate appears to block broad generic substitution.
- Any current listed patents would generally relate to a specific product or formulation rather than carbamazepine itself.
Orange Book status should be reviewed at the product and dosage-form level because approval histories and listed patents can differ among immediate-release, suspension, and extended-release products.
Are there Paragraph IV challenges to carbamazepine?
Paragraph IV litigation is not a current central market issue for standard carbamazepine products. Paragraph IV certifications typically matter when an ANDA applicant seeks approval before expiration of an Orange Book-listed patent. Carbamazepine’s principal patents expired long ago, and generic competition is already established.
Historical patent disputes could have affected specific modified-release products, but they do not create a current market-wide barrier to generic carbamazepine. The key competitive question is therefore not whether a first generic entrant can launch, but whether a manufacturer can maintain supply, pass FDA inspections, and compete at sustainable margins.
Which companies manufacture or compete with carbamazepine?
Carbamazepine is produced by a fragmented group of branded, generic, and contract manufacturers. Product availability changes by jurisdiction and distributor. U.S. market participants have included Teva, Apotex, Amneal, Rising Pharmaceuticals, NorthStar Rx, and other generic suppliers, while Novartis historically commercialized Tegretol in several markets. Manufacturer portfolios and National Drug Code status can change over time. [5]
The competitive landscape includes both direct and therapeutic competitors.
Direct generic competitors
Direct competition includes manufacturers selling:
- Carbamazepine tablets.
- Carbamazepine chewable tablets.
- Carbamazepine oral suspension.
- Carbamazepine extended-release tablets or capsules.
Direct generic products are differentiated by strength availability, supply continuity, packaging, pharmacy contracting, and formulation performance rather than by active-ingredient exclusivity.
Therapeutic competitors
| Competitor |
Competitive effect |
| Oxcarbazepine |
Closely related mechanism with fewer metabolic interactions in some settings |
| Levetiracetam |
Strong use in newer epilepsy treatment pathways; limited drug interactions |
| Lamotrigine |
Broad epilepsy use and bipolar disorder relevance |
| Valproate |
Broad antiseizure activity but important reproductive and safety restrictions |
| Phenytoin |
Older low-cost alternative with complex pharmacokinetics |
| Gabapentin and pregabalin |
Relevant for selected neuropathic pain and seizure indications |
| Lacosamide |
Newer focal-seizure therapy with higher pricing than carbamazepine |
Carbamazepine’s strongest defenses are low cost, clinical familiarity, and availability. Its main weaknesses are interaction burden and monitoring requirements.
How strong is the carbamazepine patent estate?
The patent estate is weak as a current exclusivity platform and moderate as a technical barrier for selected formulations.
Patent strength by category
| Patent category |
Current strength |
| Active ingredient |
Negligible; long expired |
| Conventional tablets |
Negligible to low |
| Oral suspension |
Low; formulation execution remains relevant |
| Extended-release delivery |
Low to moderate technical complexity, but no broad originator exclusivity |
| Manufacturing process |
Potentially relevant for a specific supplier, not a market-wide barrier |
| Method of use |
Limited commercial value because core indications are long established |
Method-of-use patents are not a major driver of current carbamazepine economics. The core epilepsy and trigeminal-neuralgia uses have been known for decades. Any later use patent would face narrow scope, invalidity risk, and generic substitution considerations.
Manufacturing intellectual property can still influence product quality. Carbamazepine has limited aqueous solubility, and modified-release products require control of particle size, excipient selection, granulation, coating, and dissolution. Those factors can affect bioequivalence and batch-to-batch performance even after patent expiration.
What FDA regulatory risks affect carbamazepine?
The main regulatory risks concern safety, consistency, and supply rather than approval of the active ingredient.
U.S. labeling carries a boxed warning for serious dermatologic reactions and aplastic anemia or agranulocytosis. Screening for HLA-B*15:02 is relevant for patients with ancestry associated with increased risk of Stevens-Johnson syndrome and toxic epidermal necrolysis. Carbamazepine also has clinically important interactions because it induces CYP3A4 and other metabolic pathways. [1]
Regulatory and commercial risks include:
- FDA manufacturing observations or warning letters.
- Product recalls caused by dissolution or contamination issues.
- Shortages caused by limited API suppliers.
- Inconsistent supply of suspension and chewable products.
- Labeling updates related to pharmacogenomics or adverse events.
- Bioequivalence problems in modified-release products.
Because the molecule is mature, a manufacturer’s value depends heavily on quality systems and supply reliability. A regulatory action against a major supplier can produce temporary pricing power for remaining manufacturers, but that benefit can disappear when alternative capacity returns.
Is biosimilar risk relevant to carbamazepine?
No. Carbamazepine is a synthetic small molecule, not a biologic. Biosimilar competition does not apply. The relevant competitive pathway is the ANDA generic pathway in the United States and equivalent generic-drug pathways in other jurisdictions.
This distinction matters commercially. Carbamazepine does not have biologic manufacturing complexity or biosimilar interchangeability disputes. It has conventional generic substitution risk, with pricing pressure determined by the number of approved suppliers and pharmacy or health-system contracting.
What is the financial trajectory for carbamazepine?
Carbamazepine has a mature, low-growth financial profile. Its financial trajectory can be summarized as follows:
| Period |
Financial profile |
| Branded growth era |
Higher margins, expanding indications, originator-led pricing |
| Early generic entry |
Rapid price erosion and share transfer to generics |
| Mature generic era |
Stable unit demand, low prices, fragmented supplier margins |
| Current outlook |
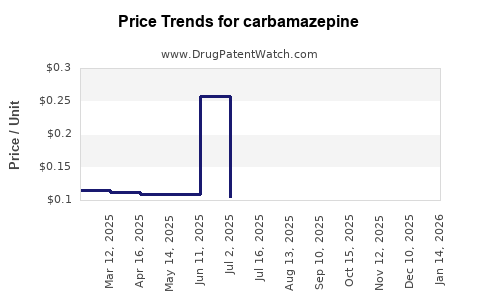
Low nominal growth, episodic pricing volatility, limited innovation premium |
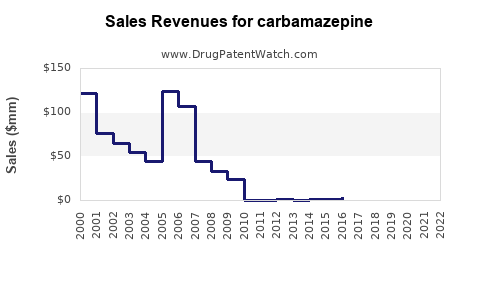
No major manufacturer typically reports carbamazepine as a standalone revenue line. Public company filings generally aggregate it within broader generic pharmaceuticals, central nervous system products, or established brands. As a result, company-level revenue exposure is better measured through product portfolios, manufacturing capacity, and supply contracts than through disclosed carbamazepine sales.
Revenue drivers
Revenue is supported by:
- Chronic epilepsy treatment.
- Continued use in low-income and middle-income markets.
- Trigeminal neuralgia demand.
- Pediatric formulations.
- Extended-release products.
- Temporary shortages affecting competing suppliers.
- Institutional and government procurement.
Revenue constraints
Revenue is limited by:
- Generic price competition.
- Therapeutic substitution by newer antiseizure medicines.
- Reduced branded promotion.
- Low switching costs for pharmacies and payers.
- Limited patent protection.
- Clinical concerns about interactions and adverse effects.
The base-case trajectory is stable to declining in nominal value per prescription, with unit volumes relatively resilient. A manufacturer with efficient production can remain profitable, but the product is unlikely to generate high pharmaceutical-style returns without a differentiated delivery system, regional supply advantage, or bundled portfolio strategy.
What generic entry risks exist for carbamazepine?
Generic entry risk is already realized rather than prospective. The principal risk to an originator is continued erosion of branded volume and price. The principal risk to a generic manufacturer is margin compression and supply competition.
Generic manufacturers face four practical risks:
- Approval and bioequivalence failure for extended-release products.
- API supply disruption.
- FDA inspection or quality-system failure.
- Price collapse after additional suppliers enter.
For buyers and licensees, the most attractive assets are not basic immediate-release tablets. They are reliable extended-release products, pediatric presentations, shortage-prone dosage forms, and products with established distribution in markets where supply is constrained.
How does carbamazepine compare with newer antiseizure drugs?
Carbamazepine has a cost advantage but a weaker convenience and interaction profile.
| Factor |
Carbamazepine |
Newer antiseizure medicines |
| Price |
Very low in generic markets |
Often higher, especially before generic entry |
| Drug interactions |
Substantial enzyme induction |
Often lower with levetiracetam and selected newer agents |
| Monitoring |
More complex in some patients |
Generally simpler for several newer products |
| Clinical familiarity |
Extensive |
Strong and expanding |
| Patent protection |
Expired |
Varies by product |
| Formulation innovation |
Limited |
More active in selected products |
| Switching pressure |
High in newly diagnosed patients |
Lower for established carbamazepine responders |
Carbamazepine remains difficult to displace in patients who are stable, tolerate it, and obtain it at low cost. It is more vulnerable in new starts, polypharmacy, elderly patients, and patients requiring therapies with fewer interactions.
What licensing and partnership opportunities exist?
Licensing activity is more likely to involve regional commercialization, contract manufacturing, or differentiated formulations than ownership of the carbamazepine molecule.
Potential deal structures include:
- Regional rights for generic carbamazepine products.
- Contract manufacturing and supply agreements.
- Technology transfer for extended-release formulations.
- API supply contracts.
- Hospital and government procurement partnerships.
- Portfolio transactions involving multiple mature CNS products.
Large upfront payments are unlikely for conventional carbamazepine. Deal value would depend on manufacturing cost, regulatory approvals, geographic rights, guaranteed volumes, and supply continuity. A formulation with improved release characteristics or reduced dosing frequency could command more interest, but its economic value would still face generic substitution unless supported by regulatory or contractual differentiation.
What geographic markets offer the strongest commercial prospects?
The United States is a large, highly competitive generic market with low unit pricing and strict regulatory expectations. Europe is similarly mature, with national reimbursement systems and substantial generic substitution. Emerging markets can offer stronger volume growth but face price controls, local manufacturing requirements, tender competition, and uneven regulatory enforcement.
| Geography |
Commercial outlook |
| United States |
High generic penetration; low pricing; supply-driven opportunities |
| Western Europe |
Mature demand; reimbursement pressure; stable chronic use |
| Central and Eastern Europe |
Generic demand with variable pricing and procurement dynamics |
| India |
Significant manufacturing and API base; intense price competition |
| Latin America |
Branded-generic opportunity; country-specific regulatory barriers |
| Southeast Asia |
Growing access; distributor and registration complexity |
| Africa |
Low-cost demand; procurement and supply reliability are decisive |
The strongest opportunity is generally not premium pricing. It is dependable supply at competitive cost in markets where established suppliers have limited capacity.
Key Takeaways
- Carbamazepine is a mature generic anticonvulsant with no meaningful composition-of-matter exclusivity.
- Tegretol launched in the United States in 1968, and its core commercial protections expired decades ago.
- The current market is driven by generic volume, manufacturing efficiency, formulation reliability, and supply continuity.
- Extended-release, chewable, and suspension products have more technical complexity than standard tablets but limited current patent strength.
- Paragraph IV litigation and Orange Book exclusivity are not major current barriers to generic entry.
- Biosimilar risk is irrelevant because carbamazepine is a small molecule.
- Revenue is likely stable to declining in nominal terms, while unit demand remains resilient among chronic users.
- Newer antiseizure medicines create prescribing pressure, especially in newly diagnosed patients and those taking multiple medications.
- The most credible commercial opportunities involve regional distribution, API supply, contract manufacturing, and differentiated modified-release products.
- Public-company financial exposure is rarely disclosed on a carbamazepine-specific basis.
FAQs
Is carbamazepine still commercially important despite being generic?
Yes. It remains clinically important because of low cost, broad availability, and long-term use in epilepsy and trigeminal neuralgia. Its commercial importance is based on volume rather than pricing power.
Can a company obtain new patent protection for a carbamazepine product?
A company may pursue patents on a novel formulation, manufacturing process, delivery system, or specific use. Such patents would not restore exclusivity for the carbamazepine molecule itself and would need to satisfy novelty, non-obviousness, and enablement requirements.
Which carbamazepine formulation has the greatest commercial defensibility?
Extended-release products generally have greater technical defensibility than immediate-release tablets. Their value depends on reliable dissolution performance, approved bioequivalence, manufacturing scale, and consistent supply.
Does carbamazepine face shortage risk?
Yes. Mature generic products can experience shortages when a small number of suppliers provide a large share of API or finished-dose capacity. Suspension, chewable, and extended-release presentations can be more exposed than standard tablets.
Is carbamazepine a growth product for pharmaceutical investors?
It is generally a defensive mature-product asset rather than a growth product. Investment value depends on manufacturing efficiency, portfolio synergies, geographic access, and supply reliability rather than patent-driven pricing expansion.
References
- U.S. Food and Drug Administration. (2023). Tegretol and Tegretol-XR prescribing information. Novartis Pharmaceuticals Corporation.
- U.S. Food and Drug Administration. (n.d.). Drugs@FDA: FDA-approved drugs, Tegretol application history.
- National Library of Medicine. (2024). DailyMed: Carbamazepine drug labels. U.S. National Library of Medicine.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (2024). Drugs@FDA and National Drug Code Directory records for carbamazepine products.