Last updated: August 21, 2026
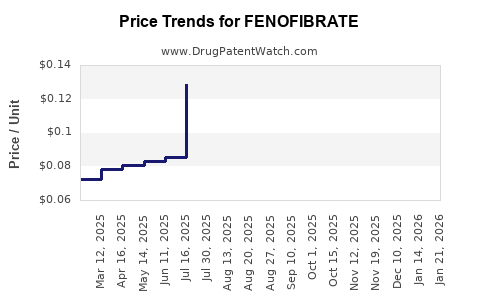
Fenofibrate is a mature, largely generic lipid-lowering drug with durable prescription demand but limited pricing power. Its commercial peak came from branded Tricor and related products before generic entry in the United States. Revenue has since shifted from originator brands to low-cost generic manufacturers, while demand remains tied to hypertriglyceridemia, mixed dyslipidemia, metabolic syndrome, and diabetes care.
Fenofibrate has no meaningful remaining U.S. composition-of-matter exclusivity. Commercial value now depends on manufacturing scale, formulary access, dosage-form differentiation, combination products, and distribution rather than patent protection.
What is the current market position of fenofibrate?
Fenofibrate is a generic fibrate marketed in multiple oral dosage forms, including tablets, capsules, micronized formulations, and delayed-release fenofibric acid products. It is used primarily to reduce triglycerides and improve lipid parameters in patients with hypertriglyceridemia or mixed dyslipidemia.
| Market factor |
Current position |
| Active ingredient |
Fenofibrate |
| Drug class |
Fibric acid derivative |
| Primary uses |
Severe hypertriglyceridemia, mixed dyslipidemia, hypercholesterolemia |
| Major historical brand |
Tricor |
| Related branded product |
Trilipix, fenofibric acid delayed-release |
| U.S. regulatory pathway |
NDA originator products; multiple ANDA generics |
| Biosimilar exposure |
None; fenofibrate is a small molecule |
| U.S. patent position |
Core patents expired |
| Pricing power |
Low for standard generic products |
| Main commercial drivers |
Prescription volume, payer coverage, manufacturing cost, dosage-form substitution |
| Main competitors |
Statins, gemfibrozil, omega-3 products, icosapent ethyl, newer lipid therapies |
Fenofibrate remains clinically relevant despite the loss of brand exclusivity. Statins are preferred for low-density lipoprotein cholesterol reduction and atherosclerotic cardiovascular disease risk management, while fenofibrate is more relevant when triglycerides are elevated or when mixed lipid abnormalities persist.
The drug’s clinical positioning is narrower than its historical commercial positioning. The ACCORD Lipid trial did not show a statistically significant reduction in major cardiovascular events for fenofibrate added to simvastatin in the overall study population, although a subgroup with high triglycerides and low HDL cholesterol showed a possible benefit signal. The FDA label does not position fenofibrate as a universal cardiovascular-risk-reduction product.[1][2]
How did fenofibrate generate its historical revenue?
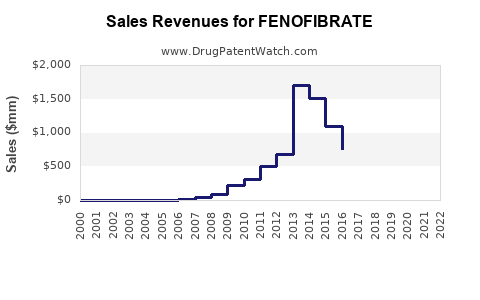
The commercial history of fenofibrate is closely linked to Abbott Laboratories’ Tricor franchise and Abbott’s 2006 acquisition of Kos Pharmaceuticals for approximately $3.7 billion. The acquisition gave Abbott control of Tricor, which was one of the leading branded lipid products in the United States at the time.[3]
Tricor benefited from multiple formulation and dosing iterations. Abbott moved the product from earlier micronized formulations to newer strengths and formulations designed to improve administration and reduce dependence on food intake. These changes supported product switching and delayed full erosion of the franchise.
Fenofibrate financial timeline
| Period |
Commercial development |
Financial implication |
| Before 2006 |
Tricor established as a major branded fibrate |
High branded pricing and strong cash generation |
| 2006 |
Abbott acquired Kos Pharmaceuticals |
Abbott obtained Tricor and related commercial assets |
| 2007-2011 |
Tricor remained a major Abbott product |
Annual sales were reported at roughly the billion-dollar scale during peak years |
| 2011-2013 |
Generic litigation and market entry accelerated |
U.S. brand revenue began falling sharply |
| After 2013 |
AbbVie inherited the product portfolio after separation from Abbott |
Tricor and related products entered a mature, declining brand phase |
| 2015 onward |
Generic substitution became dominant |
Value moved to generic volume and low-cost supply |
| Current market |
Multiple generic manufacturers compete |
No single company has durable control of the category |
Abbott’s annual reports identified Tricor as a significant pharmaceutical product during the late 2000s and early 2010s. The product’s revenue trajectory demonstrates the standard small-molecule lifecycle: rapid growth from clinical adoption, extension through formulation changes, then steep erosion after generic competition.[4]
Branded revenue is no longer the primary economic measure for fenofibrate. The relevant metrics are total prescriptions, generic utilization, average selling price, channel concentration, and the extent to which physicians use fenofibrate instead of competing triglyceride therapies.
When did fenofibrate lose exclusivity and patent protection?
Fenofibrate lost effective U.S. market exclusivity through a combination of patent expiration, generic litigation, and FDA approval of competing formulations. The core active ingredient is an old small molecule, and no current U.S. patent protects fenofibrate itself.
Tricor’s commercial protection relied on formulation, dosage, particle-size, bioavailability, and method-related patents rather than a new chemical entity patent with a long remaining term. Several patents were litigated against generic applicants, but those patents did not preserve long-term market exclusivity after the generic launch wave.
What patents protected Tricor and related fenofibrate products?
Historically, patent protection covered areas such as:
- Micronized fenofibrate particles.
- Pharmaceutical compositions containing fenofibrate.
- Tablet and capsule formulations.
- Food-effect and bioavailability characteristics.
- Dosing regimens and treatment methods.
- Delayed-release fenofibric acid formulations for Trilipix.
The most commercially important protection was formulation-based. Such patents can delay entry, but they are more vulnerable than a valid composition-of-matter patent because generic applicants can challenge validity, infringement, claim construction, or design-around options.
The Orange Book listed patents for Tricor and Trilipix during the relevant exclusivity period. Current commercial competition is primarily generic and is no longer constrained by a blocking patent estate of comparable value.[5]
What is the Orange Book status of fenofibrate?
The FDA Orange Book historically listed Tricor and Trilipix patents and regulatory exclusivities. Those listings were relevant to Paragraph IV certifications filed by generic applicants. Today, the practical Orange Book position is that fenofibrate products have no meaningful remaining brand barrier preventing ANDA competition.
| Product |
Regulatory status |
Commercial status |
| Tricor |
FDA-approved branded fenofibrate product |
Mature brand with extensive generic substitution |
| Trilipix |
FDA-approved fenofibric acid delayed-release product |
Limited branded relevance; generic competition |
| Generic fenofibrate tablets/capsules |
Multiple ANDA approvals |
Dominant U.S. supply channel |
| Fenofibrate micronized products |
Multiple approved dosage forms |
Compete on price and formulary position |
| Fenofibrate combination products |
Limited and product-specific |
Niche opportunity rather than broad exclusivity |
The precise list of active Orange Book patents can change as FDA listings are updated. The commercial conclusion is stable: no listed patent currently creates a broad, durable barrier to routine generic fenofibrate competition.
Which companies challenged fenofibrate patents?
Generic manufacturers challenged Tricor-related patents during the period when Abbott and later AbbVie sought to maintain branded market share. Publicly reported litigation involved major generic companies, including Teva, Mylan, Impax and other ANDA applicants, depending on the specific formulation and patent set.
The litigation strategy centered on Paragraph IV certifications. Generic applicants typically argued that asserted formulation or method patents were invalid, unenforceable, or not infringed. The brand company sought the statutory 30-month stay associated with qualifying patent litigation, while generic companies pursued approval and launch rights.
The key commercial effect was to compress the period during which Tricor could retain premium pricing. Once multiple generic suppliers entered, substitution increased and the branded product lost negotiating leverage with pharmacy benefit managers.
What is the FDA regulatory status of fenofibrate?
Fenofibrate is FDA-approved as an adjunct to diet for several lipid disorders. The label includes treatment of severe hypertriglyceridemia, primary hypercholesterolemia or mixed dyslipidemia, and selected lipid abnormalities associated with metabolic disease.[1]
Important regulatory considerations include:
- Fenofibrate is not a biologic and has no biosimilar pathway.
- Generic versions are approved through ANDAs.
- Bioequivalence may depend on formulation, particle size, dosage strength, and food-effect characteristics.
- Renal function affects dosing and safety.
- The drug carries warnings relating to myopathy, gallbladder disease, liver function, renal impairment, and interactions with anticoagulants and statins.
- Products and strengths are not automatically interchangeable across every formulation.
The FDA-approved label has also influenced commercial segmentation. Standard fenofibrate products compete primarily as generics, while more specialized formulations can obtain temporary differentiation through formulation design, dosing convenience, or improved administration requirements.
How strong is the fenofibrate patent estate?
The current patent estate is weak from an originator-protection perspective and moderate from a product-development perspective.
| Patent category |
Current strength |
Commercial relevance |
| Active ingredient |
Very weak; historic patents expired |
No meaningful exclusion |
| Basic oral dosage form |
Weak |
Generic substitution is established |
| Micronized formulation |
Limited |
May support formulation-specific regulatory distinctions |
| Delayed-release fenofibric acid |
Limited to product-specific claims |
Historical relevance for Trilipix |
| Combination products |
Variable |
Depends on new claims and active ingredients |
| Manufacturing process |
Potentially moderate |
Can raise supply-chain costs but rarely blocks market entry |
| New method of use |
Potentially moderate |
Requires clinically and legally defensible differentiation |
A new fenofibrate patent would need to address a commercially important problem, such as improved absorption, reduced food dependence, fixed-dose combination delivery, adherence, or a clinically validated treatment population. A routine reformulation would face weak pricing support unless it produced a material regulatory or clinical advantage.
What formulations are protected or commercially differentiated?
Fenofibrate’s formulation history is central to its market dynamics. The drug has low aqueous solubility, making particle size and formulation performance important for absorption.
Commercially relevant formulation categories include:
- Micronized fenofibrate tablets or capsules.
- Non-micronized or alternative particle-size formulations.
- Tablets designed for reduced dependence on food intake.
- Delayed-release fenofibric acid products.
- Fixed-dose combinations with statins or other lipid agents.
- Specialty formulations targeting adherence or tolerability.
The largest historical value came from moving patients between formulations without requiring a change in the underlying therapeutic class. That strategy can preserve revenue temporarily, but it does not create a permanent barrier once comparable generic formulations are approved.
How does fenofibrate compare with competing lipid-lowering drugs?
Fenofibrate competes in different segments of dyslipidemia treatment rather than directly replacing every major lipid-lowering drug.
| Drug class |
Primary lipid effect |
Price position |
Competitive relationship |
| Statins |
LDL cholesterol reduction |
Low to moderate, mostly generic |
Main standard of care; often used with fenofibrate |
| Gemfibrozil |
Triglyceride reduction |
Low |
Direct fibrate competitor, but interaction profile limits some combinations |
| Fenofibrate |
Triglyceride reduction and HDL effects |
Low |
Preferred fibrate in many combination settings |
| Icosapent ethyl |
Cardiovascular-risk reduction in selected patients; triglyceride lowering |
Higher than generic fibrates |
Competes for high-risk hypertriglyceridemia patients |
| Prescription omega-3 mixtures |
Triglyceride reduction |
Variable |
Compete in severe hypertriglyceridemia |
| PCSK9 inhibitors |
Major LDL reduction |
High |
Address a different, higher-value lipid segment |
| Bempedoic acid |
LDL reduction |
Higher than generics |
Competes where statins are inadequate or poorly tolerated |
Fenofibrate benefits from its low cost and broad generic availability. It loses share when physicians prioritize therapies with stronger cardiovascular-outcome evidence or when triglyceride elevation is modest and LDL reduction is the main objective.
What generic entry risks exist for fenofibrate?
Generic entry risk is no longer a future event. It is the defining condition of the fenofibrate market.
For originator products, the principal risks are:
- Rapid pharmacy substitution.
- Formulary exclusion or unfavorable tiering.
- Loss of branded gross margin.
- Parallel generic launches.
- Price compression among manufacturers.
- Switching from branded fenofibrate to generic alternatives.
- Substitution with generic gemfibrozil or prescription omega-3 products.
For generic manufacturers, the main risks are different:
- Commodity pricing.
- API supply disruption.
- FDA inspection or manufacturing deficiencies.
- Product-specific bioequivalence failures.
- Excessive dependence on wholesalers and large pharmacy customers.
- Low margins after multiple ANDA holders enter.
Generic fenofibrate can remain profitable at scale, but the product is unlikely to support high-margin growth without a differentiated dosage form, combination product, or supply advantage.
What manufacturing and intellectual-property barriers affect fenofibrate?
Manufacturing barriers are manageable but not trivial. Fenofibrate’s solubility characteristics create formulation and bioequivalence requirements that are more demanding than those for highly soluble small molecules.
Key technical barriers include:
- Consistent micronization and particle-size distribution.
- Control of dissolution performance.
- Stability across storage conditions.
- Reproducible food-effect behavior.
- Scale-up from development batches to commercial production.
- Compliance with FDA current good manufacturing practice requirements.
- Reliable API sourcing and analytical testing.
Process patents may protect a particular manufacturing route, but most process claims do not prevent competitors from producing fenofibrate through an alternative method. The strongest remaining barriers are operational rather than legal.
Is biosimilar risk relevant to fenofibrate?
No. Fenofibrate is a chemically synthesized small molecule. Competitors enter through the generic-drug ANDA pathway, not through abbreviated biologic applications or biosimilar applications.
This distinction matters commercially. A biosimilar generally requires more complex analytical, clinical, and manufacturing comparability work. Fenofibrate generic entry is more scalable and typically produces faster price erosion once multiple approved products reach the market.
What licensing deals and corporate transactions shaped fenofibrate?
The most important transaction was Abbott’s acquisition of Kos Pharmaceuticals in 2006. The transaction transferred control of Tricor and expanded Abbott’s branded lipid portfolio.[3]
After Abbott separated its research-based pharmaceutical business into AbbVie in 2013, Tricor and related products became part of AbbVie’s inherited commercial portfolio. The strategic value of fenofibrate declined as generic competition expanded.
There is no comparable current licensing structure that gives a single company control over the global fenofibrate market. Commercial rights are fragmented among generic manufacturers, regional distributors, and companies selling branded or co-branded formulations.
What is the likely financial trajectory for fenofibrate?
Fenofibrate’s financial trajectory is mature and volume-driven.
Revenue outlook
- Branded revenue remains structurally depressed.
- Generic prescription volume should remain relatively stable in patients with severe triglyceride elevation and mixed dyslipidemia.
- Average selling prices will remain under pressure.
- Growth is more likely to come from emerging-market volume, supply consolidation, or differentiated products than from U.S. price expansion.
- Cardiovascular-outcome uncertainty limits premium positioning against newer therapies.
- Combination products could create incremental value but would require regulatory differentiation and payer acceptance.
The category is attractive for efficient manufacturers with low API costs and established U.S. distribution. It is less attractive for companies seeking high-margin branded growth.
What patent litigation or settlement agreements affect fenofibrate today?
The major patent disputes were associated with the launch of generic Tricor and related products. Those disputes shaped the timing of generic approval and launch but do not create a current market-wide entry barrier.
Historical settlement agreements may have affected individual launch dates or authorized-generic strategies. Their economic effect has largely expired because the relevant patents have reached the end of their enforceable commercial life and multiple generic products are available.
Current diligence should focus less on historical litigation and more on:
- Active FDA product approvals.
- ANDA holder count.
- Formulation-specific substitutability.
- Current manufacturing status.
- Supply concentration.
- State substitution rules.
- Payer and pharmacy purchasing behavior.
Key Takeaways
- Fenofibrate is a mature generic lipid-lowering market with durable but low-growth demand.
- Tricor generated billion-dollar-scale annual revenue during its branded peak before generic erosion.
- Abbott’s acquisition of Kos Pharmaceuticals was the defining corporate transaction.
- Core fenofibrate patents and major Tricor formulation protections have expired or lost practical blocking value.
- No biosimilar risk exists because fenofibrate is a small-molecule drug.
- Generic manufacturers compete on price, supply reliability, formulation performance, and distribution.
- Statins remain the primary competitors for lipid management, while icosapent ethyl and prescription omega-3 products compete in high-triglyceride populations.
- Manufacturing complexity is moderate, particularly for micronized and food-effect-sensitive formulations.
- The strongest commercial opportunities are low-cost generic scale, differentiated combinations, and emerging-market expansion.
- The weakest opportunities are undifferentiated branded reformulations without new clinical or regulatory value.
FAQs About Fenofibrate Market and Patent Strategy
Is fenofibrate still profitable for generic manufacturers?
Yes, but profitability depends on manufacturing scale, API cost, product quality, and the number of competing ANDA holders. It is a volume product rather than a high-price specialty medicine.
Does Tricor still have meaningful patent protection?
No broad patent barrier currently prevents generic substitution for standard fenofibrate products. Historical formulation patents shaped market entry but no longer support durable branded exclusivity.
Can a company obtain new patents on fenofibrate?
Yes. New patents may cover formulations, combinations, dosing regimens, manufacturing methods, or specific patient populations. Their value depends on clinical differentiation and enforceability.
Is fenofibrate used with statins?
It can be used with statins in selected patients, but clinicians must consider myopathy and other safety risks. Fenofibrate is generally viewed as more suitable for combination use than gemfibrozil in many treatment settings.[1]
Which fenofibrate products have the greatest commercial opportunity?
Products with improved bioavailability, reduced food dependence, fixed-dose combinations, convenient dosing, or strong supply reliability have more commercial potential than standard undifferentiated tablets.
References
-
U.S. Food and Drug Administration. (2023). Fenofibrate prescribing information. FDA.
-
Ginsberg, H. N., Elam, M. B., Lovato, L. C., Cinsberg, H., Leiter, L. A., Linz, P., et al. (2010). Effects of combination lipid therapy in type 2 diabetes mellitus. New England Journal of Medicine, 362(17), 1563-1574.
-
Abbott Laboratories. (2006). Abbott to acquire Kos Pharmaceuticals. Abbott press release.
-
Abbott Laboratories. (2009-2012). Annual reports and Form 10-K filings. U.S. Securities and Exchange Commission.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.