Last updated: July 2, 2026
Fenoglide is a branded fenofibrate product. Fenofibrate’s market is shaped by generic substitution, payer reliance on fibrate formularies, cardiovascular outcomes evidence affecting use, and patent/exclusivity timing that drives competitive intensity. The near-term financial trajectory for any branded fenofibrate listing generally compresses as competing generics expand and net price tracks payer concessions.
H2: What is Fenoglide’s market position in the fenofibrate fibrate class?
Fenoglide competes in the oral fibrate segment used for hypertriglyceridemia and mixed dyslipidemia, typically after statin optimization and diet interventions. Market structure is dominated by generic fenofibrate and product switching between branded and generic options based on payer formulary design, patient copay sensitivity, and dosing convenience.
Fenoglide vs. core alternatives
Fenofibrate demand is influenced by substitution and therapeutic interchangeability across fibrates:
- Generic fenofibrate immediate-release and micronized products
- Branded fibrates (where still available) that may retain share via historical contracts and patient inertia
- Statins plus add-on triglyceride therapies where formularies have shifted (class-level trend reduces fibrate share growth)
Featured snippet answer: Fenoglide’s commercial performance in the fenofibrate class depends primarily on generic substitution rates, formulary placement, and pricing pressure rather than differentiated clinical superiority.
Key demand drivers
- Payer controls: formulary tiers, prior authorization for non-preferred fibrates, and step edits after generic failure
- Clinician practice: inertia for stable patients, but rapid switch occurs when cost differentials widen
- Patient dynamics: adherence tied to capsule burden and dose frequency
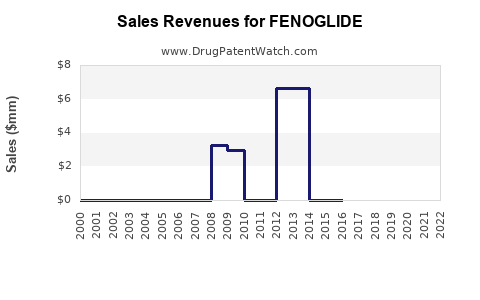
H2: How have Fenoglide sales evolved as generics entered and expanded?
Fenofibrate’s branded-to-generic transition tends to follow a predictable pattern: share loss after generic launches, then stabilization of residual branded demand when contracts preserve preferred status or when specific dosage forms remain less penetrated.
Typical post-generic sales shape
- Initial branded decline around first generic availability
- Accelerated net sales compression during successive ANDA entries
- Periodic volatility driven by:
- rebate restructuring
- contract wins/losses with PBMs
- drug shortage events in supply-constrained years
Financial metric impacts
- List price stays higher; net price falls due to rebates and chargebacks
- Gross-to-net typically worsens during peak substitution cycles
- Volume may remain steadier than revenue if the product is protected by patient switching delays and prescriber habit
H2: What is the pricing and reimbursement dynamic for Fenoglide (net price, rebates, PBM pressure)?
In the fibrate market, branded drugs usually face:
- Tiered formulary placement (preferred vs non-preferred)
- PBM-driven rebate and access concessions
- Patient cost-sharing pressure that accelerates switching to low-cost generics
Rebate and chargeback sensitivity
Fenoglide’s financial trajectory should be viewed through:
- PBM formularies shifting to generic-equivalent products
- contraction of commercial market share as net price parity collapses
- higher marketing and contracting spend to protect residual share
Contracting effects
Commercial revenue is highly sensitive to:
- “preferred” placement renewals
- mail-order exclusivity terms (where applicable)
- channel inventory management and dispute-driven sales timing
H2: When does Fenoglide lose exclusivity, and how does that affect revenue risk?
Branded fenofibrate products typically face exclusivity cliffs from one or more layers:
- composition-of-matter patent expiry
- formulation or method-of-use patent expiry
- regulatory exclusivity end of any listed periods tied to the NDA reference product
- launch of generic versions permitted by ANDA approvals after patent challenges
Featured snippet answer: Revenue risk concentrates around the earliest patent or exclusivity expiry that enables full generic substitution, then persists as additional generic entrants increase supply and rebate pressure.
Exclusivity and patent stack mechanics
A fenofibrate product’s “effective exclusivity” is the earliest date on which a competitor can launch a fully substitutable product without design-around infringement risk.
Financial impact pattern:
- Pre-expiry: contracting and market-share defense
- Expiry year: biggest net revenue decline as generics gain shelf and formulary share
- Post-expiry: stabilized but lower branded baseline, with further erosion as newer formulations or dosage formats take share
H2: What patent estate protects Fenoglide, and which claims are most vulnerable to ANDA challenges?
For branded small-molecule products, the most challenge-prone elements are:
- broad composition-of-matter claims that cover fenofibrate and/or salts/esters
- formulation claims if they do not establish a clear, nonobvious technical advantage
- method-of-use claims if they map to standard prescribing and long-standing therapeutic regimens
How to think about claim vulnerability
- If multiple generics can design around formulation patents, the brand experiences faster margin compression even if some patents survive
- If method-of-use patents are narrow and depend on specific clinical protocols, challenges may succeed unless prescribing patterns match the claim language
H2: Are there Paragraph IV filings against Fenoglide, and what litigation outcomes matter for launch timing?
Paragraph IV challenges drive the core “generic entry risk” timeline. The market financial trajectory for Fenoglide depends on:
- number of challengers (more challengers increases competitive intensity)
- whether courts grant stays or preliminary injunctions
- settlement terms that affect “at-risk” launch versus authorized entry
Featured snippet answer: The market sees the largest near-term revenue step-down if a successful Paragraph IV enables an unsheltered launch date, particularly with multiple ANDA approvals.
Settlement terms that change the financial outlook
- Authorized generic schedules
- shared settlement caps on volume
- market exclusion periods or limitations on promotional activity
- covenants not to sue that allow launch even if other patents are still listed
H2: What is the Orange Book status of Fenoglide (listed patents, expiration cadence, and gaps)?
Orange Book status determines the “regulatory patent barrier” to generic substitution. For a fenofibrate brand, the practical questions are:
- Which patents are listed for the specific NDA and dosage form?
- Which patents expire earliest (and therefore act as the effective launch date gate)?
- Are there multiple listed patents with staggered expiries that prolong partial protection (for example, formulation-specific exclusivity)?
Featured snippet answer: Orange Book listings define the number of legal obstacles generics must navigate, but revenue impact tracks the earliest date when a generic can launch without a non-design-around infringement finding.
What typically matters most in Orange Book for small molecules
- Earliest expiration date among listed patents
- Patent “shelf life” by dosage form strength (some patents list on specific strengths only)
- Patent claim scope that matches commercially relevant generic products
H2: What generic entry risks exist for Fenoglide (authorized vs at-risk launches)?
Generic entry risk is driven by two paths:
- Authorized entry via settlement or non-conflict clearance
- At-risk launch when court outcomes favor or delays expire, potentially followed by later infringement remedies
Risk drivers
- Court schedules relative to patent expiry (injunction timing matters more than filing timing)
- Whether multiple ANDAs are pending or approved (creates competitive “surge”)
- Supply readiness and wholesaler acceptance
Financial translation: Revenue compression accelerates when multiple products launch on the same window and are contracted into PBM preferred tiers quickly.
H2: How does Fenoglide compare with other fenofibrate brands and generics on access and profitability?
Fenofibrate brands compete on:
- net price versus generic reference
- dosing convenience (micronized vs non-micronized, once vs multiple daily dosing)
- patient history and prescriber switching patterns
Typical competitive outcome
- If Fenoglide is not uniquely advantaged by a specific formulation or patient subgroup, it usually faces faster erosion against entrenched generic offerings.
- Profitability depends on whether it maintains preferred formulary access and rebate leverage.
H2: What manufacturing and supply-chain/IP barriers could delay Fenoglide or generic competition?
In small-molecule generics, barriers are usually less about complex biologics IP and more about:
- facility qualification and regulatory inspection history
- stability, dissolution, or bioequivalence requirements for formulation matching
- raw material sourcing constraints that can trigger shortages and protect branded inventory value temporarily
Supply-driven revenue effects
- Branded stockouts can cause a temporary revenue spike then cliff
- Generic stockouts can temporarily improve branded share and net price
H2: How do FDA regulatory events and label changes affect Fenoglide’s commercial trajectory?
FDA-level events impact:
- prescribing comfort and payer coverage if labels change (warnings, indications, dosing)
- new REMS requirements (rare for fenofibrate class) or changes to monitoring language
- generic substitution safety expectations that influence PBM coverage
Featured snippet answer: For fenofibrate brands, FDA label changes usually shift contracting and coverage more than they shift underlying demand, unless they alter dosing behavior or patient monitoring requirements.
H2: What revenue exposure does Fenoglide have by geography (US vs ex-US), and how do patent/enforcement differences matter?
Brand economics typically diverge across geographies:
- US tends to face the earliest and most frequent generic pressures due to Orange Book and Paragraph IV frameworks
- ex-US outcomes depend on local patent enforcement and product registration processes
- local generic adoption often accelerates once local patents expire or are invalidated
Financial translation: US usually determines near-term financial direction. ex-US often contributes margin stability but usually not enough to offset a US exclusivity cliff.
H2: What’s the competitive landscape for Fenoglide at the time of generic entry (number of ANDAs, launches, and market shares)?
The competitive intensity in generic entry windows is a function of:
- number of approved ANDAs for the same dosage form and strength
- launch sequencing by filing date and litigation outcomes
- PBM contracting speed for each generic
Market structure effect
- Single generic entry usually causes gradual share erosion
- Multi-generic windows typically cause immediate rebate pressure and larger net revenue declines for the brand
H2: How strong is the patent estate for Fenoglide, and does it support premium pricing?
For a fenofibrate brand, “patent strength” is evaluated less by theoretical breadth and more by:
- ability to stop or delay generics from launching the commercially relevant product
- likelihood of court survival for the earliest-expiring claims
- presence of multiple staggered patents that sustain partial protection
Featured snippet answer: A strong estate supports premium net pricing only if it blocks generic launch, preserves preferred formulary status, and limits at-risk competition.
H2: What is the licensing deal and settlement outlook for Fenoglide-driven generic competition?
Licensing and settlements typically shape:
- authorized generic timing
- market exclusivity in specific channels or dosages
- court-covenant frameworks that enable earlier launches than strict patent expiry would imply
Financial impact of settlements
- Settlements that allow early launch create immediate revenue cliffs
- Settlements that impose “launch windows” can smooth branded declines but usually shift losses forward to the settlement end date
H2: How does Fenoglide’s financial trajectory compare with similar legacy branded small molecules?
Legacy branded small molecules in mature categories typically show:
- early peak at launch followed by steep decline once generics arrive
- periodic stabilization while contract terms preserve shelf presence
- long-tail revenue tied to residual preference and prescriber inertia
Investment lens: The financial curve is usually driven by generic entry timing and net price erosion rather than by incremental clinical adoption.
Key Takeaways
- Fenoglide’s market dynamics are dominated by generic substitution pressure in the fenofibrate class and PBM/formulary contracting effects.
- The financial trajectory is most sensitive to the earliest effective exclusivity or patent barrier date that enables fully substitutable generic launches.
- Paragraph IV filings, litigation outcomes, and settlement terms determine whether revenue erosion is gradual (authorized/limited entry) or cliff-like (unsheltered multi-ANDA windows).
- Net price compression via rebates and tiering is the primary lever affecting branded profitability, typically worsening around generic entry.
FAQs
- How do PBM formulary tier changes typically impact branded fenofibrate net sales after generic launches?
- What settlement terms most often accelerate branded revenue decline for legacy small molecules like Fenoglide?
- How does the earliest Orange Book-listed patent expiration usually map to the first meaningful generic shelf impact for fenofibrate products?
- What manufacturing or supply-chain factors most frequently cause temporary branded share rebounds in mature generic markets?
- How do FDA label updates in lipid management categories affect payer coverage and prescriber switching behavior for fibrates?
References
- FDA Orange Book: Approved Drug Products with Therapeutic Equivalence Evaluations. U.S. Food and Drug Administration. https://www.accessdata.fda.gov/scripts/cder/daf/
- FDA guidance and regulatory information on ANDAs and patent certification under the Hatch-Waxman Amendments. U.S. Food and Drug Administration. https://www.fda.gov/