Last updated: October 5, 2026
Niacin is a mature, largely commoditized vitamin and lipid-modifying ingredient with three distinct markets: prescription extended-release niacin, over-the-counter dietary supplements, and industrial and animal-feed applications. The prescription market has contracted sharply because of generic competition and limited incremental cardiovascular benefit when added to statin therapy. Growth is concentrated in low-cost supplements, fortified foods, feed additives, and pharmaceutical-grade raw materials.
What is the current market structure for niacin?
Niacin, also called nicotinic acid or vitamin B3, is sold in several forms with materially different commercial profiles.
| Segment |
Principal products |
Main buyers |
Market condition |
| Prescription niacin |
Extended-release niacin, immediate-release niacin, legacy brands such as Niaspan and Niacor |
Cardiologists, primary-care physicians, pharmacies |
Mature and declining |
| Dietary supplements |
Niacin tablets, capsules, flush-free formulations, multivitamins |
Consumers, retailers, e-commerce channels |
Large, fragmented, price competitive |
| Food fortification |
Flour, cereals, beverages, nutrition products |
Food manufacturers |
Stable, volume-driven |
| Animal nutrition |
Feed-grade niacin and derivatives |
Feed mills, livestock producers |
Cyclical and cost sensitive |
| Pharmaceutical ingredient |
Active pharmaceutical ingredient and intermediate supply |
Drug manufacturers |
Commodity-like, dependent on manufacturing scale |
Prescription niacin and consumer niacin should not be treated as one market. Prescription products compete on clinical positioning and reimbursement. Supplements compete on price, dosage, formulation, retail placement, and claims compliance.
Niacin is distinct from niacinamide, also called nicotinamide. Niacin is associated with flushing and has historically been used to modify lipid levels. Niacinamide is widely used in supplements, cosmetics, and dermatology products and generally does not produce the same flushing effect.
How has the prescription niacin market changed?
The prescription market has experienced structural decline since the broad adoption of high-intensity statins.
Niacin lowers triglycerides and low-density lipoprotein cholesterol while increasing high-density lipoprotein cholesterol. Earlier treatment strategies relied on these lipid changes as indicators of cardiovascular benefit. Large outcomes studies later weakened the commercial case for routine niacin use on top of statin therapy.
The AIM-HIGH trial found no incremental cardiovascular benefit from adding extended-release niacin to statin therapy in patients with established cardiovascular disease and controlled low-density lipoprotein cholesterol. The HPS2-THRIVE trial reached a similar commercial conclusion, reporting no significant reduction in major vascular events and identifying additional adverse effects associated with niacin-containing therapy (National Heart, Lung, and Blood Institute, 2011; HPS2-THRIVE Collaborative Group, 2014).
In 2016, the U.S. Food and Drug Administration determined that the evidence no longer supported continued use of certain niacin-statin combination indications. FDA withdrew approval of the extended-release niacin and statin combination products Advicor and Simcor for those indications, while standalone niacin products remained available for narrower uses (FDA, 2016).
The practical effect was a reduction in physician demand, formulary support, and commercial value for branded extended-release niacin.
What happened to Niaspan sales?
Niaspan was the principal branded extended-release niacin product in the United States. Abbott Laboratories developed and commercialized the product before transferring it to AbbVie following the 2013 separation of the two companies.
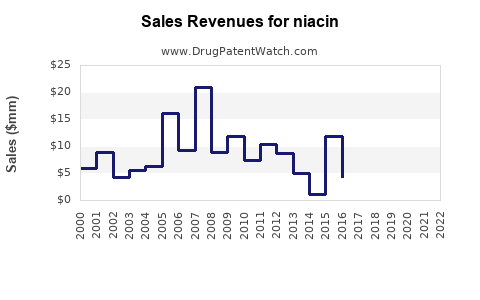
Niaspan generated more than $1 billion in annual sales near its commercial peak, according to Abbott and AbbVie financial disclosures. Sales declined as generic extended-release niacin entered the market and clinical evidence reduced demand for niacin-based lipid management (Abbott Laboratories, 2012; AbbVie, 2014).
The financial trajectory followed a conventional small-molecule lifecycle:
- Initial growth from prescription adoption and differentiation of the extended-release formulation.
- Peak sales supported by branded pricing and the use of niacin in combination lipid therapy.
- Patent and regulatory erosion.
- Generic substitution.
- Reduced prescribing after cardiovascular-outcomes evidence weakened the treatment rationale.
- Residual demand in selected dyslipidemia patients and low-price generic channels.
When did niacin lose exclusivity?
The commercial exclusivity of prescription niacin was lost in stages rather than on one date.
Niaspan received FDA approval in 1997. The product benefited from formulation and method-of-use protection, but its principal commercial barriers expired or weakened over time. Generic extended-release niacin products became available in the United States during the early 2010s, accelerating price erosion.
Niaspan’s product-specific patent and exclusivity history must be separated from the broader niacin molecule. The underlying niacin compound is long off-patent. Remaining protection historically focused on:
- Controlled-release delivery.
- Reduced-flushing formulations.
- Tablet composition and release profiles.
- Manufacturing processes.
- Combination use with statins.
- Specific treatment methods.
The FDA Orange Book remains the controlling source for listed patents and regulatory exclusivity associated with approved prescription products. The Orange Book does not establish patent validity. It identifies patents submitted by the sponsor and patent certifications made by abbreviated new drug applicants (FDA, n.d.-a).
What patents protect prescription niacin?
The principal patent value historically resided in extended-release and reduced-flush delivery technology rather than in niacin itself.
Patent estates associated with branded niacin products generally covered:
| Protection category |
Commercial purpose |
Current strategic value |
| Extended-release matrix |
Controls dissolution and dosing frequency |
Low after generic entry |
| Sustained-release tablet |
Reduces peak exposure and may moderate flushing |
Limited unless formulation is difficult to replicate |
| Combination therapy |
Links niacin with statins |
Reduced after FDA action and generic competition |
| Manufacturing process |
Controls granulation, compression, coating, or dissolution |
Relevant only if process claims remain enforceable |
| Method of treatment |
Targets dyslipidemia or cardiovascular-risk populations |
Narrow and difficult to enforce against generic substitution |
The estate is weak as a lifecycle-management platform because niacin has no remaining composition-of-matter exclusivity. Patent strength depends on claim scope, expiration, prosecution history, regulatory listing, and whether a generic product can avoid the claimed release profile.
How strong is the niacin patent estate?
The overall niacin patent estate is weak from an investment perspective.
Composition-of-matter protection
There is no meaningful composition-of-matter barrier around niacin. The active ingredient is an established vitamin and chemical commodity.
Formulation protection
Formulation patents have greater technical relevance but limited commercial durability. Generic applicants can pursue alternative release technologies, different excipients, or different manufacturing routes. A formulation patent may delay one product but generally does not prevent market entry by all competitors.
Method-of-use protection
Method-of-use patents can remain relevant when they cover a narrow patient population, dosing regimen, or treatment combination. Their practical value is constrained by:
- Declining physician use.
- Off-label prescribing.
- Difficulty proving induced infringement.
- Generic labeling strategies.
- The absence of strong current clinical demand.
Manufacturing protection
Manufacturing patents may create supplier-level advantages in yield, purity, particle size, or cost. They are more important in API and feed markets than in retail prescription products. Process claims rarely create durable branded pricing unless they produce a material quality or cost advantage.
What is the FDA regulatory status of niacin?
FDA regulates niacin through different pathways depending on the product category.
Prescription niacin products are approved drugs and must satisfy requirements for safety, efficacy, manufacturing quality, labeling, and post-market reporting. Generic versions are approved through abbreviated new drug applications and must demonstrate pharmaceutical equivalence and bioequivalence to the reference product.
Dietary supplements are regulated under the Dietary Supplement Health and Education Act. Manufacturers are responsible for ensuring product safety and truthful labeling, but dietary supplements do not undergo the same premarket efficacy review required for prescription drugs (FDA, n.d.-b).
This distinction affects market economics:
- Prescription products can make disease-treatment claims only under approved labeling.
- Supplements can make structure-function claims subject to required disclaimers.
- Prescription products face abbreviated-drug competition.
- Supplements face retail and brand competition rather than Orange Book substitution.
- Manufacturing quality and adverse-event reporting obligations differ by category.
Are there Paragraph IV challenges for niacin?
Paragraph IV risk was most relevant during the launch of generic extended-release niacin products. A generic applicant may certify that an Orange Book-listed patent is invalid, unenforceable, or will not be infringed. That certification can trigger patent litigation and a potential 30-month stay of FDA approval under the Hatch-Waxman framework.
The principal commercial significance of Paragraph IV activity for niacin has passed because:
- The reference product is mature.
- Multiple generic products have entered the market.
- Branded demand has declined.
- The remaining economic value is insufficient to support broad litigation in many cases.
Any live Paragraph IV dispute must be evaluated from current FDA Orange Book listings, ANDA approvals, and federal court dockets. Patent activity involving historical Niaspan formulations should not be treated as evidence of current market protection.
Which companies compete in the niacin market?
Competition differs by segment.
Prescription and generic drug companies
The prescription market includes the original branded sponsors, generic drug manufacturers, specialty distributors, and pharmacy suppliers. Generic competition has included large-volume manufacturers such as Teva, Mylan, Sandoz, and other ANDA holders, depending on product strength and formulation.
The key competitive factors are:
- Wholesale acquisition cost.
- Generic availability by strength.
- Pharmacy substitution.
- Supply continuity.
- API procurement.
- Formulation bioequivalence.
- Contracting with wholesalers and health plans.
Supplement companies
The supplement market is fragmented among national vitamin companies, private-label retailers, specialty nutrition brands, and online sellers. Brand differentiation is usually based on:
- Low-flush or flush-free positioning.
- Dose size.
- Combination products.
- Vegan or allergen-free claims.
- Third-party testing.
- Retail price.
- Delivery format.
Supplements face lower patent barriers and higher exposure to private-label competition. Trademark, formulation know-how, supplier relationships, and distribution are more important than drug patents.
API and feed suppliers
Bulk niacin is exposed to global manufacturing capacity, raw-material prices, energy costs, freight rates, regulatory compliance, and currency movements. Producers with integrated chemical operations may have lower unit costs than smaller formulators.
Is there biosimilar risk for niacin?
No. Niacin is a small-molecule chemical and is not subject to the biosimilar pathway.
Competitive entry occurs through generic drug applications, not biologics license applications or biosimilar applications. The relevant risks are ANDA competition, therapeutic substitution, supplement substitution, and API commoditization.
What licensing deals affect niacin?
Niacin has limited current licensing value. The market does not have the characteristics that normally support high-value licensing:
- No active composition patent.
- Limited prescription growth.
- Established generic manufacturing.
- Weak differentiation in the core molecule.
- Limited clinical-development activity.
- Broad availability of alternative lipid-lowering medicines.
Historical commercial arrangements involving Niaspan reflected branded commercialization and corporate ownership rather than a high-growth technology-licensing market. Abbott’s 2013 separation created AbbVie as the owner of Abbott’s pharmaceutical portfolio, including Niaspan-related commercial interests at that time (AbbVie, 2014).
Potential licensing value remains in specialized delivery technologies, combination products, or clinical uses that demonstrate a differentiated benefit. Those opportunities would require new clinical evidence and would not derive value from niacin’s basic composition.
What generic launch risks exist for niacin?
Generic entry risk is high for all conventional prescription niacin products.
| Risk |
Impact |
| Multiple ANDA applicants |
Rapid price erosion |
| Low switching costs |
High pharmacy substitution |
| Commodity API |
Limited supply differentiation |
| Weak branded demand |
Low retention after loss of exclusivity |
| No biosimilar barrier |
Simplified competitive pathway |
| Generic labeling constraints |
Limited ability to preserve branded clinical messaging |
| Alternative lipid therapies |
Reduced treatment demand |
A generic launch would typically produce the steepest price decline during the first several years after approval. The residual market can remain profitable for manufacturers that maintain reliable supply, but margins depend on scale and purchasing contracts.
How does niacin compare with competing lipid drugs?
Niacin has a weaker commercial position than newer lipid-lowering therapies.
| Product class |
Clinical positioning |
Patent strength |
Commercial outlook |
| Niacin |
Selected dyslipidemia uses; limited use with statins |
Weak and largely expired |
Mature or declining |
| Statins |
Foundational LDL reduction |
Mostly generic |
Large, stable volume |
| Ezetimibe |
LDL reduction, often combined with statins |
Generic in major markets |
Stable generic demand |
| PCSK9 inhibitors |
High-risk patients requiring substantial LDL reduction |
Stronger biologic or formulation protection |
Branded growth, reimbursement dependent |
| Fibrates |
Triglyceride-focused therapy |
Mostly generic |
Niche and mature |
| Bempedoic acid |
LDL reduction for selected patients, including statin-intolerant patients |
Active branded protection |
Smaller but differentiated |
| Omega-3 products |
Triglyceride reduction |
Mixed |
Fragmented and evidence sensitive |
Niacin’s main disadvantages are flushing, tolerability problems, uncertain incremental outcomes when combined with statins, and the availability of better-targeted therapies.
What is the revenue exposure to niacin?
Revenue exposure depends on the business model.
For a branded pharmaceutical company, niacin is usually immaterial relative to oncology, immunology, diabetes, cardiovascular specialty drugs, or biologics. The historical Niaspan revenue base was meaningful during peak commercialization but became a declining legacy asset after generic entry and adverse clinical evidence.
For supplement companies, niacin revenue is generally embedded within broader vitamin B, multivitamin, sports-nutrition, and wellness portfolios. Standalone niacin sales may be difficult to isolate from public filings.
For API and feed manufacturers, niacin revenue can be meaningful because volume is high even when unit prices are low. Profitability is determined by manufacturing efficiency, utilization, supply contracts, and input costs rather than patent exclusivity.
What is the geographic outlook for niacin?
The United States has the clearest prescription erosion because of generic substitution and mature statin use. Europe has similar pressure from generic competition and national reimbursement controls.
Growth and stability are more likely in:
- Emerging-market vitamin supplementation.
- Food fortification.
- Animal nutrition.
- Pharmaceutical manufacturing in lower-cost production regions.
- E-commerce supplement sales.
Geographic risk is concentrated in regulatory variation, import controls, quality inspections, currency volatility, and dependence on a limited number of API suppliers.
What manufacturing and intellectual-property barriers remain?
The main barriers are operational rather than patent-based.
Manufacturers must control:
- Chemical purity.
- Residual solvents and impurities.
- Particle size.
- Tablet dissolution.
- Stability.
- Batch consistency.
- Good manufacturing practice compliance.
- Supply-chain continuity.
For extended-release products, in vitro dissolution behavior and bioequivalence can create technical hurdles. Those hurdles may delay individual generic products but are unlikely to restore durable exclusivity to the category.
Key Takeaways
- Niacin is a mature market with separate prescription, supplement, food, feed, and API segments.
- Prescription niacin has declined because of generic entry and weak incremental cardiovascular-outcomes evidence when added to statins.
- Niaspan generated more than $1 billion in annual sales near its peak but lost commercial momentum after generic competition and changing treatment guidelines.
- Niacin has no meaningful remaining composition-of-matter protection.
- Formulation, method-of-use, and manufacturing patents may provide narrow protection but do not create a strong category-wide barrier.
- Niacin has no biosimilar risk because it is a small-molecule chemical.
- Generic entry risk is high, while current licensing value is limited.
- The strongest remaining opportunities are in supplements, food fortification, animal nutrition, and efficient API manufacturing.
- Financial performance is driven more by volume, production cost, distribution, and regulatory compliance than by intellectual-property exclusivity.
FAQs
Is niacin still prescribed for high cholesterol?
Yes, but use is substantially narrower than during the peak Niaspan era. Physicians generally favor statins and other lipid-lowering therapies with stronger cardiovascular-outcomes evidence.
Is prescription niacin still patent protected?
The niacin molecule is not patent protected. Any remaining protection is product-specific and may involve extended-release formulations, manufacturing methods, or narrow treatment claims.
Can a generic manufacturer launch extended-release niacin?
Yes, subject to FDA approval, bioequivalence requirements, applicable Orange Book certifications, and any enforceable patent or regulatory barriers.
Does niacin have investment potential as a pharmaceutical asset?
The conventional prescription product has limited investment appeal. More credible opportunities are tied to low-cost manufacturing, specialized delivery systems, food fortification, animal nutrition, or differentiated clinical applications.
What is the difference between niacin and niacinamide?
Niacin is nicotinic acid and can cause flushing at pharmacologic doses. Niacinamide is nicotinamide, a related form of vitamin B3 that generally does not cause the same flushing response and is widely used in supplements and cosmetics.
References
-
Abbott Laboratories. (2012). 2011 annual report. Abbott Laboratories.
-
AbbVie Inc. (2014). 2013 annual report. AbbVie Inc.
-
Food and Drug Administration. (2016). FDA asks manufacturers to remove certain indications for niacin-containing cholesterol medicines. U.S. Department of Health and Human Services.
-
Food and Drug Administration. (n.d.-a). Approved drug products with therapeutic equivalence evaluations, Orange Book. U.S. Department of Health and Human Services.
-
Food and Drug Administration. (n.d.-b). Dietary supplements. U.S. Department of Health and Human Services.
-
HPS2-THRIVE Collaborative Group. (2014). Effects of extended-release niacin with laropiprant in high-risk patients. New England Journal of Medicine, 371(3), 203-212.
-
National Heart, Lung, and Blood Institute. (2011). AIM-HIGH study stopped early. U.S. Department of Health and Human Services.