MELOXICAM - Generic Drug Details
✉ Email this page to a colleague
What are the generic drug sources for meloxicam and what is the scope of patent protection?
Meloxicam
is the generic ingredient in eight branded drugs marketed by Lupin, Novitium Pharma, Iceutica Operations, Baudax, Nanjing Delova, Azurity, Avondale Pharms, Tersera, Aiping Pharm Inc, Ascent Pharms Inc, Aurobindo Pharma, Chartwell Rx, Cipla, Corepharma, Cr Double Crane, Glenmark Pharms Ltd, Impax Labs Inc, Lupin Pharms, Mylan, Natco Pharma, Puracap Pharm, Rising, Roxane, Sun Pharm Inds Inc, Taro, Tp Anda Holdings, Unichem, Yung Shin Pharm, Zennova, Zydus Pharms Usa, Boehringer Ingelheim, and Axsome, and is included in thirty-three NDAs. There are one hundred and five patents protecting this compound and two Paragraph IV challenges. Additional information is available in the individual branded drug profile pages.Forty-eight suppliers are listed for this compound.
Summary for MELOXICAM
| International Patents: | 73 |
| US Patents: | 105 |
| Tradenames: | 8 |
| Applicants: | 32 |
| NDAs: | 33 |
| Finished Product Suppliers / Packagers: | 48 |
| Raw Ingredient (Bulk) Api Vendors: | 1 |
| Clinical Trials: | 104 |
| Patent Applications: | 5,212 |
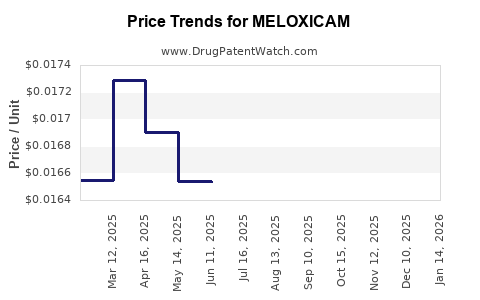
| Drug Prices: | Drug price trends for MELOXICAM |
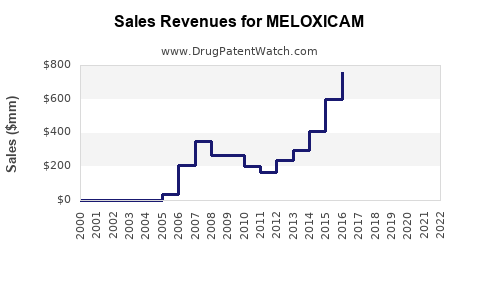
| Drug Sales Revenues: | Drug sales revenues for MELOXICAM |
| Patent Litigation and PTAB cases: | See patent lawsuits and PTAB cases for MELOXICAM |
| What excipients (inactive ingredients) are in MELOXICAM? | MELOXICAM excipients list |
| DailyMed Link: | MELOXICAM at DailyMed |
Recent Clinical Trials for MELOXICAM
Identify potential brand extensions & 505(b)(2) entrants
| Sponsor | Phase |
|---|---|
| University of Oklahoma | PHASE4 |
| St. Louis University | PHASE4 |
| St. Anne's University Hospital Brno, Czech Republic | PHASE2 |
Pharmacology for MELOXICAM
| Drug Class | Nonsteroidal Anti-inflammatory Drug |
| Mechanism of Action | Cyclooxygenase Inhibitors |
Anatomical Therapeutic Chemical (ATC) Classes for MELOXICAM
Paragraph IV (Patent) Challenges for MELOXICAM
US Patents and Regulatory Information for MELOXICAM
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | TE | Type | RLD | RS | Patent No. | Patent Expiration | Product | Substance | Delist Req. | Exclusivity Expiration |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Axsome | SYMBRAVO | meloxicam; rizatriptan benzoate | TABLET;ORAL | 215431-001 | Jan 30, 2025 | RX | Yes | Yes | 12,551,488 | ⤷ Start Trial | ⤷ Start Trial | ||||
| Cr Double Crane | MELOXICAM | meloxicam | TABLET;ORAL | 078039-002 | Dec 14, 2006 | DISCN | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| Axsome | SYMBRAVO | meloxicam; rizatriptan benzoate | TABLET;ORAL | 215431-001 | Jan 30, 2025 | RX | Yes | Yes | 10,265,324 | ⤷ Start Trial | ⤷ Start Trial | ||||
| Tp Anda Holdings | MELOXICAM | meloxicam | TABLET;ORAL | 077935-002 | Jul 19, 2006 | DISCN | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| Axsome | SYMBRAVO | meloxicam; rizatriptan benzoate | TABLET;ORAL | 215431-001 | Jan 30, 2025 | RX | Yes | Yes | 10,583,144 | ⤷ Start Trial | ⤷ Start Trial | ||||
| Roxane | MELOXICAM | meloxicam | TABLET;ORAL | 077925-002 | Jul 19, 2006 | DISCN | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >TE | >Type | >RLD | >RS | >Patent No. | >Patent Expiration | >Product | >Substance | >Delist Req. | >Exclusivity Expiration |
Expired US Patents for MELOXICAM
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | Patent No. | Patent Expiration |
|---|---|---|---|---|---|---|---|
| Baudax | ANJESO | meloxicam | SOLUTION;INTRAVENOUS | 210583-001 | Feb 20, 2020 | 10,463,673 | ⤷ Start Trial |
| Baudax | ANJESO | meloxicam | SOLUTION;INTRAVENOUS | 210583-001 | Feb 20, 2020 | 8,512,727 | ⤷ Start Trial |
| Baudax | ANJESO | meloxicam | SOLUTION;INTRAVENOUS | 210583-001 | Feb 20, 2020 | 10,471,067 | ⤷ Start Trial |
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >Patent No. | >Patent Expiration |
EU/EMA Drug Approvals for MELOXICAM
| Company | Drugname | Inn | Product Number / Indication | Status | Generic | Biosimilar | Orphan | Marketing Authorisation | Marketing Refusal |
|---|---|---|---|---|---|---|---|---|---|
| Norbrook Laboratories (Ireland) Limited | Loxicom | meloxicam | EMEA/V/C/000141DogsAlleviation of inflammation and pain in both acute and chronic musculoskeletal disorders. To reduce postoperative pain and inflammation following orthopaedic and soft-tissue surgery.CatsAlleviation of inflammation and pain in chronic musculoskeletal disorders in cats. To reduce postoperative pain after ovariohysterectomy and minor soft-tissue surgery.CattleFor use in acute respiratory infection with appropriate antibiotic therapy to reduce clinical signs in cattle. For use in diarrhoea in combination with oral rehydration therapy to reduce clinical signs in calves of over one week of age and young, non-lactating cattle. For adjunctive therapy in the treatment of acute mastitis, in combination with antibiotic therapy.PigsFor use in noninfectious locomotor disorders to reduce the symptoms of lameness and inflammation. For adjunctive therapy in the treatment of puerperal septicaemia and toxaemia (mastitis-metritis-agalactia syndrome) with appropriate antibiotic therapy.HorsesFor use in the alleviation of inflammation and relief of pain in both acute and chronic musculoskeletal disorders.For the relief of pain associated with equine colic. | Authorised | yes | no | no | 2009-02-10 | |
| Le Vet Beheer B.V. | Novaquin | meloxicam | EMEA/V/C/003866Alleviation of inflammation and relief of pain in both acute and chronic musculo-skeletal disorders in horses. | Authorised | no | no | no | 2015-09-08 | |
| Le Vet Beheer B.V | Meloxidolor | meloxicam | EMEA/V/C/002590DogsAlleviation of inflammation and pain in both acute and chronic musculoskeletal disorders.Reduction of postoperative pain and inflammation following orthopaedic and soft-tissue surgery.CatsReduction of postoperative pain after ovariohysterectomy and minor soft-tissue surgery.CattleFor use in acute respiratory infection with appropriate antibiotic therapy to reduce clinical signs.For use in diarrhoea in combination with oral rehydration therapy to reduce clinical signs in calves of over one week of age and young, non-lactating cattle.For adjunctive therapy in the treatment of acute mastitis, in combination with antibiotic therapy.PigsFor use in noninfectious locomotor disorders to reduce the symptoms of lameness and inflammation.For the relief of postoperative pain associated with minor soft-tissue surgery such as castration.For adjunctive therapy in the treatment of puerperal septicaemia and toxaemia (mastitis-metritis-agalactia syndrome) with appropriate antibiotic therapy.HorsesFor use in the alleviation of inflammation and relief of pain in both acute and chronic musculoskeletal disorders.For the relief of pain associated with equine colic. | Authorised | yes | no | no | 2013-04-22 | |
| Boehringer Ingelheim Vetmedica GmbH | Novem | meloxicam | EMEA/V/C/000086Novem 5-mg/ml solution for injection for cattle and pigs:CattleFor use in acute respiratory infection with appropriate antibiotic therapy to reduce clinical signs in cattle.For use in diarrhoea in combination with oral rehydration therapy to reduce clinical signs in calves of over one week of age and young, non-lactating cattle.For the relief of postoperative pain following dehorning in calves.PigsFor use in noninfectious locomotor disorders to reduce the symptoms of lameness and inflammation.For the relief of postoperative pain associated with minor soft-tissue surgery such as castration.Novem 20-mg/ml solution for injection for cattle and pigs:CattleFor use in acute respiratory infection with appropriate antibiotic therapy to reduce clinical signs in cattle.For use in diarrhoea in combination with oral rehydration therapy to reduce clinical signs in calves of over one week of age and young, non-lactating cattle.For adjunctive therapy in the treatment of acute mastitis, in combination with antibiotic therapy.For the relief of postoperative pain following dehorning in calves.PigsFor use in noninfectious locomotor disorders to reduce the symptoms of lameness and inflammation.For adjunctive therapy in the treatment of puerperal septicaemia and toxaemia (mastitis-metritis-agalactia syndrome) with appropriate antibiotic therapy.Novem 40 mg/ml solution for injection for cattle:For use in acute respiratory infection with appropriate antibiotic therapy to reduce clinical signs in cattle.For use in diarrhoea in combination with oral re-hydration therapy to reduce clinical signs in calves of over one week of age and young, non-lactating cattle.For adjunctive therapy in the treatment of acute mastitis, in combination with antibiotic therapy. | Authorised | no | no | no | 2004-03-02 | |
| Boehringer Ingelheim Vetmedica GmbH | Metacam | meloxicam | EMEA/V/C/000033Cats:Alleviation of mild to moderate post-operative pain and inflammation following surgical procedures, e.g. orthopaedic and soft tissue surgery.Alleviation of pain and inflammation in acute and chronic musculo-skeletal disorders.Reduction of post-operative pain after ovariohysterectomy and minor soft tissue surgery.Cattle:For use in acute respiratory infection with appropriate antibiotic therapy to reduce clinical signs.For use in diarrhoea in combination with oral re-hydration therapy to reduce clinical signs in calves of over one week of age and young, non-lactating cattle.For the relief of post-operative pain following dehorning in calves.For adjunctive therapy in the treatment of acute mastitis, in combination with antibiotic therapy.Dogs:Alleviation of inflammation and pain in both acute and chronic musculo-skeletal disorders.Reduction of post-operative pain and inflammation following orthopaedic and soft tissue surgery.Horses:For use in the alleviation of inflammation and relief of pain in both acute and chronic musculo-skeletal disorders.For the relief of pain associated with equine colic.Alleviation of inflammation and relief of pain in both acute and chronic musculo-skeletal disorders.Pigs: For use in non-infectious locomotor disorders to reduce the symptoms of lameness and inflammation.For the relief of post-operative pain associated with minor soft tissue surgery such as castration.For adjunctive therapy in the treatment of puerperal septicaemia and toxaemia (mastitis-metritis-agalactia syndrome) with appropriate antibiotic therapy.Guinea pigs:Alleviation of mild to moderate post-operative pain associated with soft tissues surgery such as male castration. | Authorised | no | no | no | 1998-01-07 | |
| Chanelle Pharmaceuticals Manufacturing Limited | Rheumocam | meloxicam | EMEA/V/C/000121DogsAlleviation of inflammation and pain in both acute and chronic musculo-skeletal disorders in dogs. To reduce post-operative pain and inflammation following orthopaedic and soft tissue surgery.CatsReduction of post-operative pain after ovariohysterectomy and minor soft tissue surgery.Alleviation of mild to moderate post-operative pain and inflammation following surgical procedures in cats, e.g. orthopaedic and soft tissue surgery.Alleviation of pain and inflammation in acute and chronic musculo-skeletal disorders in cats.CattleFor use in acute respiratory infection with appropriate antibiotic therapy to reduce clinical signs. For use in diarrhoea in combination with oral re-hydration therapy to reduce clinical signs in calves of over one week of age and young, non-lactating cattle. For adjunctive therapy in the treatment of acute mastitis, in combination with antibiotic therapy.PigsFor use in non-infectious locomotor disorders to reduce the symptoms of lameness and inflammation. For adjunctive therapy in the treatment of puerperal septicaemia and toxaemia (mastitis-metritis-agalactia syndrome) with appropriate antibiotic therapy. For the relief of post operative pain associated with minor soft tissue such as castration.HorsesAlleviation of inflammation and relief of pain in both acute and chronic musculo-skeletal disorders in horses..For the relief of pain associated with equine colic. | Authorised | yes | no | no | 2008-01-10 | |
| >Company | >Drugname | >Inn | >Product Number / Indication | >Status | >Generic | >Biosimilar | >Orphan | >Marketing Authorisation | >Marketing Refusal |
International Patents for MELOXICAM
| Country | Patent Number | Title | Estimated Expiration |
|---|---|---|---|
| Austria | 431131 | ⤷ Start Trial | |
| Canada | 2517679 | FORMULATIONS DE MELOXICANE NANOPARTICULAIRES (NANOPARTICULATE MELOXICAM FORMULATIONS) | ⤷ Start Trial |
| Germany | 602004021107 | ⤷ Start Trial | |
| Denmark | 3090731 | ⤷ Start Trial | |
| Denmark | 3434261 | ⤷ Start Trial | |
| European Patent Office | 1617816 | FORMULATIONS DE MELOXICANE NANOPARTICULAIRES (NANOPARTICULATE MELOXICAN FORMULATIONS) | ⤷ Start Trial |
| >Country | >Patent Number | >Title | >Estimated Expiration |
Meloxicam Market Dynamics, Generic Competition, and Financial Trajectory
More… ↓
Make Better Decisions: Try a trial or see plans & pricing
Drugs may be covered by multiple patents or regulatory protections. All trademarks and applicant names are the property of their respective owners or licensors. Although great care is taken in the proper and correct provision of this service, thinkBiotech LLC does not accept any responsibility for possible consequences of errors or omissions in the provided data. The data presented herein is for information purposes only. There is no warranty that the data contained herein is error free. We do not provide individual investment advice. This service is not registered with any financial regulatory agency. The information we publish is educational only and based on our opinions plus our models. By using DrugPatentWatch you acknowledge that we do not provide personalized recommendations or advice. thinkBiotech performs no independent verification of facts as provided by public sources nor are attempts made to provide legal or investing advice. Any reliance on data provided herein is done solely at the discretion of the user. Users of this service are advised to seek professional advice and independent confirmation before considering acting on any of the provided information. thinkBiotech LLC reserves the right to amend, extend or withdraw any part or all of the offered service without notice.
ISSN: 2162-2639

Privacy and Cookies
Terms & Conditions
Site Map
DrugPatentWatch Alternatives
LOE / Major Patent Expirations 2026 - 2027
NCE-1 Patent Challenge Dates 2026 - 2027
Friedman, Yali. "DrugPatentWatch" DrugPatentWatch, thinkBiotech, 2026, www.DrugPatentWatch.com.
See Primary Research Papers Citing DrugPatentWatch