Darunavir - Generic Drug Details
What are the generic drug sources for darunavir and what is the scope of freedom to operate?
Darunavir
is the generic ingredient in two branded drugs marketed by Janssen Prods, Amneal, Annora Pharma, Aurobindo Pharma Ltd, Cipla, Dr Reddys, Hetero Labs Ltd Iii, Lupin, MSN, Mylan, Teva Pharms Usa, and Zydus Lifesciences, and is included in thirteen NDAs. There is one patent protecting this compound and one Paragraph IV challenge. Additional information is available in the individual branded drug profile pages.Fourteen suppliers are listed for this compound. There are nine tentative approvals for this compound.
Summary for darunavir
| International Patents: | 48 |
| US Patents: | 1 |
| Tradenames: | 2 |
| Applicants: | 12 |
| NDAs: | 13 |
| Finished Product Suppliers / Packagers: | 14 |
| Raw Ingredient (Bulk) Api Vendors: | 96 |
| Clinical Trials: | 226 |
| Patent Applications: | 7,936 |
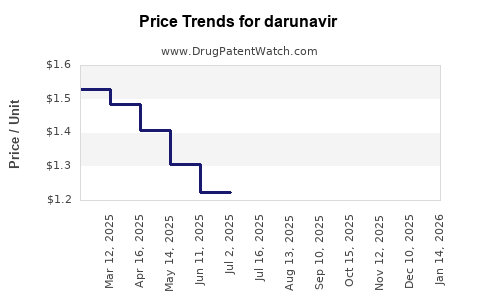
| Drug Prices: | Drug price trends for darunavir |
| What excipients (inactive ingredients) are in darunavir? | darunavir excipients list |
| DailyMed Link: | darunavir at DailyMed |
Recent Clinical Trials for darunavir
Identify potential brand extensions & 505(b)(2) entrants
| Sponsor | Phase |
|---|---|
| University of Nairobi | PHASE3 |
| London School of Hygiene and Tropical Medicine | PHASE3 |
| SolidarMed | PHASE3 |
Generic filers with tentative approvals for DARUNAVIR
| Applicant | Application No. | Strength | Dosage Form |
| ⤷ Start Trial | ⤷ Start Trial | 600MG | TABLET;ORAL |
| ⤷ Start Trial | ⤷ Start Trial | 400MG | TABLET;ORAL |
| ⤷ Start Trial | ⤷ Start Trial | 150MG | TABLET;ORAL |
The 'tentative' approval signifies that the product meets all FDA standards for marketing, and, but for the patents / regulatory protections, it would approved.
Pharmacology for darunavir
| Drug Class | Protease Inhibitor |
| Mechanism of Action | Cytochrome P450 2D6 Inhibitors Cytochrome P450 3A Inhibitors HIV Protease Inhibitors |
Anatomical Therapeutic Chemical (ATC) Classes for darunavir
US Patents and Regulatory Information for darunavir
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | TE | Type | RLD | RS | Patent No. | Patent Expiration | Product | Substance | Delist Req. | Exclusivity Expiration |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Janssen Prods | PREZISTA | darunavir | TABLET;ORAL | 021976-005 | Dec 18, 2008 | AB | RX | Yes | No | 7,700,645*PED | ⤷ Start Trial | Y | ⤷ Start Trial | ||
| Mylan | DARUNAVIR | darunavir | TABLET;ORAL | 202136-003 | Jul 22, 2025 | RX | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| Aurobindo Pharma Ltd | DARUNAVIR | darunavir | TABLET;ORAL | 210677-002 | Nov 28, 2023 | AB | RX | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Msn | DARUNAVIR | darunavir | TABLET;ORAL | 215389-002 | Nov 28, 2023 | AB | RX | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >TE | >Type | >RLD | >RS | >Patent No. | >Patent Expiration | >Product | >Substance | >Delist Req. | >Exclusivity Expiration |
Expired US Patents for darunavir
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | Patent No. | Patent Expiration |
|---|---|---|---|---|---|---|---|
| Janssen Prods | PREZISTA | darunavir | TABLET;ORAL | 021976-001 | Jun 23, 2006 | 5,583,131 | ⤷ Start Trial |
| Janssen Prods | PREZISTA | darunavir | TABLET;ORAL | 021976-001 | Jun 23, 2006 | 6,987,102 | ⤷ Start Trial |
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >Patent No. | >Patent Expiration |
EU/EMA Drug Approvals for darunavir
| Company | Drugname | Inn | Product Number / Indication | Status | Generic | Biosimilar | Orphan | Marketing Authorisation | Marketing Refusal |
|---|---|---|---|---|---|---|---|---|---|
| Mylan Pharmaceuticals Limited | Darunavir Mylan | darunavir | EMEA/H/C/004068Darunavir, co-administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV-1) infection (see section 4.2).Darunavir Mylan 75 mg, 150 mg, 300 mg and 600 mg tablets may be used to provide suitable dose regimens (see section 4.2):For the treatment of HIV-1 infection in antiretroviral treatment (ART)-experienced adult patients, including those that have been highly pre-treated.For the treatment of HIV-1 infection in paediatric patients from the age of 3 years and at least 15 kg body weight.In deciding to initiate treatment with darunavir co-administered with low dose ritonavir, careful consideration should be given to the treatment history of the individual patient and the patterns of mutations associated with different agents. Genotypic or phenotypic testing (when available) and treatment history should guide the use of darunavir (see sections 4.2, 4.4 and 5.1).Darunavir co-administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV-1) infection. Darunavir co-administered with cobicistat is indicated in combination with other antiretroviral medicinal products for the treatment of human immunodeficiency virus (HIV-1) infection in adults and adolescents (aged 12 years and older, weighing at least 40 kg) (see section 4.2). Darunavir Mylan 400 mg and 800 mg tablets may be used to provide suitable dose regimens for the treatment of HIV-1 infection in adult and paediatric patients from the age of 3 years and at least 40 kg body weight who are: antiretroviral therapy (ART)-naïve (see section 4.2). ART-experienced with no darunavir resistance associated mutations (DRV-RAMs) and who have plasma HIV-1 RNA < 100,000 copies/ml and CD4+ cell count ≥ 100 cells x 10⁶/L. In deciding to initiate treatment with darunavir in such ART-experienced patients, genotypic testing should guide the use of darunavir (see sections 4.2, 4.3, 4.4 and 5.1). | Authorised | yes | no | no | 2017-01-03 | |
| Janssen-Cilag International NV | Prezista | darunavir | EMEA/H/C/000707PREZISTA, co administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of human immunodeficiency virus (HIV 1) infection in adult and paediatric patients from the age of 3 years and at least 15 kg body weight.PREZISTA, co administered with cobicistat is indicated in combination with other antiretroviral medicinal products for the treatment of human immunodeficiency virus (HIV 1) infection in adults and adolescents (aged 12 years and older, weighing at least 40 kg).In deciding to initiate treatment with PREZISTA co administered with cobicistat or low dose ritonavir, careful consideration should be given to the treatment history of the individual patient and the patterns of mutations associated with different agents. Genotypic or phenotypic testing (when available) and treatment history should guide the use of PREZISTA.PREZISTA, co administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV 1) infection.PREZISTA 75 mg, 150 mg, and 600 mg tablets may be used to provide suitable dose regimens:For the treatment of HIV 1 infection in antiretroviral treatment (ART) experienced adult patients, including those that have been highly pre treated.For the treatment of HIV 1 infection in paediatric patients from the age of 3 years and at least 15 kg body weight.In deciding to initiate treatment with PREZISTA co administered with low dose ritonavir, careful consideration should be given to the treatment history of the individual patient and the patterns of mutations associated with different agents. Genotypic or phenotypic testing (when available) and treatment history should guide the use of PREZISTA.PREZISTA, co administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV 1) infection.PREZISTA, co administered with cobicistat is indicated in combination with other antiretroviral medicinal products for the treatment of human immunodeficiency virus (HIV 1) infection in adults and adolescents (aged 12 years and older, weighing at least 40 kg).PREZISTA 400 mg and 800 mg tablets may be used to provide suitable dose regimens for the treatment of HIV 1 infection in adult and paediatric patients from the age of 3 years and at least 40 kg body weight who are:antiretroviral therapy (ART) naïve.ART experienced with no darunavir resistance associated mutations (DRV RAMs) and who have plasma HIV 1 RNA < 100,000 copies/ml and CD4+ cell count ≥ 100 cells x 106/L. In deciding to initiate treatment with PREZISTA in such ART experienced patients, genotypic testing should guide the use of PREZISTA. | Authorised | no | no | no | 2007-02-11 | |
| KRKA, d.d., Novo mesto | Darunavir Krka d.d. | darunavir | EMEA/H/C/004891400mg and 800 mg Film-coated TabletsDarunavir Krka d.d., co-administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV-1) infection.Darunavir Krka d.d., co-administered with cobicistat is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV-1) infection in adult patients (see section 4.2).Darunavir Krka d.d. 400 mg and 800 mg tablets may be used to provide suitable dose regimens for the treatment of HIV-1 infection in adult and paediatric patients from the age of 3 years and at least 40 kg body weight who are:antiretroviral therapy (ART)-naïve (see section 4.2).ART-experienced with no darunavir resistance associated mutations (DRV-RAMs) and who have plasma HIV-1 RNA < 100,000 copies/ml and CD4+ cell count ≥ 100 cells x 106/l. In deciding to initiate treatment with darunavir in such ART-experienced patients, genotypic testing should guide the use of darunavir (see sections 4.2, 4.3, 4.4 and 5.1).600mg Film-coated TabletsDarunavir Krka d.d., co-administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV-1) infection.Darunavir Krka d.d. 600 mg tablets may be used to provide suitable dose regimens (see section 4.2):For the treatment of HIV-1 infection in antiretroviral treatment (ART)-experienced adult patients, including those that have been highly pre-treated.For the treatment of HIV-1 infection in paediatric patients from the age of 3 years and at least 15 kg body weight.In deciding to initiate treatment with darunavir co-administered with low dose ritonavir, careful consideration should be given to the treatment history of the individual patient and the patterns of mutations associated with different agents. Genotypic or phenotypic testing (when available) and treatment history should guide the use of darunavir. | Withdrawn | yes | no | no | 2018-01-18 | |
| KRKA, d.d., Novo mesto | Darunavir Krka | darunavir | EMEA/H/C/004273400 and 800 mgDarunavir Krka, co-administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV-1) infection.Darunavir Krka 400 mg and 800 mg tablets may be used to provide suitable dose regimens for the treatment of HIV-1 infection in adult and paediatric patients from the age of 3 years and at least 40 kg body weight who are:antiretroviral therapy (ART)-naïve (see section 4.2).ART-experienced with no darunavir resistance associated mutations (DRV-RAMs) and who have plasma HIV-1 RNA < 100,000 copies/ml and CD4+ cell count ≥ 100 cells x 106/l. In deciding to initiate treatment with darunavir in such ART-experienced patients, genotypic testing should guide the use of darunavir (see sections 4.2, 4.3, 4.4 and 5.1).600 mg Darunavir Krka, co-administered with low dose ritonavir is indicated in combination with other antiretroviral medicinal products for the treatment of patients with human immunodeficiency virus (HIV-1) infection.Darunavir Krka 600 mg tablets may be used to provide suitable dose regimens (see section 4.2):For the treatment of HIV-1 infection in antiretroviral treatment (ART)-experienced adult patients, including those that have been highly pre-treated.For the treatment of HIV-1 infection in paediatric patients from the age of 3 years and at least 15 kg body weight.In deciding to initiate treatment with darunavir co-administered with low dose ritonavir, careful consideration should be given to the treatment history of the individual patient and the patterns of mutations associated with different agents. Genotypic or phenotypic testing (when available) and treatment history should guide the use of darunavir. | Authorised | yes | no | no | 2018-01-26 | |
| >Company | >Drugname | >Inn | >Product Number / Indication | >Status | >Generic | >Biosimilar | >Orphan | >Marketing Authorisation | >Marketing Refusal |
International Patents for darunavir
| Country | Patent Number | Title | Estimated Expiration |
|---|---|---|---|
| African Regional IP Organization (ARIPO) | 2052 | Pseudopolymorphic forms of HIV protease inhibitor | ⤷ Start Trial |
| Australia | 2003271740 | PSEUDOPOLYMORPHIC FORMS OF A HIV PROTEASE INHIBITOR | ⤷ Start Trial |
| Australia | 2012205289 | Pseudopolymorphic forms of a HIV protease inhibitor | ⤷ Start Trial |
| Brazil | 0311176 | Formas pseudopolimórficas de um inibidor da protease do hiv | ⤷ Start Trial |
| >Country | >Patent Number | >Title | >Estimated Expiration |
Supplementary Protection Certificates for darunavir
| Patent Number | Supplementary Protection Certificate | SPC Country | SPC Expiration | SPC Description |
|---|---|---|---|---|
| 3150586 | 2090020-5 | Sweden | ⤷ Start Trial | PRODUCT NAME: COBICISTAT OR A PHARMACEUTICALLY ACCEPTABLE SALT OR SOLVATE THEREOF, DARUNAVIR OR A PHARMACEUTICALLY ACCEPTABLE SALT OR SOLVATE THEREOF, IN PARTICULAR DARUNAVIR ETHANOLATE, AND EMTRICITABINE OR A PHARMACEUTICALLY ACCEBTABLE SALT OR SOLVATE THEREOF; FIRST MARKETING AUTHORIZATION NUMBER SE: EG EU/1/17/1225, 2017-09-25; RAETTAD SKYDDSTID FOER TILLAEGGSSKYDD'; PRV HAR I BESLUT DEN 8 JULI 2025 RAETTAT SKYDDSTIDEN I FOELJANDE TILLAEGGSSKYDD I ENLIGHET MED PMD:S BESLUT PMAE 7804/24: 2290016-1, 2090020-5, 2090055-1, 1590060-8, 1890030-8, 1990012-5, 2190017-0, 1690040-9, 1790035-8, 2390005-3, 1990013-3, 2090009-8 |
| 3150586 | 301045 | Netherlands | ⤷ Start Trial | PRODUCT NAME: COBICISTAT OF EEN FARMACEUTISCH AANVAARDBAAR ZOUT OF SOLVAAT DAARVAN, DARUNAVIR OF EEN FARMACEUTISCH AANVAARDBAAR ZOUT OF SOLVAAT DAARVAN, IN HET BIJZONDER DARUNAVIRETHANOLAAT, EN EMTRICITABINE OF EEN FARMACEUTISCH AANVAARDBAAR ZOUT OF SOLVAAT DAARVAN; REGISTRATION NO/DATE: EU/1/17/1225 20170925 |
| 2487162 | 300861 | Netherlands | ⤷ Start Trial | PRODUCT NAME: COBICISTAT, DAN WEL EEN FARMACEUTISCH AANVAARDBAAR ZOUT OF SOLVAAT DAARVAN EN DARUNAVIR, DAN WEL EEN FARMACEUTISCH AANVAARDBAAR ZOUT OF SOLVAAT DAARVAN. IN HET BIJZONDER DARUNAVIRETHANOLAAT; REGISTRATION NO/DATE: EU/1/14/967 20141121 |
| 2487162 | 284 1-2017 | Slovakia | ⤷ Start Trial | PRODUCT NAME: KOBICISTAT VO VSETKYCH FORMACH CHRANENYCH ZAKLADNYM PATENTOM/DARUNAVIR VO VSETKYCH FORMACH CHRANENYCH ZAKLADNYM PATENTOM; REGISTRATION NO/DATE: EU/1/14/967 20141121 |
| >Patent Number | >Supplementary Protection Certificate | >SPC Country | >SPC Expiration | >SPC Description |
Darunavir Market Dynamics, Financial Trajectory, Patent Protection and Generic Risk
More… ↓
Make Better Decisions: Try a trial or see plans & pricing
Drugs may be covered by multiple patents or regulatory protections. All trademarks and applicant names are the property of their respective owners or licensors. Although great care is taken in the proper and correct provision of this service, thinkBiotech LLC does not accept any responsibility for possible consequences of errors or omissions in the provided data. The data presented herein is for information purposes only. There is no warranty that the data contained herein is error free. We do not provide individual investment advice. This service is not registered with any financial regulatory agency. The information we publish is educational only and based on our opinions plus our models. By using DrugPatentWatch you acknowledge that we do not provide personalized recommendations or advice. thinkBiotech performs no independent verification of facts as provided by public sources nor are attempts made to provide legal or investing advice. Any reliance on data provided herein is done solely at the discretion of the user. Users of this service are advised to seek professional advice and independent confirmation before considering acting on any of the provided information. thinkBiotech LLC reserves the right to amend, extend or withdraw any part or all of the offered service without notice.
ISSN: 2162-2639

Privacy and Cookies
Terms & Conditions
Site Map
DrugPatentWatch Alternatives
LOE / Major Patent Expirations 2026 - 2027
NCE-1 Patent Challenge Dates 2026 - 2027
Friedman, Yali. "DrugPatentWatch" DrugPatentWatch, thinkBiotech, 2026, www.DrugPatentWatch.com.
See Primary Research Papers Citing DrugPatentWatch