Last updated: September 8, 2026
Oxycodone is a mature controlled-substance market with declining branded revenue, persistent generic volume, and high regulatory and litigation exposure. The commercial center shifted from Purdue Pharma’s OxyContin extended-release franchise to low-cost immediate-release and extended-release generics. U.S. demand remains material because oxycodone is widely used for acute and cancer-related pain, but prescribing restrictions, opioid stewardship, abuse-deterrent alternatives, production quotas, and payer pressure limit growth.
How large is the oxycodone market?
The United States is the most commercially significant oxycodone market, although products are sold globally under different regulatory controls and brand names. Public data do not provide a single audited revenue figure for all oxycodone products because sales are split among branded products, authorized generics, hospital contracts, retail generics, combination products, and international markets.
The market has three main segments:
| Segment |
Representative products |
Commercial position |
| Immediate-release oxycodone |
Oxycodone hydrochloride tablets, capsules, and oral solutions |
Predominantly generic; used for acute and breakthrough pain |
| Extended-release oxycodone |
OxyContin and generic oxycodone ER |
Branded originator declined sharply; generic competition is established |
| Oxycodone combinations |
Percocet and generic oxycodone-acetaminophen products |
Large generic segment; acetaminophen limits dosing and shapes prescribing |
The U.S. opioid market contracted after prescription volumes peaked in the early 2010s. CDC data show that opioid dispensing fell from more than 240 million prescriptions in 2011 to roughly 125 million prescriptions in 2023. Oxycodone declined with the broader market, although it remains one of the most frequently dispensed opioid ingredients (Centers for Disease Control and Prevention, 2024).
What drives oxycodone demand?
Demand is concentrated in:
- Postoperative and short-term acute pain
- Cancer-related pain
- Palliative care
- Severe musculoskeletal and traumatic pain
- Breakthrough pain in patients receiving chronic analgesic treatment
The market is constrained by prescription-duration limits, electronic prescribing controls, opioid risk-management requirements, hospital stewardship programs, prior authorization, and physician substitution toward non-opioid analgesics.
Oxycodone remains commercially resilient because it is familiar to prescribers, available in multiple dosage strengths, and supported by extensive generic manufacturing capacity. Its use is less dependent on a single branded product than it was during the OxyContin expansion period.
What is the financial trajectory of oxycodone?
The financial trajectory has four phases.
1. Branded expansion before generic erosion
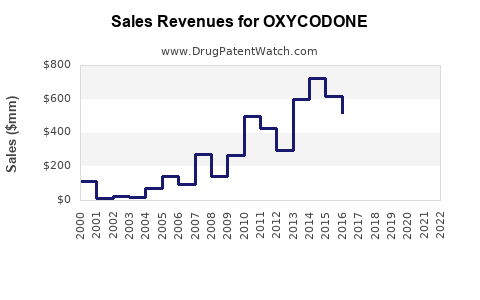
OxyContin became a major pharmaceutical product after its launch in 1996. Purdue Pharma generated multi-billion-dollar annual sales at the height of the extended-release franchise. Public reporting placed OxyContin sales at approximately $3 billion annually around the product’s peak period, although reported figures vary by year and accounting methodology (U.S. Department of Justice, 2020).
The original commercial model depended on:
- Extended-release dosing convenience
- High prescription frequency
- Premium branded pricing
- Broad primary-care prescribing
- Long-term treatment positioning
2. Patent expiry and generic entry
OxyContin lost core protection over time, and generic oxycodone ER products entered the market. Purdue’s reformulated abuse-deterrent product delayed some substitution but did not preserve the original revenue base. Generic competition reduced average selling prices and moved the category toward contract manufacturing and low-margin volume sales.
3. Demand contraction and litigation liabilities
Oxycodone revenue declined as U.S. prescribing fell and public-health controls intensified. Purdue’s commercial value became increasingly offset by litigation, restructuring, government claims, and settlement obligations. Purdue filed for Chapter 11 protection in 2019 as part of a restructuring process connected to opioid litigation (Purdue Pharma, 2019).
The financial impact was asymmetric:
- Branded OxyContin revenue declined.
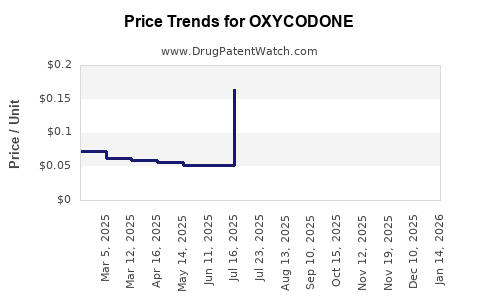
- Generic manufacturers retained volume but faced price compression.
- Distributors and pharmacies faced compliance and settlement costs.
- Manufacturers incurred legal, monitoring, and controlled-substance compliance expenses.
- State and local governments pursued opioid-related damages and remediation payments.
4. Mature generic and institutional market
The current oxycodone market is primarily a mature generic market. Revenue growth is more likely to come from pricing, supply availability, hospital contracts, new dosage forms, or geographic expansion than from increased prescription volume.
The highest-value commercial opportunities are limited:
- Authorized or branded generic supply agreements
- Hospital and integrated delivery network contracts
- Specialized oral solutions and dosage strengths
- Abuse-deterrent extended-release products
- International markets with controlled but stable medical use
- Manufacturing capacity during shortages
For standard immediate-release tablets, the category has low product differentiation and limited pricing power.
What is the FDA regulatory status of oxycodone?
Oxycodone is an FDA-approved prescription opioid and a Schedule II controlled substance in the United States. Schedule II status applies to products with recognized medical use but high abuse, dependence, and diversion risk.
FDA-approved oxycodone products include:
- Oxycodone hydrochloride immediate-release tablets
- Oxycodone oral solutions and concentrates
- Oxycodone extended-release tablets
- Oxycodone-acetaminophen combination products
- Oxycodone-ibuprofen combination products
OxyContin is an extended-release oxycodone product marketed by Purdue Pharma. The current formulation was designed with physicochemical properties intended to make crushing and extraction more difficult than with the original formulation. FDA describes the product as abuse-deterrent, not abuse-proof. Abuse-deterrent labeling does not eliminate overdose risk or prevent all forms of misuse (U.S. Food and Drug Administration, 2023a).
What is the Orange Book status of oxycodone?
The Orange Book contains multiple oxycodone-related entries because oxycodone is sold under several approved applications and dosage forms. The relevant regulatory distinctions are:
| Product category |
Orange Book position |
Competitive effect |
| Immediate-release oxycodone |
Multiple generic approvals |
High generic density and low differentiation |
| Oxycodone-acetaminophen |
Numerous abbreviated new drug applications |
Strong price competition |
| Oxycodone ER |
Brand and generic listings, subject to product-specific patents and certifications |
Greater technical and regulatory barriers than immediate-release products |
| Abuse-deterrent oxycodone ER |
Product-specific labeling and formulation requirements |
More limited competition and higher development cost |
Orange Book patent listings and exclusivity status must be reviewed by product and application number. A single “oxycodone patent expiration date” is not accurate because immediate-release, combination, extended-release, and abuse-deterrent products have different regulatory histories.
What patents protect oxycodone products?
Oxycodone itself is an old active pharmaceutical ingredient and is not protected by meaningful composition-of-matter exclusivity in the United States. Commercial protection has instead centered on formulations, delivery systems, manufacturing processes, and labeling.
What patents protected OxyContin?
The historical OxyContin patent estate included patents directed to controlled-release oxycodone formulations and abuse-deterrent technology. Important historical examples include:
| Patent |
General subject matter |
Commercial relevance |
| U.S. Patent No. 5,508,042 |
Controlled-release oxycodone formulation |
Core historical OxyContin protection |
| U.S. Patent No. 5,656,295 |
Controlled-release oral opioid formulation |
Extended-release formulation protection |
| U.S. Patent No. 7,074,430 |
Controlled-release opioid formulation technology |
Associated with later formulation protection |
| U.S. Patent No. 8,652,513 |
Abuse-deterrent or formulation-related oxycodone protection |
Relevant to reformulated OxyContin protection |
Patent terms depend on filing dates, patent-term adjustments, terminal disclaimers, continuations, and regulatory extensions. The principal commercial effect of these patents has already occurred: they delayed or complicated generic entry but did not preserve a high-growth branded market after broad generic substitution and prescription contraction.
How strong is the oxycodone patent estate?
The oxycodone patent estate is weak for the active ingredient and stronger for specific dosage forms.
| Patent layer |
Strength |
Reason |
| Oxycodone molecule |
Very weak |
Long-established small molecule |
| Immediate-release tablets |
Weak |
Numerous generic approvals and limited formulation differentiation |
| Combination products |
Weak to moderate |
Formulation and labeling claims exist, but generic competition is extensive |
| Extended-release tablets |
Moderate |
Manufacturing, bioequivalence, and formulation requirements raise entry barriers |
| Abuse-deterrent ER products |
Moderate to strong for specific claims |
Technical formulation and bioequivalence challenges are more complex |
| Manufacturing processes |
Variable |
Protection depends on claim scope and practical design-around options |
| Method-of-use claims |
Variable |
Often vulnerable to label carve-outs and prescribing limitations |
The remaining commercial value lies in product-specific formulation protection, not in oxycodone as a chemical entity.
When did oxycodone lose exclusivity?
Immediate-release oxycodone has been generic for decades. The significant exclusivity event involved extended-release oxycodone and OxyContin.
OxyContin’s original commercial protection began eroding as patents expired and generic developers pursued abbreviated new drug applications. Purdue introduced a reformulated OxyContin product in 2010, with abuse-deterrent characteristics and a different regulatory profile. FDA approved the reformulation and later recognized its abuse-deterrent labeling under applicable regulatory standards (U.S. Food and Drug Administration, 2023a).
The practical exclusivity timeline is:
| Period |
Market event |
| 1996 |
OxyContin launched in the United States |
| 2000s |
OxyContin reaches peak commercial importance |
| 2010 |
Reformulated abuse-deterrent OxyContin approved |
| Early-to-mid 2010s |
Core OxyContin patent barriers begin expiring or losing commercial force |
| 2015 onward |
Generic oxycodone ER competition expands |
| 2019 |
Purdue files for bankruptcy protection |
| 2020s |
Mature generic market with declining prescription volume |
Were there Paragraph IV challenges to OxyContin?
Yes. Generic drug applicants used Paragraph IV certifications to challenge patents listed for extended-release oxycodone products. These challenges alleged that listed patents were invalid, unenforceable, or would not be infringed by the proposed generic product.
Paragraph IV disputes affected:
- Generic oxycodone ER timing
- Formulation design
- Abuse-deterrent characteristics
- Patent litigation costs
- Settlement and launch timing
- The commercial value of remaining listed patents
The principal generic litigation strategy was to develop a product capable of demonstrating bioequivalence while avoiding or challenging specific formulation claims. Generic applicants also faced the technical question of whether their product would carry abuse-deterrent labeling or compete as a conventional extended-release product.
Because oxycodone products are approved under multiple applications, Paragraph IV analysis must be conducted by NDA, ANDA, dosage strength, formulation, and patent listing. Broad conclusions about all oxycodone products are unreliable.
Which companies compete in the oxycodone market?
The U.S. competitive landscape includes originator, generic, specialty, and contract manufacturers.
Branded and specialty participants
- Purdue Pharma: OxyContin
- Rhodes Pharmaceuticals: generic and specialty controlled-substance products
- Hikma Pharmaceuticals: generic opioid products
- Mallinckrodt: generic controlled substances and opioid products
- Teva Pharmaceuticals: generic oxycodone and combination products
- Endo and Par Pharmaceutical: historical participation in generic and specialty opioid markets
- Amneal Pharmaceuticals: generic controlled-substance products
- Ingenus Pharmaceuticals and other specialty manufacturers: selected dosage forms and contract opportunities
Availability changes by dosage strength, application holder, manufacturing site, and wholesaler inventory. A company may hold an approval without maintaining continuous commercial supply.
How does oxycodone compare with hydrocodone?
| Attribute |
Oxycodone |
Hydrocodone |
| Main use |
Acute, severe, cancer, and breakthrough pain |
Acute and chronic pain, often in combination products |
| Generic status |
Mature generic market |
Mature generic market |
| Potency perception |
Often viewed as more potent milligram-for-milligram |
Broad primary-care and dental use |
| Combination products |
Commonly combined with acetaminophen |
Historically dominated by hydrocodone-acetaminophen |
| Commercial risk |
High litigation and regulatory exposure |
High litigation and regulatory exposure |
| Growth outlook |
Low |
Low |
Oxycodone has a stronger association with extended-release branded commercialization through OxyContin. Hydrocodone has historically had broader combination-product penetration.
What generic entry risks exist for oxycodone?
For standard immediate-release oxycodone, generic entry risk is already realized. The commercial issue is price erosion rather than future entry.
For extended-release and abuse-deterrent oxycodone, the main risks are:
- New ANDA approvals by manufacturers with existing controlled-substance infrastructure.
- Patent invalidity or noninfringement findings.
- Successful Paragraph IV challenges.
- FDA approval of a non-abuse-deterrent generic that competes on price.
- Reimbursement policies that favor generic substitution.
- Hospital purchasing contracts that exclude branded products.
- Manufacturing scale advantages held by large generic suppliers.
The principal barriers are FDA bioequivalence requirements, controlled-substance quotas, specialized manufacturing, stability testing, abuse-deterrent performance, and supply-chain compliance. These barriers slow entry but do not recreate originator-level pricing power.
What is the impact of opioid litigation and settlement agreements?
Oxycodone is directly linked to the U.S. opioid litigation environment. Purdue’s bankruptcy process involved claims by states, municipalities, tribes, hospitals, and individuals. The Purdue restructuring plan contemplated payments and value transfers connected to opioid abatement, with the Sackler family also contributing under the restructuring framework. The legal status and enforceability of specific settlement provisions have changed through appellate and Supreme Court proceedings (Supreme Court of the United States, 2024).
Litigation affects market economics through:
- Direct settlement payments
- Legal defense expenses
- Insurance costs
- Compliance monitoring
- Product withdrawal decisions
- Restrictions on marketing and distribution
- Counterparty diligence requirements
- Reputational and financing constraints
Generic manufacturers have also faced lawsuits and settlements, although their exposure differs from Purdue’s because many did not develop or market OxyContin as an originator product. Distributor and pharmacy liability has created additional pressure on controlled-substance supply chains.
What is the outlook for oxycodone revenue?
The base-case outlook is stable-to-declining revenue in the United States.
| Driver |
Expected effect |
| Declining opioid prescribing |
Negative for volume |
| Generic substitution |
Negative for price |
| Cancer and palliative-care demand |
Supports baseline demand |
| Aging population and surgery volume |
Supports selective demand |
| Abuse-deterrent technology |
Supports premium niches |
| Controlled-substance quotas |
Can create shortages and intermittent revenue |
| Litigation and compliance expense |
Negative for margins |
| Hospital contracts |
Supports volume but compresses price |
| International markets |
Selective growth opportunity |
| New non-opioid analgesics |
Long-term substitution risk |
The branded OxyContin franchise is unlikely to return to its historical revenue scale. The more durable opportunity is in generic supply, specialty dosage forms, contract manufacturing, and markets where reliable controlled-substance capacity is scarce.
How significant is oxycodone revenue exposure for manufacturers?
Oxycodone exposure is material for companies with concentrated controlled-substance portfolios but usually limited for diversified pharmaceutical companies.
A manufacturer’s risk profile depends on:
- Share of revenue from oxycodone and other opioids
- Dependence on U.S. retail pharmacies
- Number of approved suppliers
- Exposure to government purchasing
- Product-specific litigation
- Manufacturing-site concentration
- DEA quota allocation
- Ability to shift capacity to non-opioid products
For a diversified generic company, oxycodone is usually a modest revenue contributor. For a specialty controlled-substance manufacturer, it can be a core product category with higher regulatory and legal sensitivity.
What is the biosimilar risk for oxycodone?
There is no biosimilar risk because oxycodone is a chemically synthesized small-molecule drug, not a biologic. Competition proceeds through the generic drug pathway, primarily abbreviated new drug applications under the Federal Food, Drug, and Cosmetic Act.
The relevant competitive risks are generic entry, formulation substitution, therapeutic substitution, and non-opioid alternatives.
Key Takeaways
- Oxycodone is a mature, genericized controlled-substance market.
- OxyContin generated substantial branded revenue but no longer supports an originator-scale growth profile.
- Oxycodone’s active ingredient has no meaningful remaining composition-of-matter exclusivity.
- Remaining patent value is concentrated in extended-release, abuse-deterrent, manufacturing, and product-specific method claims.
- Immediate-release oxycodone faces entrenched generic competition and limited pricing power.
- Extended-release oxycodone has higher technical entry barriers but remains exposed to Paragraph IV challenges and generic substitution.
- U.S. opioid prescription volume has fallen sharply from its early-2010s peak.
- Purdue’s bankruptcy and the opioid litigation cycle materially changed the economic value of the franchise.
- Biosimilar competition is irrelevant; generic competition is the central risk.
- Future oxycodone revenue is likely to remain stable to declining, with selective opportunities in specialty formulations, institutional supply, and international markets.
FAQs About Oxycodone Market and Patent Economics
Is OxyContin still commercially important?
OxyContin remains a recognized branded extended-release oxycodone product, but its commercial importance is far below its historical peak because of generic competition, lower opioid prescribing, regulatory controls, and litigation-related restructuring.
Does oxycodone have a composition-of-matter patent?
No commercially meaningful U.S. composition-of-matter exclusivity remains for oxycodone. Product protection historically came from controlled-release formulations, abuse-deterrent technology, manufacturing methods, and related claims.
Can a generic company launch oxycodone without challenging every patent?
A generic applicant can use Paragraph III, Paragraph IV, or a section viii statement depending on the listed patent and proposed labeling. The applicable route depends on the specific NDA, formulation, dosage strength, and patent claim.
Are abuse-deterrent oxycodone products immune from generic competition?
No. Abuse-deterrent products can face generic competition, although formulation complexity, bioequivalence testing, labeling requirements, and patent disputes may delay entry and increase development costs.
Is oxycodone a growth market outside the United States?
Selected international markets may grow from low prescription bases, expanded cancer care, and improved palliative-care access. Growth is constrained by narcotics controls, import restrictions, diversion concerns, and national reimbursement policies.
References
-
Centers for Disease Control and Prevention. (2024). U.S. opioid dispensing rate maps and data. U.S. Department of Health and Human Services.
-
Purdue Pharma L.P. (2019). Voluntary petition for bankruptcy and restructuring materials. United States Bankruptcy Court for the Southern District of New York.
-
Supreme Court of the United States. (2024). Harrington v. Purdue Pharma L.P., 603 U.S. 204.
-
U.S. Department of Justice. (2020). Purdue Pharma agrees to plead guilty to federal felony charges and pay over $8 billion. U.S. Department of Justice.
-
U.S. Food and Drug Administration. (2023a). OxyContin prescribing information. FDA.
-
U.S. Food and Drug Administration. (2023b). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
U.S. Patent and Trademark Office. (n.d.). Patent Center and patent term information for U.S. Patent Nos. 5,508,042; 5,656,295; 7,074,430; and 8,652,513. USPTO.