Last updated: August 20, 2026
Ondansetron is a mature, off-patent antiemetic with broad use in chemotherapy-induced nausea and vomiting, radiotherapy-induced nausea and vomiting, and postoperative nausea and vomiting. The original Zofran franchise lost its primary U.S. market protection in the mid-2000s, enabling broad generic entry. Revenue has therefore shifted from branded pharmaceutical sales to low-margin, high-volume generic tablets, orally disintegrating tablets, oral solutions, and injectable products.
The market remains commercially durable because ondansetron is inexpensive, familiar to clinicians, included in hospital protocols, and used across oncology, surgery, emergency medicine, and outpatient care. Its principal risks are price erosion, supplier concentration, injectable manufacturing constraints, therapeutic substitution, and regulatory scrutiny over off-label use, particularly in pregnancy and pediatric populations.
What is the current market position of ondansetron?
Ondansetron is a foundational generic antiemetic rather than a premium pharmaceutical asset. The active ingredient is a selective 5-HT3 receptor antagonist. Its main commercial forms are:
| Dosage form |
Typical commercial channel |
Market characteristics |
| 4 mg and 8 mg tablets |
Retail, specialty, hospital outpatient |
Highly commoditized |
| Orally disintegrating tablets |
Retail and outpatient |
Retains convenience value but faces generic competition |
| Oral solution |
Pediatric, geriatric, institutional |
Smaller volume, formulation-specific demand |
| Injectable solution |
Hospitals, surgery centers, oncology |
More concentrated supplier base and greater manufacturing sensitivity |
| Branded Zofran products |
Limited legacy or residual branded demand |
No meaningful broad U.S. exclusivity advantage |
The product is prescribed primarily for nausea and vomiting associated with moderately or highly emetogenic chemotherapy, radiotherapy, and surgery. Physicians also use it widely in emergency and outpatient settings for acute nausea, gastroenteritis, and other off-label indications.
Ondansetron is listed in the World Health Organization Model List of Essential Medicines in the antiemetic category, supporting persistent global demand even where pricing is low.[1]
How did ondansetron reach the generic market?
The U.S. Food and Drug Administration approved Zofran, containing ondansetron hydrochloride, in 1991 for chemotherapy-induced nausea and vomiting. FDA subsequently approved additional dosage forms and indications, including injection, oral solution, orally disintegrating tablets, and postoperative nausea and vomiting.[2]
The key commercial milestones were:
| Event |
Approximate timing |
Commercial effect |
| Original U.S. approval of Zofran |
1991 |
Established the branded market |
| Expansion into injection and oral formulations |
1990s |
Increased hospital and oncology utilization |
| Orally disintegrating tablet introduction |
Late 1990s |
Added convenience-oriented differentiation |
| Primary patent and regulatory protection expiration |
Mid-2000s |
Opened the market to ANDA competition |
| Broad generic availability |
2006 onward |
Rapid price and share erosion for branded Zofran |
| Mature multisupplier market |
2010s to present |
High volume, low unit economics |
GlaxoSmithKline was the principal historical innovator and commercial sponsor of Zofran. Generic competition subsequently expanded across tablets, orally disintegrating tablets, oral solution, and injection products.
What patents protect ondansetron, and when did exclusivity end?
Ondansetron has no current U.S. composition-of-matter patent barrier comparable to those protecting newer specialty medicines. The original Zofran patent estate was directed to ondansetron and related pharmaceutical compositions and formulations. The principal historical U.S. patent commonly associated with the product was U.S. Patent No. 4,695,578, which covered antiemetic compounds including ondansetron-related technology.[3]
The relevant protection expired before the current generic market matured. Pediatric exclusivity and regulatory extensions affected the final timing of generic availability, but those protections ended in the mid-2000s. FDA-approved generic products are now widely available.
What is the Orange Book status of ondansetron?
The FDA Orange Book lists approved ondansetron products and historical reference-listed drug information. The commercial significance of the Orange Book for ondansetron is now limited because the principal innovator exclusivity period has ended and numerous abbreviated new drug applications have been approved.[4]
The practical regulatory position is:
- No active U.S. market exclusivity protects the original Zofran franchise.
- Generic manufacturers can compete through ANDA approvals.
- Any remaining formulation or method-of-use patents would have limited commercial effect unless they block a specific dosage form or indication.
- Injectable products may face manufacturing and supply constraints independent of patent status.
How many patents cover ondansetron today?
The number of patents mentioning ondansetron is much higher than the number of patents capable of blocking generic competition. Later patents may cite ondansetron in combination products, delivery systems, packaging, dosing methods, or broader antiemetic regimens. Those references do not recreate exclusivity for the active ingredient.
The economically relevant patent categories are:
| Patent category |
Current impact |
| Composition-of-matter patents |
Expired |
| Core pharmaceutical composition patents |
Expired or commercially exhausted |
| Tablet and orally disintegrating formulations |
Limited blocking power after generic approvals |
| Injectable formulations |
May protect manufacturing or presentation details, but not the molecule |
| Combination therapies |
Narrow and indication-specific |
| Method-of-use patents |
Limited value because of broad prior clinical use and generic labeling constraints |
| Manufacturing patents |
Can raise barriers for individual suppliers without restoring market exclusivity |
Patent strength is therefore low for the overall ondansetron market. It can be moderate for a narrow formulation, device, or manufacturing process if the patent is enforceable and difficult to design around, but those rights do not create a broad branded franchise.
When did ondansetron lose market exclusivity?
Ondansetron lost its commercially meaningful U.S. exclusivity in the mid-2000s, with generic launch activity becoming material in 2006. The result was a standard small-molecule patent cliff:
- Branded Zofran held substantial oncology and hospital utilization.
- Generic manufacturers entered after expiration of the principal protection.
- Payers substituted lower-cost products.
- Branded pricing power declined rapidly.
- The market stabilized around high prescription volume and low average selling prices.
Unlike a biologic facing biosimilar substitution, ondansetron faced direct generic competition. FDA-approved ANDA products are generally substitutable at the pharmacy level when state substitution rules and dosage-form equivalence permit it.
Which companies compete in the ondansetron market?
The market is fragmented across regional and global generic manufacturers. Companies that have marketed or obtained U.S. approvals for ondansetron products include Teva Pharmaceutical Industries, Sandoz, Dr. Reddy’s Laboratories, Hikma Pharmaceuticals, Fresenius Kabi, Aurobindo Pharma, Amneal Pharmaceuticals, and other ANDA sponsors.[2][4]
The competitive landscape differs by dosage form.
Tablets and orally disintegrating tablets
These products have the highest degree of commoditization. Competition is based on:
- Contracting with wholesalers and pharmacy benefit managers
- Product availability
- Manufacturing cost
- FDA compliance history
- Ability to maintain multiple strengths
- Stable supply during demand spikes
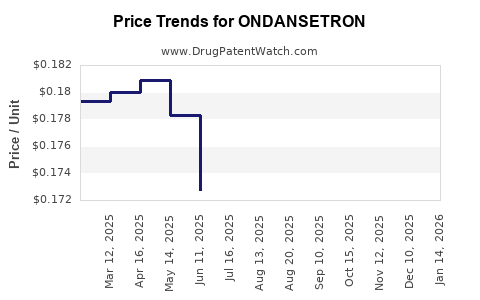
Unit prices are generally compressed because several approved suppliers can compete for the same prescriptions.
Oral solution
Oral solution has a smaller market but can offer better economics than standard tablets when there are fewer qualified suppliers. Pediatric use, institutional purchasing, and dosing flexibility support demand. The product remains exposed to generic substitution and hospital tender pricing.
Injection
Ondansetron injection is commercially more sensitive to manufacturing quality, sterile-facility capacity, container availability, and hospital contracts. Injectable generic markets can experience temporary shortages when one or more suppliers encounter production or inspection problems. These events can improve short-term pricing for remaining suppliers, but they do not create durable patent protection.
What is the financial trajectory of ondansetron?
The financial trajectory has four distinct phases.
| Phase |
Revenue profile |
Margin profile |
Primary driver |
| Branded growth, 1990s |
Expanding and relatively high |
High branded margins |
New indications and dosage forms |
| Late-brand period, early 2000s |
Mature and substantial |
High but declining |
Established oncology and surgical demand |
| Generic entry, 2006 onward |
Sharp branded decline |
Generic margins compressed |
ANDA competition and substitution |
| Mature generic market, present |
Stable volume, low unit revenue |
Low to moderate, formulation-dependent |
Supply reliability and contract scale |
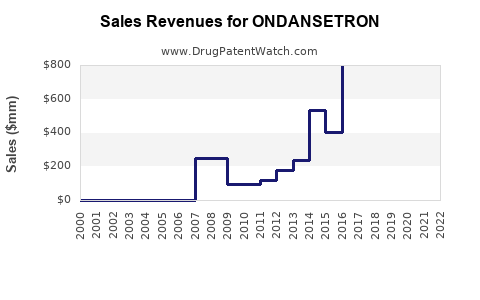
Public companies generally do not report ondansetron revenue as a separate line item. It is usually included in broader generic pharmaceutical, hospital products, or injectable product revenue. That prevents a clean, audited global market-revenue series for the molecule.
The economics are best understood through volume and price rather than franchise revenue:
- Prescription and hospital demand remains durable.
- The active ingredient is inexpensive to manufacture relative to complex biologics or sterile injectables.
- Standard oral products have limited pricing power.
- Injectable products can produce better short-term economics during shortages.
- Wholesale acquisition price, net contract price, and pharmacy reimbursement can differ materially.
- Large suppliers benefit from procurement scale, manufacturing utilization, and distribution reach.
The branded Zofran business experienced the largest value destruction after generic entry. Generic manufacturers captured volume but competed away much of the molecule’s economic surplus. The winners were companies with efficient manufacturing, strong distribution, or differentiated presentations rather than companies holding legacy patents.
What financial factors drive ondansetron demand?
Oncology utilization
Chemotherapy remains a structural demand base. Modern antiemetic regimens often combine a 5-HT3 antagonist with a neurokinin-1 antagonist, dexamethasone, olanzapine, or other agents depending on emetogenic risk. Ondansetron remains useful because it is inexpensive and familiar, even where newer regimens are preferred for highly emetogenic chemotherapy.[5]
Surgery and procedural care
Postoperative nausea and vomiting creates recurring demand in hospitals and ambulatory surgery centers. Use depends on surgical volume, anesthesia protocols, patient risk factors, and institutional formulary preferences.
Emergency and outpatient prescribing
Emergency departments and outpatient clinicians use ondansetron for acute nausea and vomiting. This channel expanded the product beyond its original oncology-centered market, but much of this use is off-label. Demand is sensitive to prescribing protocols and payer policy.
Pediatric demand
Oral solution and weight-based dosing support pediatric use. Pediatric utilization can support formulation-level differentiation, although the underlying molecule remains generic.
Global access
Ondansetron is used internationally, but market value varies sharply by country. Low-income markets are more price-sensitive and may rely on local manufacturers. Higher-income markets have stronger hospital procurement systems and greater use of combination antiemetic regimens.
What regulatory status does ondansetron have?
Ondansetron is an FDA-approved small-molecule drug. FDA-approved products include oral tablets, orally disintegrating tablets, oral solution, and injection, depending on the manufacturer and product presentation.[2]
Regulatory considerations include:
- Dose selection by indication and patient population
- QT-interval prolongation risk
- Drug interactions involving serotonergic agents
- Hepatic impairment considerations
- Sterile manufacturing controls for injection
- Labeling restrictions for approved indications
- State and federal rules affecting off-label prescribing and substitution
The most commercially important regulatory distinction is between oral and injectable products. Oral products have low technical barriers and many suppliers. Injectable products require validated sterile manufacturing and are more exposed to inspection findings and supply interruptions.
Are there biosimilar or generic entry risks for ondansetron?
Biosimilar risk does not apply because ondansetron is a chemically synthesized small molecule, not a biologic. Generic entry is already established and is the central market condition.
The remaining competitive risks are:
| Risk |
Exposure |
| Additional oral generic entrants |
High |
| Further tablet price erosion |
High |
| Injectable supplier disruption |
Moderate to high |
| New branded reformulation |
Low |
| Therapeutic substitution by newer antiemetics |
Moderate |
| Patent-based blocking strategy |
Low |
| Regulatory withdrawal of a major supplier |
Moderate |
| Hospital purchasing consolidation |
High |
A new entrant would generally need a cost, supply, formulation, or distribution advantage. Patent ownership alone is unlikely to support a premium strategy for standard ondansetron.
What Paragraph IV challenges and litigation affect ondansetron?
Ondansetron was subject to the ordinary generic patent-challenge environment surrounding an aging branded product. ANDA applicants could challenge listed patents through Paragraph IV certifications once the relevant protections became vulnerable. Generic competition ultimately entered the U.S. market, indicating that the patent estate did not prevent commercial substitution.
There is no broadly recognized current U.S. patent litigation campaign that materially limits access to standard ondansetron tablets or injection. Historical disputes were principally tied to generic entry timing, listed patents, and regulatory approval rather than a continuing battle over the molecule.
Settlement agreements, where used during the generic-entry period, are no longer central to the present market structure. The commercial question has moved from launch timing to manufacturing reliability, contract access, and price discipline.
What formulations are protected or commercially differentiated?
Current formulation differentiation is narrow but economically relevant.
Orally disintegrating tablets
ODT products offer administration without water and can be useful for patients with active nausea. The original branded presentation created differentiation, but generic ODT products have substantially reduced the value of that distinction.
Oral solution
Oral solution supports pediatric and dose-flexible use. Commercial advantages can arise from taste, packaging, dosing devices, and supply reliability. These factors are practical rather than durable patent barriers.
Injection
Injection has the strongest operational barriers because sterile manufacturing is complex. A supplier can gain share during shortages, but the advantage depends on regulatory compliance and production capacity.
Combination products
Ondansetron may be used in combination antiemetic regimens, but combination use does not generally provide a proprietary moat for the ondansetron component. Newer fixed-dose products would require separate clinical, regulatory, and commercial justification.
How does ondansetron compare with competing antiemetics?
| Drug or class |
Competitive position versus ondansetron |
Commercial implication |
| Granisetron |
Same broad 5-HT3 class |
Competes on formulary preference and price |
| Palonosetron |
Longer-acting 5-HT3 antagonist |
Stronger differentiation in some chemotherapy regimens |
| Dolasetron |
Historically comparable class product |
Reduced current relevance |
| Aprepitant and other NK1 antagonists |
Used in combination for higher-risk chemotherapy |
Captures value in premium oncology regimens |
| Olanzapine |
Increasing role in selected antiemetic protocols |
Can reduce reliance on single-agent 5-HT3 therapy |
| Promethazine and prochlorperazine |
Low-cost alternatives for some indications |
Compete in emergency and general nausea markets |
| Metoclopramide |
Broad antiemetic and gastrointestinal use |
Substitutable in selected settings |
Ondansetron remains strongest where low cost, predictable tolerability, oral convenience, and broad familiarity matter. It is less differentiated in high-risk chemotherapy protocols that require multi-drug prevention of delayed nausea and vomiting.
What generic launch scenarios exist for ondansetron?
The market is already in the post-generic phase, so launch scenarios relate to new suppliers and new presentations rather than first generic entry.
Base case
Multiple suppliers continue selling standard oral products. Prices remain low, demand remains stable, and revenue growth tracks prescription volume or hospital utilization rather than price increases.
Supply-constrained case
A sterile manufacturing disruption reduces injectable supply. Remaining suppliers gain temporary volume and potentially improve net pricing. The effect fades as competitors restore capacity or new suppliers receive approval.
Reformulation case
A supplier introduces a differentiated delivery system, packaging format, or combination product. Commercial success depends on reimbursement and clinical utility because standard ondansetron is inexpensive.
Demand-erosion case
Hospitals and clinicians increasingly use longer-acting 5-HT3 antagonists or combination regimens. Ondansetron retains broad use but loses selected higher-value oncology applications.
What is the geographic coverage of ondansetron?
Ondansetron has broad global coverage through national regulatory approvals, local generic manufacturers, and hospital procurement channels. The United States is a mature generic market with substantial price pressure. Europe is similarly genericized, with national reimbursement and tender systems affecting pricing. Emerging markets often have more fragmented supply and greater reliance on local manufacturers.
Geographic commercial strength depends on:
- National registration status
- Local manufacturing capacity
- Hospital tender participation
- Pharmacist substitution rules
- Reimbursement limits
- Sterile injectable availability
- Distribution infrastructure
The molecule’s low cost supports broad access but limits revenue per unit.
How strong is the ondansetron patent estate?
The overall patent estate is weak from an investment or licensing perspective. Core molecule protection has expired, generic products are established, and no current patent position appears capable of restoring broad exclusivity for standard presentations.
The strongest residual opportunities are operational:
- Injectable manufacturing
- Pediatric oral-solution packaging
- Adherence-oriented delivery systems
- Hospital supply contracts
- Regional regulatory registrations
- Contract manufacturing and private-label supply
These opportunities can generate cash flow but are unlikely to support a high-value asset transaction based solely on ondansetron rights.
Key Takeaways
- Ondansetron is a mature, off-patent generic antiemetic.
- The original Zofran franchise lost meaningful U.S. exclusivity in the mid-2000s.
- Generic competition has eliminated most branded pricing power.
- Tablets and ODT products are highly commoditized.
- Injectable ondansetron has greater operational value because sterile manufacturing can constrain supply.
- No biosimilar risk applies; direct generic competition is already established.
- Financial performance depends on volume, manufacturing cost, supply reliability, and hospital contracts.
- Public companies generally do not disclose ondansetron revenue separately.
- The molecule remains commercially durable because of oncology, surgery, emergency, pediatric, and outpatient demand.
- Patent value is low, while manufacturing and distribution capabilities provide the main competitive advantages.
FAQs About Ondansetron Market Economics and Exclusivity
Is ondansetron still protected by a brand patent?
No. The principal U.S. patent protection associated with Zofran and ondansetron expired in the mid-2000s. Standard ondansetron products are now supplied primarily by generic manufacturers.
Can a company obtain FDA exclusivity for a new ondansetron formulation?
Potentially, but a new formulation would need qualifying innovation and FDA approval. Any exclusivity would generally apply to the specific formulation or indication, not the ondansetron molecule as a whole.
Why can injectable ondansetron be more profitable than tablets?
Sterile injectable manufacturing requires specialized facilities, validation, quality controls, and regulatory compliance. Fewer reliable suppliers can support better pricing during shortages, although hospital contracting keeps long-term margins under pressure.
Does ondansetron face competition from palonosetron?
Yes. Palonosetron competes directly within the 5-HT3 antagonist class and has longer-acting properties. Ondansetron remains more cost-competitive and broadly available, while palonosetron can be favored in selected chemotherapy protocols.
Is ondansetron a potential licensing or acquisition target?
A standard ondansetron product is unlikely to justify a large strategic transaction based on patent value. Licensing or acquisition interest would more likely focus on regional distribution, sterile manufacturing capacity, differentiated delivery systems, or a broader hospital antiemetic portfolio.
References
-
World Health Organization. (2023). WHO model list of essential medicines: 23rd list. World Health Organization.
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs, ondansetron products and labeling. U.S. Department of Health and Human Services.
-
United States Patent and Trademark Office. (1987). U.S. Patent No. 4,695,578: Antiemetic compositions. U.S. Department of Commerce.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book. U.S. Department of Health and Human Services.
-
National Comprehensive Cancer Network. (2024). NCCN clinical practice guidelines in oncology: Antiemesis. National Comprehensive Cancer Network.