Last updated: August 18, 2026
Chlorthalidone is a mature, low-cost antihypertensive with no meaningful remaining composition-of-matter exclusivity. Its commercial outlook is driven by prescription volume, guideline adoption, generic manufacturing economics, and demand for low-cost diuretics rather than by pricing power or patent protection. Revenue is likely to remain stable in aggregate but modest at the product level, with limited visibility because manufacturers generally do not report chlorthalidone sales separately.
What is the current market position of chlorthalidone?
Chlorthalidone is a long-acting thiazide-like diuretic used primarily for hypertension and, less frequently, edema. It competes with hydrochlorothiazide, indapamide, loop diuretics, and fixed-dose antihypertensive combinations.
The drug has a differentiated clinical profile:
- Long duration of action, commonly described as approximately 48 to 72 hours.
- Strong historical evidence for blood-pressure reduction and cardiovascular risk reduction.
- Low generic acquisition cost.
- Greater electrolyte and metabolic monitoring requirements than some alternatives.
- Increasing use in patients with chronic kidney disease and resistant hypertension.
The drug’s main commercial constraint is that its clinical differentiation has not translated into branded pricing. Most prescriptions are filled as generic tablets, and the active ingredient is widely available from multiple manufacturers.
| Market factor |
Effect on chlorthalidone |
| Large hypertension population |
Supports durable prescription demand |
| Generic status |
Limits price and margin expansion |
| Long duration of action |
Supports clinical preference in selected patients |
| Electrolyte abnormalities |
Restricts use in some patients |
| Multiple manufacturers |
Increases supply competition |
| No current exclusivity barrier |
Permits broad generic substitution |
| Limited product innovation |
Reduces investment in premium formulations |
The market is therefore volume-stable and value-constrained. Chlorthalidone can retain or increase prescription share without producing substantial revenue growth.
How large is the chlorthalidone market?
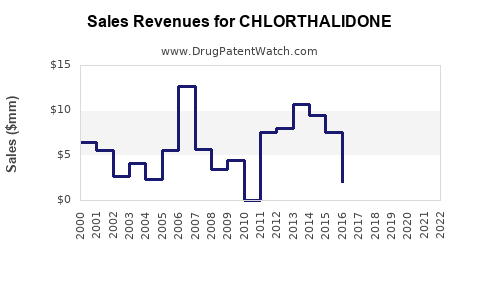
There is no authoritative, publicly reported global market value for chlorthalidone as a standalone product. Commercial datasets generally aggregate the drug within cardiovascular generics or diuretic categories, while manufacturers do not identify chlorthalidone revenue in public financial filings.
The relevant market is better measured through prescription volume and competitive share:
- Generic hypertension therapy has a large and recurring patient base.
- Chlorthalidone is prescribed less frequently than hydrochlorothiazide but has a higher clinical profile in certain guideline and specialist settings.
- Most revenue is captured by low-cost generic manufacturers, wholesalers, pharmacies, and government payers.
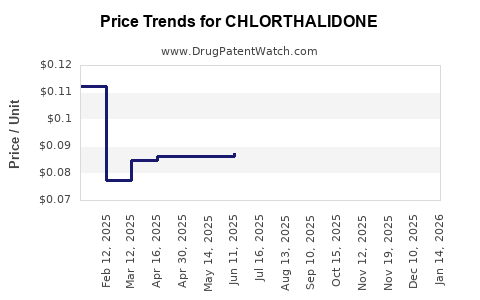
- Average selling prices are exposed to generic competition and reimbursement compression.
The addressable patient population includes adults with primary hypertension, patients requiring combination therapy, and selected patients with resistant hypertension or chronic kidney disease. The total hypertension market is large, but only a fraction of that market uses chlorthalidone.
The product’s economic value is greater to payers than to manufacturers. A low acquisition price can reduce treatment costs, but the drug’s long half-life and electrolyte effects can increase laboratory monitoring and adverse-event management costs in some patients.
What is the financial trajectory for chlorthalidone?
Chlorthalidone’s financial trajectory is best characterized as stable demand with low unit economics and limited upside.
Revenue outlook
Standalone chlorthalidone revenue is not separately disclosed by the major generic companies. Teva Pharmaceutical Industries, Viatris, Hikma Pharmaceuticals, and other generic manufacturers report broad business segments rather than product-level sales for mature oral antihypertensives.
The likely revenue pattern is:
| Period |
Expected commercial trend |
| Historical period |
Declining branded value as products moved to generic status |
| Current market |
Stable or gradually increasing volume |
| Near term |
Low price growth and continued generic competition |
| Medium term |
Limited nominal revenue growth, mainly from population growth and utilization |
| Long term |
Potential volume erosion from alternative antihypertensives and fixed-dose combinations |
Chlorthalidone is unlikely to generate material revenue expansion without a new delivery system, combination product, branded indication, or major clinical positioning change. None of those factors currently creates a clear premium-price pathway.
Margin profile
Generic chlorthalidone margins depend on manufacturing scale, active pharmaceutical ingredient sourcing, regulatory compliance, and supply reliability. Tablets are relatively simple to manufacture, which lowers technical barriers. Margins can narrow when several suppliers compete for the same pharmacy and wholesaler contracts.
The strongest economics generally accrue to suppliers that have:
- Reliable U.S. regulatory approval;
- Multi-source API procurement;
- High-volume tablet manufacturing;
- Stable wholesaler relationships;
- Adequate inventory during supply disruptions;
- Low-cost packaging and distribution.
Small-dose tablets can create operational complexity because of content uniformity, low active-ingredient loading, and multiple strength requirements. Those factors affect manufacturing efficiency but do not create a durable patent moat.
What patents protect chlorthalidone?
No meaningful composition-of-matter patent protection remains for chlorthalidone. The active ingredient was developed decades ago, and any original compound or early-use patents expired long before the current generic market.
The relevant intellectual-property position is therefore limited to potential:
- Product-specific formulation patents;
- Manufacturing-process patents;
- Crystalline or salt-form patents, where applicable;
- Combination-product patents;
- Method-of-use patents;
- Packaging or device claims.
These categories have limited commercial importance for standard immediate-release chlorthalidone tablets.
| IP category |
Current commercial relevance |
| Original molecule patent |
Expired |
| Standard tablet formulation |
Generally unprotected by enforceable exclusivity |
| Manufacturing process |
May exist but is usually nonblocking |
| Combination products |
Potentially relevant if separately patented |
| Method of use |
Could affect a narrow indication, but no major barrier is established |
| Delivery device |
Not relevant to conventional tablets |
Patent protection should therefore be analyzed at the level of a specific manufacturer, dosage form, and approved product rather than at the active-ingredient level.
What is the Orange Book status of chlorthalidone?
The FDA Orange Book identifies approved drug products and relevant patent and exclusivity information. Standard generic chlorthalidone tablets do not have a practical Orange Book patent barrier comparable to newer branded drugs.
The commercial implications are direct:
- ANDA applicants can generally seek approval without waiting for a branded patent term to expire.
- Paragraph IV litigation is not a central market feature for conventional chlorthalidone tablets.
- Generic substitution is broadly available where state pharmacy rules and payer policies permit it.
- No remaining new-drug exclusivity is expected to protect the mature active ingredient.
The branded product history includes Thalitone and other historical chlorthalidone products. Their commercial importance is limited relative to generic supply. FDA approval status and marketing status can change by manufacturer, so an individual product’s listing must be distinguished from the active ingredient’s broader generic availability. FDA Drugs@FDA and the Orange Book remain the controlling sources for product-specific status.[1][2]
When does chlorthalidone lose exclusivity?
Chlorthalidone lost practical exclusivity decades ago. It is not comparable to a recently approved small molecule with five-year new chemical entity exclusivity, three-year clinical-investigation exclusivity, or an active patent estate.
No meaningful exclusivity timeline remains for the conventional active ingredient. The relevant commercial timeline is instead determined by:
- Generic approval and market entry.
- Number of approved manufacturers.
- Wholesaler and payer contracting.
- API availability.
- Reimbursement rates.
- Prescriber preference relative to hydrochlorothiazide and indapamide.
This creates a mature-market profile in which competition affects price immediately and product differentiation depends primarily on clinical evidence.
Which companies are challenging or competing with chlorthalidone?
Chlorthalidone faces competition from both manufacturers and substitute therapies.
Generic manufacturers
Multiple manufacturers have marketed chlorthalidone tablets or have held approvals for the product. The competitive field can include large integrated generic companies, specialty generic suppliers, and contract manufacturers. Product availability differs by strength, dosage form, and market period.
Because the product is generic, the key competitive question is not whether one company controls the molecule. It is whether suppliers can maintain reliable inventory at commercially viable prices.
Therapeutic competitors
The primary therapeutic competitors are:
- Hydrochlorothiazide;
- Indapamide;
- Amlodipine;
- ACE inhibitors;
- Angiotensin receptor blockers;
- Loop diuretics for selected patients;
- Fixed-dose combinations containing a thiazide or thiazide-like diuretic.
Hydrochlorothiazide remains widely used because of historical prescribing familiarity and extensive combination-product availability. Chlorthalidone has a longer duration of action and stronger evidence in some cardiovascular-outcome discussions, but its use can be limited by hypokalemia, hyponatremia, hyperuricemia, and renal-function concerns.
The 2017 American College of Cardiology and American Heart Association hypertension guideline identifies thiazide diuretics, including chlorthalidone, as first-line antihypertensive options.[3]
How strong is the chlorthalidone patent estate?
The patent estate is weak as a commercial defense. Chlorthalidone has no credible molecule-level barrier to generic entry, and conventional tablets have limited opportunity for enforceable differentiation.
Patent strength can still vary for a particular product if a company develops:
- An extended-release tablet;
- A co-formulation with another antihypertensive;
- A formulation designed to reduce electrolyte abnormalities;
- A novel dosing regimen;
- A new indication supported by clinical data.
Those claims would face validity, written-description, obviousness, and enablement risks. A formulation patent would need to provide a practical clinical or manufacturing advantage to justify investment because standard chlorthalidone tablets are inexpensive and widely substitutable.
What clinical developments could affect demand?
The strongest demand catalyst is clinical adoption in patients with resistant hypertension, chronic kidney disease, or difficult-to-control blood pressure.
The CLICK trial evaluated chlorthalidone in patients with stage 4 chronic kidney disease and uncontrolled hypertension. The study reported clinically meaningful reductions in ambulatory blood pressure, while also documenting adverse effects such as hypokalemia, reversible increases in serum creatinine, hyperuricemia, dizziness, and hyperglycemia.[4]
That evidence can support specialist prescribing, but it does not create a premium market. The likely effect is incremental volume growth in selected patients rather than a broad change in pricing.
Clinical adoption will depend on how prescribers balance:
- Blood-pressure efficacy;
- Cardiovascular outcome evidence;
- Kidney function;
- Electrolyte monitoring;
- Tolerability;
- Simplicity of once-daily therapy;
- Availability of alternative agents.
What generic entry risks exist for chlorthalidone?
Generic entry risk is already realized rather than prospective. Conventional chlorthalidone tablets have broad generic availability and no apparent patent-based launch restriction.
The principal risks to manufacturers are commercial:
- Further price erosion;
- Loss of formulary position;
- Supplier consolidation;
- API shortages;
- Manufacturing deviations;
- Product discontinuations;
- Low profitability at lower-volume strengths.
The principal risk to branded or reformulated products would be rapid substitution once an ANDA is approved, particularly if the reformulation does not demonstrate a clear clinical advantage.
What patent litigation and Paragraph IV challenges affect chlorthalidone?
There is no major, widely recognized Paragraph IV litigation campaign centered on standard chlorthalidone tablets. That reflects the product’s age, generic status, and absence of a commercially significant patent barrier.
Any future litigation would more likely involve a branded reformulation, fixed-dose combination, or narrow method-of-use claim than the conventional active ingredient. Such litigation would have limited effect on the broader chlorthalidone market unless the challenged product captured substantial prescription volume.
What licensing deals affect chlorthalidone?
No major, publicly disclosed licensing transaction is associated with the conventional chlorthalidone tablet market. Mature generic products are commonly supplied through ordinary manufacturing, distribution, and private-label arrangements rather than high-value intellectual-property licenses.
Licensing could become relevant if a company commercialized a proprietary formulation, combination product, or specialty indication. There is no established evidence that such a transaction currently changes the market structure.
How does chlorthalidone compare with hydrochlorothiazide?
| Attribute |
Chlorthalidone |
Hydrochlorothiazide |
| Drug class |
Thiazide-like diuretic |
Thiazide diuretic |
| Duration |
Longer |
Shorter |
| Generic availability |
Broad |
Very broad |
| Pricing power |
Minimal |
Minimal |
| Guideline role |
First-line option |
First-line option |
| Combination products |
Available but less extensive |
Extensive |
| Monitoring |
Electrolytes and renal function |
Electrolytes and renal function |
| Commercial outlook |
Stable niche volume |
Larger overall volume |
| Patent barrier |
None of practical importance |
None of practical importance |
Hydrochlorothiazide has greater commercial reach because it is embedded in numerous fixed-dose combinations. Chlorthalidone has a stronger position where prescribers value prolonged blood-pressure control or evidence from outcome studies.
Key Takeaways
- Chlorthalidone is a mature generic antihypertensive with no meaningful remaining molecule-level exclusivity.
- Its market is volume-driven, not price-driven.
- Public companies generally do not report standalone chlorthalidone revenue.
- Revenue is likely stable to modestly growing in aggregate, while per-unit pricing remains under pressure.
- The main competitors are hydrochlorothiazide, indapamide, calcium-channel blockers, ACE inhibitors, ARBs, and fixed-dose combinations.
- Standard tablets face no material Orange Book or Paragraph IV barrier.
- Patent value would arise mainly from a novel formulation, combination, dosing regimen, or indication.
- The CLICK trial supports use in selected chronic kidney disease patients but also highlights electrolyte and renal-monitoring risks.
- Manufacturing reliability and reimbursement access matter more than patent ownership.
- The product has low strategic value as a standalone branded asset but can retain predictable generic demand.
FAQs
Is chlorthalidone still commercially profitable?
It can be profitable for efficient generic manufacturers, but low pricing and competition limit margins. Profitability depends on manufacturing scale, supply reliability, and contracting rather than exclusivity.
Is chlorthalidone included in fixed-dose combination products?
Yes. Chlorthalidone has been used in combination products, although hydrochlorothiazide is more widely represented in commercial fixed-dose antihypertensive combinations.
Can a company obtain new exclusivity for chlorthalidone?
Potentially, but only for a qualifying new formulation, indication, or clinical-use product. The existing active ingredient does not qualify for new chemical entity exclusivity.
Does chlorthalidone have biosimilar competition?
No. Chlorthalidone is a chemically synthesized small molecule, so competition proceeds through generic drug pathways rather than FDA biosimilar regulation.
What is the largest commercial threat to chlorthalidone?
The largest threat is substitution by other low-cost antihypertensives, particularly hydrochlorothiazide-containing combinations, rather than patent expiration or Paragraph IV litigation.
References
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/orange-book-data-files
-
U.S. Food and Drug Administration. (n.d.). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
-
Whelton, P. K., Carey, R. M., Aronow, W. S., Casey, D. E., Collins, K. J., Dennison Himmelfarb, C., DePalma, S. M., Gidding, S., Jamerson, K. A., Jones, D. W., MacLaughlin, E. J., Muntner, P., Ovbiagele, B., Smith, S. C., Spencer, C. C., Stafford, R. S., Taler, S. J., Thomas, R. J., Williams, K. A., Williamson, J. D., & Wright, J. T. (2018). 2017 ACC/AHA guideline for the prevention, detection, evaluation, and management of high blood pressure in adults. Hypertension, 71(6), e13-e115. https://doi.org/10.1161/HYP.0000000000000065
-
Agarwal, R., Sinha, A. D., Cramer, A. E., Balmes-Fenwick, M., Dickinson, J. H., O’Neill, W. C., Veverka, A., & Weir, M. R. (2021). Chlorthalidone for hypertension in advanced chronic kidney disease. New England Journal of Medicine, 385(27), 2507-2519. https://doi.org/10.1056/NEJMoa2110730