Last updated: September 27, 2026
Atenolol is a mature, multisource generic beta blocker with no meaningful U.S. patent or regulatory exclusivity barrier. Its commercial profile is defined by low acquisition cost, broad manufacturer competition, stable demand in hypertension and cardiovascular care, and long-term substitution by newer beta blockers and other antihypertensive classes. Financial growth is unlikely to come from price expansion. The principal opportunities are volume contracts, supply reliability, combination products, emerging-market distribution, and manufacturing efficiency.
What is the current FDA status of atenolol?
Atenolol is an FDA-approved prescription beta-1 selective adrenergic blocker marketed primarily as oral tablets in 25 mg, 50 mg, and 100 mg strengths. It is approved for hypertension and long-term management of angina pectoris. U.S. labeling also recognizes use in acute myocardial infarction in appropriate clinical settings, although practice patterns have evolved since the original approval period.[1]
| Attribute |
Atenolol status |
| Active ingredient |
Atenolol |
| Drug class |
Beta-1 selective beta blocker |
| U.S. dosage forms |
Primarily oral tablets |
| Common strengths |
25 mg, 50 mg, 100 mg |
| Prescription status |
Prescription only |
| Reference product |
Tenormin |
| Originator |
ICI Pharmaceuticals, later associated with AstraZeneca |
| FDA pathway for current suppliers |
Abbreviated New Drug Application, or ANDA |
| Current market structure |
Multisource generic |
| Biosimilar exposure |
None; atenolol is a small-molecule drug |
| Primary therapeutic uses |
Hypertension, angina, cardiovascular risk management |
DailyMed records multiple atenolol tablet labels from generic manufacturers. Product availability and label status can change as manufacturers discontinue or reactivate individual National Drug Codes.[2]
When did atenolol lose patent and market exclusivity?
Atenolol lost practical U.S. market exclusivity decades ago. Generic competition began in the 1990s after expiration of the relevant originator patent and regulatory exclusivity period. The product is now far beyond the commercial life of its original protection.
The principal commercial implication is that an entrant does not need to wait for a future patent expiration date. Generic manufacturers can compete through ANDA approval, manufacturing capacity, procurement access, and state or health-plan formulary positioning.
| Exclusivity category |
Atenolol position |
| New chemical entity exclusivity |
Expired |
| Original compound patent protection |
Expired |
| Pediatric exclusivity |
No current commercial relevance |
| Orphan exclusivity |
None identified for the core product |
| New formulation exclusivity |
No broad market barrier identified |
| U.S. patent cliff |
Historical, not upcoming |
| Current barrier to entry |
FDA approval, quality compliance, supply economics, and contracting |
The original Tenormin franchise is therefore not protected by a live exclusivity strategy comparable to newer cardiovascular drugs. The relevant commercial question is supply participation, not patent timing.
What patents protect atenolol in the United States?
No active U.S. patent estate is generally associated with the basic atenolol tablet opportunity. The originator compound, the conventional tablet formulation, and the principal method-of-use claims are historical assets rather than current barriers to generic entry.
The relevant patent categories are:
| Patent category |
Commercial status |
| Atenolol compound patent |
Expired |
| Conventional tablet formulation |
No meaningful current blocking protection |
| Hypertension method of use |
Expired or commercially non-blocking |
| Angina method of use |
Expired or commercially non-blocking |
| Manufacturing process patents |
Any surviving rights would be unlikely to block standard generic tablet production |
| Combination-product patents |
Product-specific and generally not relevant to standalone atenolol |
| Device or delivery patents |
Limited relevance because the main product is an oral tablet |
A manufacturer still must avoid infringement of any narrow, later-filed patent directed to a specific formulation, process, dosage regimen, or combination product. Those rights would not normally prevent approval and sale of ordinary atenolol tablets unless they were listed or otherwise enforceable against the proposed product.
What is the Orange Book status of atenolol?
The FDA Orange Book identifies approved drug products and, where applicable, listed patents and exclusivity. Atenolol is represented through legacy reference-product and generic approvals, but the ordinary tablet market does not have a current Orange Book patent barrier that would delay standard generic entry.[3]
The reference product, Tenormin, is no longer the commercial center of the market. Generic applicants typically rely on the reference listed drug for bioequivalence and labeling purposes. A new applicant seeking to market conventional atenolol tablets would generally pursue an ANDA rather than a 505(b)(2) application.
Are there Paragraph IV challenges for atenolol?
Paragraph IV litigation is not a meaningful current feature of the standard atenolol market. Paragraph IV certifications are used when an ANDA applicant asserts that a listed patent is invalid, unenforceable, or not infringed. Because the core atenolol tablet opportunity is long off-patent, a contemporary Paragraph IV campaign would have little strategic value unless directed to a narrow, later-listed product or formulation.
The commercial exposure is therefore different from that of a recently approved drug. Atenolol has no material current litigation-driven launch date, first-filer premium, or 180-day exclusivity event that would reshape the market.
How many manufacturers sell atenolol?
The U.S. market has historically included numerous ANDA holders and contract manufacturers. The number of active suppliers varies by dosage strength, packaging configuration, and time period. Some approved products may be discontinued, while others remain listed but have limited commercial distribution.
The competitive field generally includes:
- Large generic companies with broad cardiovascular portfolios.
- Regional suppliers focused on retail, institutional, or government contracts.
- Contract manufacturers supplying private-label products.
- Wholesaler and pharmacy-chain sources using approved third-party manufacturers.
The number of approved applications is less important than the number of dependable commercial suppliers. Atenolol is inexpensive, so buyers often consolidate purchasing with vendors that can provide stable fill rates, acceptable quality metrics, and competitive contract terms.
What formulations are protected by atenolol patents?
The commercially important product is the immediate-release oral tablet. It is generally available in 25 mg, 50 mg, and 100 mg strengths. No broadly adopted extended-release or specialty delivery format has displaced the conventional tablet.
Tablet formulation economics
The tablet has several commercial advantages:
- Simple manufacturing process.
- Low active pharmaceutical ingredient cost.
- Long-established analytical methods.
- Straightforward stability profile.
- No complex device or sterile manufacturing requirement.
- Low regulatory complexity relative to modified-release products.
These characteristics reduce technical barriers and support a large generic supplier base. They also reduce the probability of durable price premiums.
Combination products
Atenolol has been studied and marketed in combination with other cardiovascular agents in various jurisdictions. Combination products can create separate regulatory and patent considerations, but they do not materially protect the standalone atenolol tablet market. An applicant seeking a combination product may face different clinical, labeling, and intellectual-property requirements than an applicant for single-ingredient atenolol.
What is the market demand for atenolol?
Atenolol demand is mature and primarily driven by chronic cardiovascular treatment. Its demand base includes patients with hypertension, angina, selected arrhythmias, and other indications in which beta-blockade is clinically appropriate.
Demand is supported by:
- Large installed patient populations.
- Low out-of-pocket cost.
- Familiarity among prescribers.
- Broad generic availability.
- Use in health systems that prioritize low-cost essential medicines.
Demand is constrained by:
- Greater use of guideline-preferred therapies for uncomplicated hypertension.
- Competition from metoprolol, bisoprolol, carvedilol, nebivolol, and other beta blockers.
- Increased use of ACE inhibitors, angiotensin receptor blockers, calcium-channel blockers, and thiazide-type diuretics.
- Concerns about atenolol’s pharmacokinetic profile and central nervous system penetration relative to some alternatives.
- Clinical preference for other agents in heart failure, post-myocardial infarction care, or rate control depending on the patient.
Atenolol remains commercially relevant, but it is generally a maintenance product rather than a growth product.
How does atenolol compare with competing beta blockers?
| Drug |
Competitive position |
Main commercial advantage |
Main limitation |
| Atenolol |
Mature generic |
Low price and established supply |
Older clinical profile and declining preference in some guidelines |
| Metoprolol tartrate |
High-volume generic |
Broad cardiovascular use and multiple strengths |
Immediate-release dosing can require multiple daily doses |
| Metoprolol succinate |
High-value generic relative to atenolol |
Extended-release profile and heart-failure use |
More formulation-specific competition |
| Bisoprolol |
Established generic |
Beta-1 selectivity and chronic cardiovascular use |
Smaller volume in some markets |
| Carvedilol |
Established generic |
Heart-failure and hypertension positioning |
Nonselective beta and alpha blockade; different tolerability profile |
| Nebivolol |
Higher-priced generic or branded-generic segment |
Selectivity and nitric-oxide-related positioning |
Higher price and narrower cost advantage |
| Propranolol |
Mature generic |
Broad indications and low price |
Nonselective profile and central nervous system effects |
Atenolol competes most directly with metoprolol and bisoprolol in chronic beta-blocker treatment. It competes indirectly with non-beta-blocker antihypertensive classes, which account for a larger share of first-line hypertension prescribing.
What generic entry risks exist for atenolol?
Generic entry risk is high because technical and legal barriers are low. The principal risk to an existing supplier is not a sudden patent-triggered launch but gradual erosion from additional approved or reactivated suppliers.
| Risk factor |
Assessment |
| Patent blocking risk |
Low |
| FDA approval complexity |
Low to moderate |
| Manufacturing complexity |
Low |
| API supply risk |
Moderate, depending on supplier concentration |
| Price erosion risk |
High |
| Substitution risk |
Moderate to high |
| Hospital purchasing pressure |
High |
| Shortage risk |
Episodic rather than structural |
| Long-term volume growth |
Low |
A new entrant can obtain share if it has reliable supply, competitive pricing, acceptable packaging, and access to wholesalers or institutional contracts. Because the product is low margin, a small number of manufacturing failures or recalls can materially damage an individual supplier’s economics.
What patent litigation affects atenolol?
No major current U.S. patent litigation is generally associated with the ordinary atenolol tablet market. Historical litigation would have centered on generic entry after the originator’s patent period, but that phase ended long ago.
Current legal exposure is more likely to involve:
- Product liability claims.
- Manufacturing and quality disputes.
- Contracting or supply disagreements.
- False advertising or labeling issues.
- Regulatory enforcement involving manufacturing practices.
- Patent disputes involving a combination product or specialized formulation.
The absence of active core-product litigation removes a major source of launch uncertainty. It also eliminates the opportunity for a litigation-based first entrant to capture a temporary market advantage.
What licensing deals affect atenolol?
Atenolol is unlikely to generate significant current licensing activity for the standalone tablet. The active ingredient is generic, widely available, and inexpensive. Commercial agreements are more likely to involve:
- Contract manufacturing.
- Private-label supply.
- Distribution rights in specific countries.
- API sourcing.
- Hospital or government procurement.
- Portfolio transfers involving generic products.
The economic value of a licensing deal is determined by volume, manufacturing cost, regulatory status, and distribution access rather than by exclusivity over the molecule.
What is the financial trajectory for atenolol?
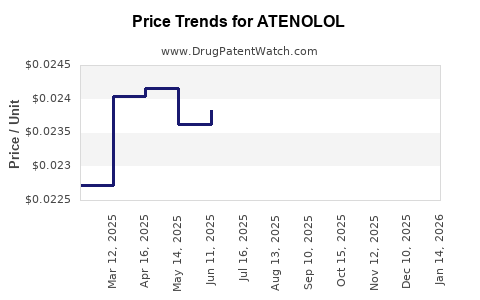
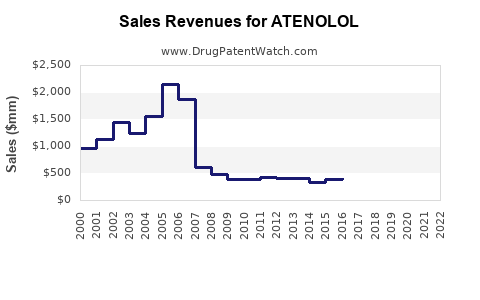
Atenolol’s financial trajectory is structurally mature. Aggregate utilization can remain substantial while revenue declines or stays flat because generic prices fall over time. Public companies generally do not report atenolol revenue as a separate line item, so a precise drug-level revenue forecast cannot be derived from issuer filings alone.
| Financial driver |
Expected direction |
| Unit demand |
Stable to gradually declining in developed markets |
| Net price |
Downward pressure |
| Gross margin |
Low and potentially compressing |
| Revenue concentration |
Distributed across multiple suppliers |
| Pricing power |
Minimal |
| Commercial life |
Long tail |
| Growth opportunity |
Emerging markets, tenders, supply reliability, combinations |
| Investor relevance |
Portfolio contribution rather than standalone franchise value |
Revenue exposure by business model
For a large generic manufacturer, atenolol may contribute recurring volume but limited strategic value. For a smaller supplier, a government tender or pharmacy contract can produce material revenue concentration even though the product has low margins. For an API producer, economics depend on manufacturing scale and customer concentration rather than branded demand.
The product may become financially attractive during temporary supply disruptions. A supplier with available inventory can obtain incremental volume when competitors experience quality problems, plant shutdowns, or procurement failures. Such gains are usually episodic and do not create durable pricing power.
What is the global market outlook for atenolol?
Atenolol remains relevant in countries where low-cost generic treatment is prioritized and established prescribing habits remain strong. Its position is stronger in price-sensitive markets than in formularies that favor newer beta blockers or alternative antihypertensive classes.
Geographic coverage
The product has broad international regulatory history and is marketed in multiple regions under generic names and legacy brand names. Market conditions differ:
- United States: mature generic market with low prices and strong contracting pressure.
- Europe: genericized market with national reimbursement controls.
- India: significant domestic production and branded-generic competition.
- Latin America: variable regulatory and pricing conditions.
- Emerging markets: potential volume demand, but lower per-unit revenue and tender-driven pricing.
International growth depends on local registration, pharmacopoeial compliance, supply-chain execution, and reimbursement access. Patent protection is generally not the limiting factor.
How strong is the atenolol patent estate?
The patent estate is weak as a commercial defense but irrelevant to current generic availability. Atenolol has no meaningful remaining composition-of-matter protection in the principal markets. Its conventional formulation is technically simple, and manufacturing know-how is widely distributed.
| Patent-strength dimension |
Rating |
| Core molecule protection |
None of current commercial significance |
| Tablet formulation protection |
Weak |
| Method-of-use protection |
Weak |
| Manufacturing barriers |
Low |
| Regulatory barriers |
Low to moderate |
| Supply-chain barriers |
Moderate |
| Brand differentiation |
Low |
| Defensibility of premium pricing |
Very low |
The stronger assets in this market are operational: quality systems, dependable API sourcing, low conversion cost, and procurement relationships.
What are the likely generic launch scenarios?
Because atenolol is already generic, the relevant scenarios concern new supplier entry, re-entry, and market-share shifts.
Base case
Existing suppliers maintain broad availability while prices remain low. Demand declines gradually in developed markets but persists through chronic use and institutional procurement.
Upside case for a supplier
A manufacturer gains share through a competitor shortage, a successful tender, vertically integrated API supply, or reliable distribution in an underserved market. Revenue increases through volume rather than price.
Downside case
Additional suppliers enter, reimbursement prices decline, or demand shifts toward metoprolol, bisoprolol, and non-beta-blocker therapies. Low margins make the product vulnerable to discontinuation if manufacturing costs rise.
What regulatory and manufacturing barriers remain?
Atenolol has low product-development complexity but still requires compliance with FDA current good manufacturing practices, validated analytical methods, bioequivalence standards, stability requirements, and approved labeling.[4]
The main manufacturing risks are:
- API impurity control.
- Supplier qualification.
- Batch consistency.
- Packaging and serialization compliance.
- Facility inspection findings.
- Recalls or warning letters.
- Inadequate inventory planning.
- Dependence on a small number of API sources.
For a low-priced drug, remediation costs can exceed the expected profit from continued supply. Manufacturers therefore tend to rationalize portfolios when volumes fall below efficient production levels.
Key Takeaways
- Atenolol is a mature, multisource generic beta blocker with no meaningful current U.S. patent barrier.
- Core composition, tablet, and method-of-use protection are historical and do not support premium pricing.
- The FDA market is driven by ANDA-approved generic tablets, mainly in 25 mg, 50 mg, and 100 mg strengths.
- Paragraph IV litigation, settlement agreements, and launch-date disputes are not material features of the current standalone product market.
- Revenue is difficult to isolate because manufacturers report atenolol within broad generic portfolios.
- Financial performance depends on volume, tenders, contract access, API costs, and supply reliability.
- Demand is stable but structurally mature, with competitive pressure from metoprolol, bisoprolol, carvedilol, nebivolol, and non-beta-blocker antihypertensives.
- The main commercial risks are price erosion, supplier rationalization, clinical substitution, and manufacturing disruption.
- The most defensible assets are operational rather than intellectual property-based.
FAQs
Is atenolol still profitable for generic manufacturers?
It can be profitable at scale, but margins are generally thin. Profitability depends on manufacturing efficiency, procurement volume, API cost, and the ability to avoid quality-related disruptions.
Does atenolol have pediatric exclusivity?
No current pediatric exclusivity period creates a commercial barrier for ordinary atenolol tablets. Any historical regulatory exclusivity is no longer relevant to market entry.
Can a company launch atenolol without a Paragraph IV certification?
Yes. For a conventional product with no relevant listed patent blocking approval, an ANDA applicant can use the applicable certification pathway without challenging an active patent.
Is atenolol included in essential-medicines procurement?
Atenolol may be included in national, institutional, or hospital formularies, but procurement status varies by jurisdiction. Inclusion generally supports volume, not high pricing.
Does atenolol have biosimilar competition?
No. Atenolol is a chemically synthesized small molecule. Competition comes from generic-drug manufacturers, not biosimilar developers.
References
-
U.S. Food and Drug Administration. (2023). Tenormin (atenolol) prescribing information. FDA.
-
National Library of Medicine. (2024). DailyMed: Atenolol tablet labeling. U.S. National Library of Medicine.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Food and Drug Administration. (2024). Abbreviated new drug application submissions: Product-specific guidance and bioequivalence requirements. FDA.