Last updated: September 24, 2026
Zithromax, Pfizer’s brand for azithromycin, is a mature macrolide antibiotic with limited remaining brand economics and extensive generic competition. U.S. market exclusivity ended in the mid-2000s, while Pfizer retains value through brand recognition, established clinical use, and selected formulations. Most azithromycin volume now flows through generic manufacturers rather than Pfizer.
The commercial trajectory has four phases:
- Rapid growth after U.S. approval in 1991.
- Peak branded sales before generic entry.
- Sharp erosion after azithromycin generics launched.
- Long-term commoditization, with intermittent demand increases during respiratory-disease surges.
Azithromycin remains FDA-approved for several bacterial infections, including community-acquired pneumonia, acute bacterial exacerbations of chronic bronchitis, acute bacterial sinusitis, pharyngitis or tonsillitis, uncomplicated skin infections, urethritis and cervicitis, and selected sexually transmitted infections.[1]
What is Zithromax and how does azithromycin compete in the antibiotic market?
Zithromax is the original branded version of azithromycin, a semisynthetic azalide related to the macrolide antibiotic erythromycin. Its pharmacokinetic profile allows shorter treatment courses than many older antibiotics, which supported rapid adoption in outpatient care.
| Attribute |
Zithromax profile |
| Active ingredient |
Azithromycin |
| Drug class |
Macrolide, azalide antibiotic |
| Original U.S. sponsor |
Pfizer and predecessor companies |
| Initial U.S. approval |
1991 |
| Main dosage forms |
Tablets, capsules, oral suspension, injection |
| Common outpatient use |
Respiratory, skin, ear, and selected sexually transmitted infections |
| Primary competitors |
Generic azithromycin, clarithromycin, erythromycin, doxycycline, amoxicillin-based regimens |
| Current market structure |
Predominantly generic |
| Biosimilar exposure |
None; azithromycin is a small-molecule drug |
Zithromax’s commercial advantage historically came from once-daily dosing, short treatment durations, broad prescribing familiarity, and pediatric liquid formulations. The commercial disadvantage is that azithromycin is now widely available from multiple generic manufacturers at low prices.
When did Zithromax lose exclusivity and when did generic azithromycin launch?
U.S. brand protection ended in the mid-2000s. The core commercial patent estate did not maintain a long exclusivity period after the original 1991 approval.
| Event |
Timing |
Commercial effect |
| FDA approval of Zithromax |
1991 |
Start of U.S. branded commercialization |
| Pediatric liquid and tablet expansion |
1990s |
Broadened outpatient and pediatric use |
| Zmax extended-release suspension approval |
2005 |
Added a differentiated formulation shortly before broad generic erosion |
| Core U.S. patent protection |
Mid-2000s |
Expired or became commercially ineffective |
| Generic azithromycin availability |
2005-2006 period |
Rapid price and market-share pressure |
| Mature generic market |
2010s onward |
Brand sales became a small portion of total azithromycin economics |
The FDA’s Orange Book is the principal source for approved drug products, patent listings, and regulatory exclusivity information.[2] For a mature product such as Zithromax, current commercial protection depends less on the original active-ingredient patent and more on whether any later formulation, method-of-use, or device patent remains listed and enforceable.
What patents protect Zithromax and how strong is the patent estate?
The historic Zithromax patent estate protected azithromycin chemistry, pharmaceutical compositions, and selected formulations. The estate is no longer commercially strong in the United States because generic azithromycin has been available for many years.
Core compound and composition patents
Azithromycin was protected through patents covering the azalide compound and related pharmaceutical compositions. The original patent term ran into the early 2000s, with later statutory adjustments, pediatric exclusivity, and product-specific patent positions affecting the practical generic-entry date.
The core patent estate had three commercial limitations:
- The patents were filed decades ago and had finite patent terms.
- Azithromycin is a small molecule with a relatively accessible manufacturing pathway.
- Later formulation claims did not prevent broad generic substitution across all dosage forms.
Formulation patents
Zithromax was marketed in tablets, capsules, oral suspensions, injectable products, and the Zmax extended-release suspension. Formulation protection could delay competition for a specific dosage form, but it did not necessarily prevent generic tablets, capsules, or conventional oral suspension from entering the market.
Zmax had a more differentiated formulation and dosing profile. Its commercial value was limited by the availability of conventional azithromycin products and by the fact that prescribers could substitute alternative dosage forms for many indications.
Method-of-use patents
Method-of-use claims historically covered treatment of specified bacterial infections. These claims created potential Paragraph IV litigation exposure, but they did not create durable protection across all azithromycin uses. Generic applicants could also rely on section viii statements for indications not covered by valid patent claims, subject to labeling restrictions.
Current patent strength
| Patent category |
Historic relevance |
Current U.S. strength |
| Azithromycin active-ingredient patents |
High |
Expired |
| Basic composition patents |
High |
Expired or commercially ineffective |
| Tablet and capsule formulations |
Moderate |
Largely expired |
| Oral suspension formulations |
Moderate |
Limited practical protection |
| Zmax extended-release formulation |
Moderate to high |
Legacy protection; limited current economic impact |
| Method-of-use claims |
Indication-specific |
Narrow and generally low commercial leverage |
| Manufacturing patents |
Potentially relevant |
Not a broad barrier to generic supply |
The Zithromax estate should be classified as a weak current patent estate. Its value is primarily historical, not a basis for meaningful U.S. exclusivity.
What is the Orange Book status of Zithromax?
The FDA Orange Book identifies Zithromax as a legacy approved product with multiple azithromycin dosage forms and strengths. The practical Orange Book question is not whether Zithromax has an approved NDA, but whether active listed patents or exclusivity periods prevent an ANDA applicant from receiving final approval.
For a mature product, the relevant analysis covers:
- The NDA and dosage-form status.
- Any currently listed patents.
- Patent expiration dates.
- Regulatory exclusivity.
- Whether generic labeling can omit protected indications.
- Whether the reference product has been discontinued, withdrawn, or retained only as a listed reference.
FDA regulatory status does not equal commercial exclusivity. Zithromax can remain FDA-approved after its patent estate has lost economic force. Approved generic azithromycin products can compete even while Pfizer’s brand remains on the market.
Which companies challenged Zithromax patents, and what happened to Paragraph IV risk?
Generic competition came from multiple large and specialty pharmaceutical manufacturers after the relevant patent barriers weakened. Generic azithromycin has been marketed by companies including Teva, Sandoz, Mylan, Dr. Reddy’s, Lupin, Apotex, and other suppliers, depending on dosage form and market period.
Paragraph IV challenges were most important before generic launch. An ANDA applicant could certify that a listed patent was invalid, unenforceable, or would not be infringed. A Paragraph IV notice could trigger patent litigation and a potential 30-month stay of FDA approval under the Hatch-Waxman framework.[3]
For Zithromax, the litigation risk was time-limited:
- Core azithromycin claims were approaching the end of their statutory term.
- Generic applicants had strong commercial incentives to challenge remaining claims.
- Multiple dosage forms created opportunities for design-around strategies.
- The presence of narrow formulation claims did not protect the entire azithromycin market.
No current Paragraph IV dispute materially changes the U.S. competitive position of mature azithromycin products.
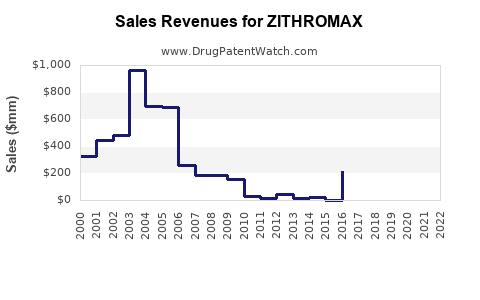
How did Zithromax revenue change after generic entry?
Pfizer does not generally report Zithromax as a separately disclosed current revenue line. The company reports large product categories and selected products, while mature brands may be grouped within established pharmaceutical revenues.[4]
The financial trajectory is therefore best assessed through market structure rather than a current standalone revenue figure.
Commercial trajectory
1991-1999: rapid adoption
Zithromax gained share from older macrolides because of its short course, once-daily dosing, and broad outpatient use. Pediatric and respiratory prescribing supported high prescription volume.
2000-2004: peak branded economics
Before broad generic substitution, Zithromax had the economics of a high-volume branded antibiotic. Revenue was supported by brand pricing, physician familiarity, and extensive use in primary care.
2005-2007: generic erosion
Generic azithromycin entry caused the principal financial break in the product’s trajectory. U.S. branded antibiotic revenue typically declines sharply when pharmacy substitution becomes available, especially where the active ingredient is chemically stable and multiple manufacturers enter.
2008 onward: mature brand phase
Zithromax continued to generate residual sales, but the commercial center of gravity moved to generic azithromycin. Pfizer’s economics shifted from high-margin branded sales toward a smaller legacy-brand contribution.
2020-2022: respiratory-market volatility
Azithromycin prescriptions increased in some markets during the COVID-19 period because of empirical prescribing and combination-treatment practices. Clinical guidelines and randomized evidence did not establish azithromycin as an effective treatment for COVID-19 in the absence of a susceptible bacterial infection.[5] Any temporary volume increase did not restore the product’s pre-generic financial model.
2023 onward: normalization
Demand is driven by ordinary bacterial infection incidence, respiratory seasons, antimicrobial stewardship, pricing, supply availability, and physician prescribing. The market remains generic-led.
What is the revenue exposure for Pfizer?
Zithromax is not a material growth driver for Pfizer relative to its patented medicines, vaccines, and newer specialty products. Its current revenue exposure is limited by:
- Generic substitution.
- Low unit pricing.
- Mature therapeutic competition.
- Lack of meaningful U.S. exclusivity.
- Limited differentiation among oral azithromycin products.
- Antimicrobial stewardship programs that discourage unnecessary prescribing.
The brand can retain niche value in markets where physicians, hospitals, or patients prefer the originator product. That value is unlikely to offset the revenue loss caused by generic competition.
A reasonable investment interpretation is that Zithromax is a legacy cash-flow asset, not a pipeline or lifecycle-growth asset. Its financial contribution depends on residual branded demand, international pricing, supply arrangements, and portfolio accounting rather than on patent-protected sales expansion.
How does Zithromax compare with competing antibiotics?
| Drug or class |
Competitive position versus azithromycin |
Patent and market profile |
| Generic azithromycin |
Direct substitute |
Highly commoditized |
| Clarithromycin |
Same broad macrolide category |
Generic, with lower current commercial differentiation |
| Doxycycline |
Competes in respiratory, dermatologic, and sexually transmitted infections |
Generic; strong clinical substitution in several indications |
| Amoxicillin or amoxicillin-clavulanate |
Major respiratory and ear-infection competitors |
Generic, high-volume, low-cost |
| Fluoroquinolones |
Used selectively because of safety restrictions |
Generic but constrained by stewardship and safety concerns |
| Branded newer antibiotics |
Can compete in resistant or specialized infections |
Higher price, narrower use, potentially stronger exclusivity |
Azithromycin’s principal market strength is convenience and familiarity. Its principal weakness is that those attributes are available through inexpensive generics.
What generic entry risks remain for Zithromax?
United States
Generic entry risk is no longer an emerging risk. It is the established market condition. Further erosion can occur through:
- Additional generic approvals.
- Pharmacy substitution.
- Contracting pressure.
- Price competition among manufacturers.
- Hospital formulary replacement.
- Reduced use for viral respiratory illnesses.
Europe and other markets
Generic entry occurred at different times by jurisdiction, depending on national patent terms, supplementary protection certificates, pediatric extensions, and local regulatory pathways. The brand may retain higher visibility in countries where physician prescribing is less substitution-driven, but geographic protection is generally weak.
Manufacturing and supply barriers
Azithromycin does not have the manufacturing complexity of a biologic or highly specialized injectable. Generic manufacturers can produce the active ingredient and finished dosage forms through established small-molecule processes.
Potential barriers include:
- Active pharmaceutical ingredient qualification.
- Quality-system compliance.
- Bioequivalence requirements.
- Suspension stability.
- Injectable manufacturing controls.
- Supply-chain disruptions.
- Regulatory inspection findings.
These are operational barriers, not durable intellectual-property barriers.
What is the biosimilar risk for Zithromax?
There is no biosimilar risk because Zithromax is a chemically synthesized small-molecule drug. Generic azithromycin is approved through the ANDA pathway, which requires pharmaceutical equivalence and bioequivalence rather than the biologic comparability framework used for biosimilars.[6]
The relevant competitive risk is generic substitution, not biosimilar competition.
What litigation and settlement agreements affect Zithromax?
Historic litigation centered on generic applicants’ challenges to azithromycin patents and formulation claims. The commercial relevance of that litigation declined once core patent protection expired and generic supply became established.
There is no known current litigation or settlement structure that materially restricts broad generic azithromycin competition in the United States. Any assessment of a particular dosage form should review the FDA Orange Book, ANDA approvals, product labeling, and court dockets because litigation can differ between tablets, capsules, suspensions, and injectable products.
What generic launch scenarios should investors consider?
The relevant scenarios are now operational rather than patent-driven.
| Scenario |
Market effect |
Financial implication |
| Stable generic supply |
Continued low pricing and broad substitution |
Limited Pfizer upside |
| Supply disruption |
Temporary price increases or pharmacy shortages |
Short-term opportunity for available suppliers |
| Respiratory-season surge |
Higher prescription volume |
Modest volume benefit, low margin |
| Stewardship tightening |
Lower inappropriate use |
Long-term volume pressure |
| Brand relaunch or premium positioning |
Limited uptake |
Unlikely to recreate historical economics |
| Formulation-specific shortage |
Potential temporary value for an available product |
Narrow and unstable benefit |
The strongest commercial opportunity in azithromycin is usually supply reliability, not patent exclusivity.
Key Takeaways
- Zithromax is Pfizer’s original azithromycin brand and was approved in the United States in 1991.
- Core U.S. exclusivity ended in the mid-2000s.
- Generic azithromycin is the dominant market product.
- The current patent estate is weak and does not support meaningful broad-market exclusivity.
- Formulation and method-of-use claims historically created narrower barriers but did not prevent generic substitution across the market.
- Zithromax has no biosimilar risk; its risk is generic competition.
- Pfizer does not separately disclose a current Zithromax revenue stream that would support a precise standalone valuation.
- Temporary prescription increases during the COVID-19 period did not reverse long-term commoditization.
- Future economics depend on brand residual demand, geographic pricing, supply availability, and generic market structure.
FAQs About Zithromax Patents, Revenue, and Generic Competition
Is Zithromax still a branded prescription drug?
Yes. Zithromax remains a branded azithromycin product, but most U.S. prescriptions are filled with generic azithromycin because FDA-approved generics are available and pharmacy substitution is widespread.
Does Pfizer still have exclusive rights to azithromycin?
No broad U.S. exclusivity remains for azithromycin as an active ingredient. Any residual rights would be product-specific, jurisdiction-specific, or tied to narrow formulations or uses.
Can a generic manufacturer launch azithromycin without infringing Zithromax patents?
Generic manufacturers can enter after relevant patents expire, are invalidated, are not infringed, or are avoided through permitted labeling and formulation strategies. The long-established generic market confirms that broad Zithromax barriers no longer prevent entry.
Is Zmax more protected than standard Zithromax tablets?
Zmax used an extended-release oral suspension formulation that could have distinct formulation protection. That protection did not preserve exclusivity for the broader azithromycin market because conventional tablets, capsules, and suspensions remained available.
Is azithromycin still commercially important despite low prices?
Yes. Azithromycin remains clinically and commercially important because it is prescribed in large volumes worldwide. Its importance is based on volume and medical familiarity, not on branded pricing power or patent protection.
References
- U.S. Food and Drug Administration. (2023). Zithromax (azithromycin) prescribing information. Pfizer Laboratories.
- U.S. Food and Drug Administration. (2025). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (2024). Hatch-Waxman amendments and abbreviated new drug applications.
- Pfizer Inc. (2005-2024). Annual reports and Form 10-K filings.
- National Institutes of Health. (2024). COVID-19 treatment guidelines: Azithromycin.
- U.S. Food and Drug Administration. (2024). Generic drug facts and abbreviated new drug application requirements.