Last updated: August 12, 2026
Bimatoprost is a mature prostaglandin analog used primarily to reduce intraocular pressure in open-angle glaucoma and ocular hypertension. Its commercial history spans three products: Lumigan for glaucoma, Latisse for eyelash hypotrichosis, and Durysta, a biodegradable intracameral implant. The market has shifted from branded ophthalmology revenue to low-cost generic competition, while AbbVie retains differentiated value through Durysta and the Latisse brand.
Bimatoprost remains commercially relevant because glaucoma is chronic, treatment is recurrent, and prostaglandin analogs are established first-line therapies. Its financial profile is no longer driven by broad exclusivity for the original ophthalmic solution. Current value depends on formulation differentiation, physician adoption, procedure-based delivery, brand retention, and manufacturing scale.
What is bimatoprost and how is it marketed?
Bimatoprost is a synthetic prostamide analog that lowers intraocular pressure by increasing aqueous humor outflow. The FDA-approved products have distinct indications and commercial models.
| Product |
Active ingredient |
Indication |
Dosage form |
Primary commercial owner |
| Lumigan 0.01% and 0.03% |
Bimatoprost |
Glaucoma and ocular hypertension |
Topical ophthalmic solution |
AbbVie through Allergan |
| Latisse 0.03% |
Bimatoprost |
Hypotrichosis of the eyelashes |
Topical ophthalmic solution |
AbbVie through Allergan |
| Durysta |
Bimatoprost |
Glaucoma and ocular hypertension |
Biodegradable intracameral implant |
AbbVie through Allergan |
| Generic bimatoprost |
Bimatoprost |
Glaucoma and ocular hypertension |
Topical ophthalmic solution |
Multiple generic manufacturers |
Lumigan is dispensed chronically, generally once daily. Latisse is applied to the upper eyelid margin and is sold primarily through dermatology, aesthetics and direct-to-consumer channels. Durysta is administered by an eye-care professional and is reimbursed through a procedure-oriented model rather than a conventional retail prescription model. [1][2][3]
How large is the bimatoprost market?
The global bimatoprost market is mature and fragmented. Public companies generally do not report standalone bimatoprost revenue, and third-party market estimates vary because some reports include all formulations while others count only branded products.
The commercial market has four principal segments:
- Generic topical glaucoma treatment.
- Branded Lumigan prescriptions that remain where physicians or payers accept a brand premium.
- Latisse prescriptions for eyelash hypotrichosis.
- Durysta procedures for sustained intraocular pressure control.
Generic topical bimatoprost accounts for the largest unit share in the glaucoma segment. Brand revenue is concentrated in Latisse and Durysta, with residual Lumigan sales dependent on formulary positioning and prescriber loyalty.
What drives demand for bimatoprost?
Demand is supported by several structural factors:
- Glaucoma prevalence rises with age.
- Treatment is usually long term.
- Prostaglandin analogs are widely used as initial pharmacologic therapy.
- Bimatoprost has established clinical familiarity.
- Latisse has a separate consumer and aesthetic use.
- Durysta addresses adherence problems associated with daily eye drops.
Demand is constrained by generic substitution, pressure on ophthalmology reimbursement, medication adherence failures, ocular surface side effects, and competition from latanoprost, travoprost, tafluprost, beta blockers, carbonic anhydrase inhibitors and fixed-dose combinations.
What is the financial trajectory of bimatoprost?
Bimatoprost followed the standard lifecycle of a successful specialty pharmaceutical: rapid branded growth, line extension activity, patent erosion, generic substitution and portfolio repositioning.
Branded growth and peak commercialization
Allergan developed Lumigan as a major ophthalmology product and later launched Latisse in 2008 after receiving FDA approval for eyelash hypotrichosis. The Latisse launch expanded bimatoprost beyond ophthalmology and created a higher-margin branded aesthetic franchise. [2][4]
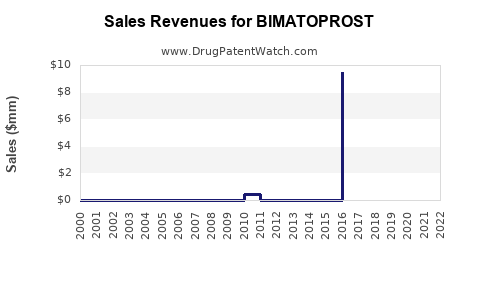
Allergan’s public reporting grouped products into broader therapeutic categories. It did not consistently disclose current standalone revenue for Lumigan, Latisse or Durysta. As a result, exact product-level revenue trends after generic entry cannot be established from AbbVie’s annual reports alone.
The principal financial phases were:
| Period |
Commercial phase |
Financial effect |
| 2001-2008 |
Lumigan market expansion |
Growth from branded glaucoma prescriptions |
| 2008-2012 |
Latisse launch and expansion |
New aesthetic revenue stream and brand premium |
| 2013-2017 |
Mature branded franchise |
Higher exposure to patent and generic-entry risk |
| 2017 onward |
Generic erosion of topical glaucoma sales |
Lower Lumigan volume and pricing |
| 2020 onward |
Durysta launch and relaunch activity |
Potential formulation-based replacement revenue |
| Current phase |
Mixed generic, branded aesthetic and implant market |
Revenue concentrated in differentiated products |
What happened to Lumigan sales after generic entry?
Generic bimatoprost materially changed the economics of Lumigan. Once abbreviated new drug application applicants received approval, payers and pharmacies gained an inexpensive substitute for the branded topical product. This reduced brand volume and increased rebate and formulary pressure.
Topical bimatoprost remains commercially viable for generic manufacturers because manufacturing is established, demand is recurring and the product is dispensed through a large ophthalmic market. For AbbVie, the strategic value of Lumigan is lower than its historic value because the core solution formulation no longer has broad market exclusivity.
How does Latisse affect the financial outlook?
Latisse has a different economic profile from Lumigan. It is a branded product with an aesthetic indication, lower dependence on chronic glaucoma formularies and greater exposure to cash-pay or partially reimbursed demand.
Latisse benefits from:
- Brand recognition among dermatologists and aesthetic prescribers.
- Consumer awareness of eyelash enhancement.
- Product differentiation based on an FDA-approved indication.
- A direct relationship between treatment and visible cosmetic outcome.
Its risks include generic or compounded alternatives, off-label use of ophthalmic bimatoprost, price sensitivity, cosmetic-cycle volatility and competition from eyelash serums and cosmetic products. Because Latisse is a small-molecule topical product, its long-term protection depends more on branding, distribution and regulatory positioning than on a strong composition-of-matter barrier.
What is Durysta’s commercial significance?
Durysta is the principal product that extends bimatoprost beyond the mature topical-solution market. The FDA approved Durysta in March 2020 as the first biodegradable intracameral implant for reducing intraocular pressure in patients with open-angle glaucoma or ocular hypertension. [3]
Durysta is designed to release bimatoprost inside the eye over an extended period, reducing dependence on daily topical administration. Its commercial model is materially different from Lumigan:
| Factor |
Lumigan |
Durysta |
| Administration |
Patient-applied daily drops |
Office-administered implant |
| Payment model |
Pharmacy benefit |
Medical or procedure-related reimbursement |
| Adherence dependence |
High |
Lower after administration |
| Manufacturing complexity |
Conventional sterile ophthalmic solution |
Drug-device implant with specialized production |
| Competitive barrier |
Limited after generic entry |
Higher technical and regulatory barrier |
| Principal risk |
Generic substitution |
Procedure adoption, safety, reimbursement and repeat dosing |
Durysta’s uptake has been affected by administration requirements, provider training, reimbursement, patient selection and concerns associated with repeated intracameral administration. Its value is therefore tied to clinical workflow and health-economic evidence, not only to the pharmacology of bimatoprost.
When does bimatoprost lose exclusivity?
The original U.S. exclusivity for topical bimatoprost has largely expired. Lumigan’s commercial protection was based on a combination of formulation patents, method-of-use patents, regulatory exclusivity and brand positioning rather than an enduring composition-of-matter monopoly.
What patents protect Lumigan and Latisse?
Historically relevant U.S. patent protection included patents directed to bimatoprost ophthalmic compositions and its use in treating glaucoma and ocular hypertension. U.S. Patent No. 6,403,649 was associated with ophthalmic compositions containing bimatoprost and had a term that reached the early 2020s under the applicable U.S. patent-term rules. U.S. Patent No. 7,351,404 covered use of bimatoprost for eyelash growth and reached the early 2020s. [5][6]
The effective commercial protection was affected by:
- Patent-term adjustment.
- Pediatric exclusivity.
- Paragraph IV litigation.
- Product-specific Orange Book listings.
- Authorized generic arrangements.
- FDA approval timing for competing products.
The expiration of key patents did not eliminate all barriers immediately. Generic applicants still had to satisfy FDA requirements for ophthalmic quality, sterility, formulation equivalence and manufacturing controls.
What patents protect Durysta?
Durysta is protected through a more complex combination of drug-device formulation claims, implant construction, biodegradation characteristics, drug release and methods of treating ocular hypertension. The relevant patent estate is more difficult to assess than the Lumigan estate because protection may be distributed across patents covering the implant, formulation, manufacturing process and administration method.
Durysta’s commercial barrier is therefore partly legal and partly technical. A competitor may need to reproduce a biodegradable implant with acceptable release kinetics, sterility, ocular tolerability and clinical performance. Those requirements increase development cost even if a single blocking patent is challenged or expires.
What is the Orange Book status of bimatoprost products?
Lumigan and Durysta are FDA-approved prescription products with Orange Book relevance. The Orange Book identifies approved products, therapeutic equivalence information and listed patents where applicable. Generic topical bimatoprost products rely on abbreviated new drug applications and are evaluated against the relevant reference-listed drug. [7]
Latisse is also an FDA-approved bimatoprost product, but its commercial and legal position differs because its approved indication is eyelash hypotrichosis. A generic approved for glaucoma is not automatically substitutable for Latisse for the cosmetic indication. Indication differences, labeling and patent certifications can affect the timing and scope of generic competition.
Durysta has a separate reference product and more specialized product characteristics. Generic or follow-on competition would require an FDA pathway appropriate to the product’s drug-device and implant attributes. The regulatory route is more demanding than a conventional ophthalmic solution ANDA.
Were there Paragraph IV challenges to bimatoprost?
Generic companies challenged key Lumigan patents through Paragraph IV certifications as part of the U.S. abbreviated approval process. These challenges contributed to patent litigation and accelerated the transition from branded to generic topical bimatoprost after the relevant patents expired or were resolved.
Paragraph IV risk for Lumigan was commercially significant because a first filer could obtain 180 days of generic exclusivity, creating a rapid price and volume shift. [7][8]
The competitive consequences were:
- Earlier loss of branded prescription volume.
- Rapid pharmacy substitution.
- Lower net pricing.
- Increased payer leverage.
- Reduced value of later-expiring secondary patents.
The same framework is less directly applicable to Durysta because the product is an intracameral implant rather than a standard topical solution. The legal and regulatory pathway for a follow-on implant may involve more complex questions of sameness, device performance and clinical comparability.
What generic entry risks exist for bimatoprost?
Topical glaucoma products
Generic entry risk is high for Lumigan-type topical solutions. The product is mature, multiple generic manufacturers participate and clinical substitution is straightforward when the formulation is accepted as therapeutically equivalent.
The principal residual risks for generic manufacturers are:
- Sterile manufacturing failures.
- Container-closure performance.
- Preservative and excipient differences.
- Supply interruptions.
- FDA inspection findings.
- Price compression caused by multiple approved suppliers.
Latisse
Latisse faces moderate-to-high substitution risk from generic bimatoprost and compounded products, but automatic substitution is less direct because of the eyelash-growth indication. The branded product retains value through FDA labeling, consumer awareness and physician confidence.
Durysta
Durysta faces lower near-term generic risk than topical bimatoprost but higher execution risk. A competing implant would need to meet demanding standards for release profile, biocompatibility, administration and clinical performance. Competitive risk could emerge from other sustained-release glaucoma technologies rather than from a direct bimatoprost copy.
How strong is the bimatoprost patent estate?
The estate is weak for the original topical molecule and stronger for the implant platform.
| Asset |
Patent strength |
Commercial interpretation |
| Bimatoprost molecule |
Low |
Mature small molecule with expired core protection |
| Lumigan solution |
Low to moderate historically; low currently |
Secondary formulation protection largely eroded |
| Latisse indication |
Moderate historically; declining after expiry |
Brand and labeling remain relevant |
| Durysta implant |
Moderate to strong |
Product-specific formulation, device and manufacturing barriers |
| Manufacturing know-how |
Moderate |
Sterile implant production may delay competitors |
| Brand equity |
Moderate for Latisse |
Non-patent protection supports price retention |
The strongest defensibility now comes from regulatory approval, physician familiarity, production know-how, and the commercial positioning of Latisse and Durysta. The historic Lumigan patent estate is no longer sufficient to support substantial monopoly pricing.
What FDA regulatory milestones shaped the market?
| Date |
Milestone |
| 2001 |
FDA approval of Lumigan for reducing elevated intraocular pressure |
| 2008 |
FDA approval of Latisse for eyelash hypotrichosis |
| 2010s |
Expansion of generic bimatoprost competition |
| March 2020 |
FDA approval of Durysta |
| 2020s |
Commercial development focused on sustained-release delivery and adherence |
The FDA approval of Latisse created a second indication with different economics. Durysta created a separate product category but required providers to adopt an office-based administration model. [2][3]
Which companies compete with bimatoprost?
Bimatoprost competes in a crowded glaucoma market.
Drug competitors
- Latanoprost, including Pfizer’s Xalatan legacy franchise and generic products.
- Travoprost, including Travatan and generic products.
- Tafluprost, including Zioptan.
- Timolol and other beta blockers.
- Dorzolamide and brinzolamide.
- Fixed-dose combinations such as dorzolamide/timolol and brimonidine/timolol.
- Sustained-release or implant-based glaucoma products.
Latanoprost is often the strongest generic comparator because of broad use, low cost and extensive physician familiarity. Bimatoprost may retain a role where intraocular-pressure reduction, tolerability, preservative profile or prior treatment response supports its selection.
Competitive delivery technologies
Durysta competes with alternative adherence technologies, including sustained-release implants, drug-eluting inserts, depot formulations and surgical or minimally invasive glaucoma procedures. The relevant commercial question is whether the technology reduces medication burden at a total cost acceptable to payers and providers.
What licensing deals and ownership changes affect bimatoprost?
Allergan acquired the rights and commercial platform associated with Lumigan and Latisse before AbbVie acquired Allergan in 2020. AbbVie therefore became the principal owner of the Allergan ophthalmology portfolio, including bimatoprost products. [9]
The bimatoprost franchise is strategically linked to AbbVie’s broader eye-care portfolio, which includes products and technologies in glaucoma, dry eye and ophthalmic surgery. Public filings do not identify a major recent third-party licensing transaction that materially changes ownership of the core bimatoprost franchise.
The economic value of the portfolio is now concentrated in product differentiation rather than in the original molecule.
What patent litigation affects bimatoprost?
The major litigation risk historically involved Paragraph IV challenges to patents covering Lumigan and related ophthalmic formulations. Those disputes were part of the standard generic-entry process and contributed to the loss of branded exclusivity.
Current litigation risk is more likely to involve:
- Durysta formulation and implant patents.
- Patent-term and Orange Book listing disputes.
- Product-specific manufacturing claims.
- Labeling and indication issues affecting Latisse substitution.
- Regulatory challenges involving follow-on implants.
No current litigation should be treated as commercially material without confirmation from the latest court docket, FDA Orange Book and AbbVie securities filings. Patent status must be assessed product by product because Lumigan, Latisse and Durysta do not have identical legal estates.
What revenue exposure does AbbVie have to bimatoprost?
AbbVie’s direct exposure is limited relative to its largest immunology, oncology and neuroscience products. The company reports revenue at broader product and therapeutic-area levels, and public filings do not provide a consistent standalone bimatoprost revenue series. [9]
The exposure is asymmetric:
- Lumigan contributes declining or limited branded revenue because of generic competition.
- Latisse provides a differentiated branded stream with aesthetic-market exposure.
- Durysta offers potential growth but remains dependent on physician adoption and reimbursement.
- Generic competition limits the value of topical glaucoma volume.
- Manufacturing and regulatory costs are higher for Durysta than for a conventional ophthalmic solution.
The likely financial trajectory is stable-to-declining for legacy branded drops, relatively resilient for Latisse, and uncertain but strategically important for Durysta.
What generic launch scenarios exist for bimatoprost?
Scenario 1: Continued generic erosion
This is the base case for Lumigan. Multiple generic suppliers maintain low prices, brand volume declines and AbbVie relies on Latisse and Durysta for differentiated revenue.
Scenario 2: Brand retention in selected channels
Lumigan retains a small branded niche where physicians prefer the original product, patients experience formulation-specific tolerability differences or payer contracts preserve access. This scenario supports residual revenue but not a return to historical peak economics.
Scenario 3: Faster Latisse substitution
Generic or compounded bimatoprost products gain broader use for eyelash growth. Latisse protects share through FDA-approved labeling and brand recognition but faces price pressure.
Scenario 4: Durysta expansion
Greater adoption of intracameral delivery improves the value of the bimatoprost franchise. Growth depends on repeat administration, safety data, reimbursement and provider workflow.
Scenario 5: Sustained-release competition
Alternative implants or depot technologies reduce Durysta’s growth potential. Competition would shift from molecule-based efficacy to delivery platform, procedure economics and patient selection.
How does bimatoprost compare with latanoprost?
| Metric |
Bimatoprost |
Latanoprost |
| Core class |
Prostaglandin analog/prostamide |
Prostaglandin analog |
| Branded franchise |
Lumigan, Latisse, Durysta |
Xalatan legacy franchise |
| Generic exposure |
High for topical solution |
High |
| Aesthetic indication |
Yes, Latisse |
No comparable FDA-approved brand |
| Sustained-release platform |
Durysta |
Less directly associated with a comparable approved implant |
| Commercial differentiation |
Latisse brand and Durysta delivery |
Low-cost generic scale and physician familiarity |
| Financial outlook |
Mature drops, differentiated extensions |
Mature generic market |
Bimatoprost has greater indication and formulation breadth. Latanoprost has stronger generic-market familiarity and cost positioning. The clinical and commercial balance depends on payer policy, tolerability, pressure-lowering response and delivery preference.
Key Takeaways
- Bimatoprost is a mature small-molecule franchise with high generic exposure in topical glaucoma.
- Lumigan’s original commercial protection has largely expired, and generic competition limits branded pricing power.
- Latisse remains the main branded topical asset because its FDA-approved eyelash indication supports brand differentiation.
- Durysta is the most important long-term asset because its intracameral implant design creates technical and regulatory barriers beyond the molecule itself.
- AbbVie does not publicly disclose a reliable standalone revenue series for bimatoprost products.
- The franchise’s future value depends on Durysta adoption, Latisse brand retention and manufacturing know-how, not on renewed exclusivity for conventional bimatoprost drops.
- Biosimilar risk is not relevant because bimatoprost is a synthetic small molecule. The relevant threat is generic and follow-on drug-device competition.
- The highest near-term generic risk is concentrated in Lumigan-type ophthalmic solutions.
FAQs About Bimatoprost Market and Patent Risk
Is bimatoprost still commercially profitable after generic entry?
Yes, but profitability is concentrated in differentiated products. Generic topical bimatoprost has low unit economics, while Latisse and Durysta can support higher value through branding and delivery differentiation.
Does bimatoprost have biosimilar competition?
No. Bimatoprost is a synthetic small molecule, so competitors enter through generic-drug pathways rather than biosimilar pathways.
Can generic bimatoprost be substituted for Latisse?
Not automatically for the cosmetic indication. The product, labeling, indication and state substitution rules determine whether a generic glaucoma product can replace Latisse in practice.
Is Durysta more protected than Lumigan?
Yes. Durysta relies on implant, formulation, release-profile, manufacturing and administration barriers. Lumigan is a conventional topical solution with extensive generic competition.
What is the main investment risk in the bimatoprost franchise?
The main risk is that Durysta adoption fails to offset the long-term erosion of branded topical revenue. Reimbursement, repeat dosing, safety, provider workflow and competing sustained-release technologies are the central variables.
References
- U.S. Food and Drug Administration. (2024). Lumigan (bimatoprost ophthalmic solution) prescribing information.
- U.S. Food and Drug Administration. (2024). Latisse (bimatoprost ophthalmic solution) prescribing information.
- U.S. Food and Drug Administration. (2020). FDA approves first implant to reduce eye pressure in patients with open-angle glaucoma.
- Allergan plc. (2008). Allergan announces FDA approval of Latisse for inadequate or not enough eyelashes.
- U.S. Patent No. 6,403,649. (2002). Ophthalmic compositions containing bimatoprost. United States Patent and Trademark Office.
- U.S. Patent No. 7,351,404. (2008). Use of bimatoprost for the treatment of eyelash hypotrichosis. United States Patent and Trademark Office.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book.
- U.S. Food and Drug Administration. (2024). Abbreviated new drug application approvals and 180-day generic drug exclusivity.
- AbbVie Inc. (2024). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934.