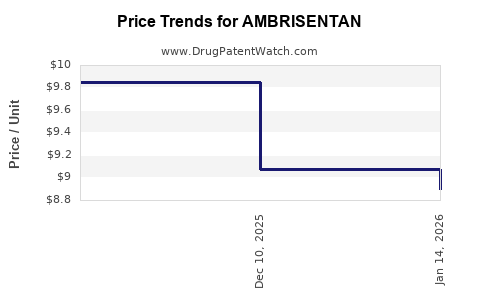
Last updated: September 7, 2026
Ambrisentan is a mature endothelin receptor antagonist for pulmonary arterial hypertension (PAH). Its commercial value has declined from peak branded sales because U.S. generic entry began in 2019, while treatment demand has shifted toward combination regimens and newer PAH products. Gilead Sciences retains the Letairis brand, but ambrisentan is no longer a major growth driver. The principal commercial opportunity is in generic supply, regional markets with slower substitution, and combination-based PAH treatment.
What is ambrisentan and how is it used?
Ambrisentan is an oral, once-daily selective endothelin A receptor antagonist. It is approved for adults with pulmonary arterial hypertension to improve exercise capacity and delay clinical worsening. The U.S. reference product is Letairis, marketed by Gilead Sciences. [1]
| Attribute |
Ambrisentan |
| Brand |
Letairis |
| Active ingredient |
Ambrisentan |
| Drug class |
Endothelin receptor antagonist |
| Primary indication |
Pulmonary arterial hypertension, WHO Group 1 |
| Administration |
Oral, once daily |
| Common strengths |
5 mg and 10 mg |
| U.S. approval |
2007 |
| Original developer |
Myogen |
| Current reference-product owner |
Gilead Sciences |
| Generic status |
Available in the United States |
| Principal competitors |
Macitentan, bosentan, tadalafil, sildenafil, riociguat, selexipag |
Ambrisentan selectively blocks the endothelin A receptor. The mechanism is intended to reduce endothelin-mediated vasoconstriction and vascular remodeling. Its once-daily schedule and selective receptor profile supported adoption, but edema, fluid retention, anemia and pregnancy-related restrictions limit the product's positioning.
How large is the ambrisentan market?
The global ambrisentan market is mature and fragmented between branded and generic products. The United States remains commercially important because of the size of the PAH treatment market, but generic penetration has materially reduced branded revenue.
The product's addressable market is determined by:
- The prevalence of PAH and the number of newly diagnosed patients.
- Use of initial combination therapy.
- Treatment switching from other endothelin receptor antagonists.
- Generic substitution and tender pricing.
- Reimbursement restrictions and specialty-pharmacy distribution.
- Patient access controls related to pregnancy risk.
PAH is a specialist market with high treatment costs and concentrated prescribing among pulmonary hypertension centers. That concentration supports targeted commercial programs but limits broad primary-care expansion.
How does ambrisentan compare with macitentan and bosentan?
| Factor |
Ambrisentan |
Macitentan |
Bosentan |
| Receptor profile |
Selective endothelin A |
Dual endothelin A/B |
Dual endothelin A/B |
| Dosing |
Once daily |
Once daily |
Twice daily |
| Liver monitoring |
Lower burden than bosentan, but clinically relevant monitoring remains |
Requires monitoring under labeling and local practice |
Significant liver-enzyme monitoring |
| Generic competition |
Yes |
Increasing in some markets |
Broad generic availability |
| Commercial position |
Mature, price-sensitive |
Stronger branded position for Opsumit |
Older, lower-cost option |
| Combination use |
Often combined with tadalafil |
Frequently used in combination regimens |
Used where cost and access dominate |
Macitentan has generally held the stronger branded position because Opsumit was launched later and was promoted as a successor-generation endothelin receptor antagonist. The AMBITION study also supported initial ambrisentan-tadalafil combination therapy, creating a clinically relevant role for ambrisentan despite its age. [2]
What is the financial trajectory for ambrisentan?
Gilead does not consistently report Letairis revenue as a separate current operating segment. Public filings show the broader trend: branded sales were meaningful before generic entry, then declined as generic competition expanded.
| Period |
Financial trajectory |
| 2007-2013 |
Rapid adoption following U.S. approval and expansion of PAH treatment |
| 2014-2017 |
Mature branded product with stable specialty-pharmacy demand |
| 2018 |
Revenue pressure began as generic approval and launch preparations advanced |
| 2019 |
U.S. generic entry created substantial price and volume erosion |
| 2020-2021 |
Continued decline in branded economics; generic and COVID-era access effects increased pressure |
| 2022 onward |
Mature, low-growth market with value concentrated in generics and non-U.S. markets |
Gilead's acquisition of Myogen in 2006 gave it control of the Letairis franchise before approval. The acquisition was valued at approximately $2.5 billion and also provided Gilead with Myogen's PAH pipeline and commercial platform. [3]
The key financial inflection point was generic entry, not a collapse in disease demand. PAH diagnoses and treatment intensity continued to support market volume, but the value of each prescription fell. The branded product therefore moved from a growth asset to a defensive or residual asset.
What drove the decline in Letairis revenue?
The main drivers were:
- U.S. generic competition after loss of effective commercial exclusivity.
- Price substitution by payers and specialty pharmacies.
- Greater use of macitentan and other combination-based treatment strategies.
- Limited ability to expand the indication base beyond PAH.
- Restricted prescriber concentration within specialty centers.
- Reduced value of brand differentiation after the core mechanism became established.
The market did not require a therapeutic failure to produce revenue erosion. Once equivalent generic supply became available, formulary and payer behavior reduced the economic value of the branded product.
When did ambrisentan lose exclusivity?
U.S. commercial exclusivity ended in stages. Letairis received FDA approval in June 2007. The product was protected by a combination of compound, formulation, regulatory and use-related rights, but the practical market barrier weakened when FDA-approved generic versions became available.
FDA records identify generic ambrisentan approvals in 2019. Teva and other manufacturers entered the U.S. market under abbreviated new drug applications. [4] The timing was commercially important because generic entry occurred before the end of the product's entire theoretical patent life, reflecting patent litigation and settlement outcomes rather than a simple expiration-only pathway.
What is the Orange Book status of Letairis?
Letairis has historically had Orange Book-listed patents covering the drug product and related uses. The relevant legal position has changed over time as patents expired, settlements took effect and generic applicants entered the market.
The Orange Book is the controlling public source for current listed patents, expiration dates and exclusivity data. FDA's online listing should be used for a live patent-status determination because the commercial status of an individual listing can change through expiration, delisting or administrative updates. [5]
For investment and launch analysis, the critical conclusion is that Orange Book protection no longer prevents U.S. generic supply. A current entrant would focus less on blocking all generic competition and more on product quality, supply reliability, contracting and state-level substitution.
Which patents protect ambrisentan?
Ambrisentan protection has historically included several categories:
Compound patents
Early patents covered ambrisentan and related endothelin receptor antagonist chemical structures. These rights formed the foundation of the Letairis franchise but are no longer sufficient to block ordinary U.S. generic entry.
Formulation and dosage-form patents
Product-related claims can cover tablet composition, dosage strengths, excipient combinations, dissolution characteristics and manufacturing parameters. These patents may create narrower barriers than a compound patent because a generic manufacturer can design around the claim or certify that it will not market a protected use.
Method-of-use patents
Use claims may cover treatment of PAH, dosing regimens or combinations with other therapies. Method patents can support targeted litigation, but their commercial value depends on labeling, physician prescribing behavior and the ability to enforce induced-infringement claims.
Regulatory exclusivity
Ambrisentan was approved before the current generic market developed. Regulatory exclusivity periods associated with the original approval have expired. Pediatric or orphan-related rights do not provide a current barrier equivalent to market exclusivity for the U.S. product.
Were there Paragraph IV challenges to Letairis?
Yes. Generic applicants used abbreviated new drug application procedures and challenged the enforceability or infringement of listed Letairis patents. Paragraph IV litigation and related settlements helped determine when generic manufacturers could enter before the full expiration of every listed patent.
The commercial result was more important than any single lawsuit: U.S. generic ambrisentan became available in 2019, causing the branded product to lose substantial pricing power. Public docket and settlement records should be reviewed for applicant-specific launch dates, licensed entry provisions, royalties, manufacturing restrictions and authorized-generic terms. FDA's Drugs@FDA and Orange Book records provide the relevant regulatory framework. [4,5]
What patent litigation and settlement risks affect ambrisentan?
The main litigation risks for ambrisentan are now narrower than they were before generic launch.
| Risk area |
Current commercial effect |
| Orange Book patent dispute |
More relevant to a new entrant seeking an early or differentiated launch |
| Formulation claim |
Can affect a specific generic design but rarely blocks all supply |
| Method-of-use claim |
May affect labeling and skinny-label strategy |
| Manufacturing patent |
Can require an alternative process or supplier |
| Settlement agreement |
May contain launch, licensing or royalty restrictions |
| Regulatory petition |
Can delay approval or create labeling disputes |
| REMS-related access |
May affect distribution economics, but is not a durable exclusivity barrier |
The central diligence issue is whether a proposed generic uses the same formulation and manufacturing route as an incumbent. Patent risk is product-specific. An ambrisentan tablet that differs in excipients, process or labeling may face a different risk profile from an existing approved generic.
What is the FDA regulatory status of ambrisentan?
Letairis is FDA approved for PAH in adults. FDA-approved generics are available. Ambrisentan distribution has historically involved risk-management controls because of embryo-fetal toxicity. Letairis was subject to a restricted distribution and monitoring framework, and FDA later modified the risk-management requirements as generic availability developed. [1,6]
The most important regulatory constraints are:
- Contraindication in pregnancy.
- Mandatory pregnancy testing and contraception requirements.
- Risk of fetal harm.
- Potential edema and fluid retention.
- Hematologic effects, including reduced hemoglobin.
- Specialty-pharmacy and prescriber-management requirements.
- Need for labeling consistency between reference and generic products.
These controls raise administrative costs but do not create durable commercial exclusivity.
What generic entry risks exist?
Generic competition is established in the United States, but market entry remains operationally demanding.
Supply and manufacturing barriers
Ambrisentan is a small-molecule tablet, so it does not have the manufacturing complexity of a biologic. The principal barriers are:
- Demonstrating bioequivalence.
- Controlling impurities and polymorphic characteristics.
- Maintaining consistent dissolution across strengths.
- Managing specialized packaging and labeling.
- Meeting pregnancy-risk distribution requirements.
- Securing active pharmaceutical ingredient supply.
- Obtaining favorable specialty-pharmacy and payer contracts.
The manufacturing barrier is moderate. It is high enough to limit casual entry but too low to preserve meaningful long-term monopoly pricing.
Commercial barriers
A generic supplier must compete on more than approval. Relevant factors include:
- Wholesale acquisition cost.
- Medicaid and commercial rebate exposure.
- Specialty-pharmacy access.
- Reliable supply during demand surges.
- Contracting with pulmonary hypertension treatment centers.
- Ability to support risk-management administration.
- Portfolio coverage across 5 mg and 10 mg strengths.
A limited number of reliable suppliers can maintain higher prices than a fully commoditized market, but the direction remains toward lower net prices.
How strong is the ambrisentan patent estate?
The current estate is commercially weak as a broad blocking platform and potentially useful as a narrow defensive estate.
| Dimension |
Assessment |
| Core compound protection |
Expired or no longer commercially blocking in the U.S. |
| Formulation protection |
Potentially relevant to specific product designs |
| Method-of-use protection |
Narrow, labeling-dependent and harder to monetize |
| Manufacturing protection |
Possible process-level barrier |
| Regulatory exclusivity |
Expired for the original product |
| Litigation leverage |
Limited after generic entry |
| Global position |
Variable by country and local patent history |
| Overall strength |
Low for blocking generic market access; moderate for product-specific defense |
Outside the United States, patent and regulatory positions vary. Countries with slower generic registration, local reimbursement controls or limited supplier competition may preserve higher branded or generic margins. The European and emerging-market positions require country-by-country review.
What licensing deals shaped the ambrisentan market?
The major transaction was Gilead's acquisition of Myogen in 2006. The deal gave Gilead rights to ambrisentan and expanded its PAH portfolio before Letairis approval. [3]
Later commercial arrangements focused more on distribution, specialty-pharmacy access and generic supply than on major new molecule licensing. The strategic value of ambrisentan therefore shifted from asset acquisition to portfolio management. Gilead's PAH franchise also included other products and pipeline assets, allowing the company to use a broader pulmonary hypertension platform rather than depend exclusively on Letairis.
What is the competitive outlook for ambrisentan?
Ambrisentan will remain commercially relevant because PAH is chronic, specialist-managed and often treated with combination therapy. Its growth outlook is limited.
The most likely market trajectory is:
- Continued volume in generic and lower-cost channels.
- Further price compression in the United States.
- Stable or declining branded demand.
- Selective value in markets with delayed generic access.
- Ongoing use in combination with tadalafil.
- Competitive displacement by macitentan where branded access is available.
- Persistent demand where physicians prioritize once-daily dosing and established clinical data.
Ambrisentan's strongest remaining differentiation is its clinical familiarity, once-daily administration and role in combination treatment. Its weakest attributes are generic availability, limited patent leverage and the absence of a meaningful new-indication strategy.
Key Takeaways
- Ambrisentan is a mature PAH therapy marketed in the United States as Letairis.
- Gilead acquired the asset through its 2006 acquisition of Myogen.
- U.S. generic entry began in 2019 and materially reduced branded revenue.
- The market remains clinically durable but financially price-sensitive.
- Ambrisentan competes mainly with macitentan, bosentan and other PAH pathway therapies.
- Core patent protection no longer blocks U.S. generic access.
- Formulation, method-of-use and manufacturing patents may still affect specific products.
- The FDA status is established, but pregnancy-risk controls remain central to distribution.
- The financial opportunity has moved from branded growth to generic supply, contracting and selected international markets.
- The overall patent estate is weak as a market-blocking platform and more relevant for product-specific defense.
FAQs About Ambrisentan Market and Patent Risk
Is ambrisentan still commercially viable after generic entry?
Yes, but primarily as a generic or low-cost specialty product. Branded growth is limited, while demand remains supported by chronic PAH treatment and combination therapy.
Does ambrisentan have biologic or biosimilar competition?
No. Ambrisentan is a chemically synthesized small molecule. Its competitive threat comes from generic tablets and other PAH drugs, not biosimilars.
Can a company launch a new ambrisentan generic without copying Letairis?
Yes. An applicant may use an abbreviated new drug application with a formulation and manufacturing design that meets bioequivalence requirements and avoids applicable patent claims.
Is ambrisentan more commercially attractive than macitentan?
Macitentan generally has stronger branded economics, while ambrisentan offers a lower-cost and more established generic opportunity. The answer depends on whether the business model is branded specialty commercialization or generic supply.
What is the largest remaining commercial risk for an ambrisentan manufacturer?
The largest risk is price and supply competition. Once multiple approved suppliers are active, payer contracting, reliable API supply and manufacturing consistency become more important than patent exclusivity.
References
- U.S. Food and Drug Administration. (2007). Letairis (ambrisentan) prescribing information.
- Galiè, N., Barbera, J. A., Frost, A. E., et al. (2015). Initial use of ambrisentan plus tadalafil in pulmonary arterial hypertension. New England Journal of Medicine, 373(9), 834-844.
- Gilead Sciences, Inc. (2006). Gilead Sciences to acquire Myogen, Inc. Company announcement.
- U.S. Food and Drug Administration. (2019). Drugs@FDA: Ambrisentan abbreviated new drug application approvals.
- U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (2019). FDA removes certain REMS requirements for endothelin receptor antagonists.