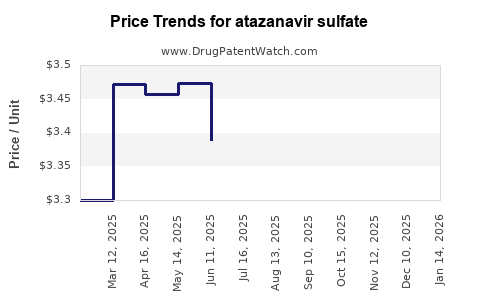
Last updated: September 7, 2026
Atazanavir sulfate is a mature HIV-1 protease inhibitor marketed originally as Reyataz by Bristol-Myers Squibb. The FDA approved Reyataz in 2003 for combination treatment of HIV-1 infection. Its commercial value declined as treatment shifted toward integrase strand-transfer inhibitors, while generic atazanavir and low-cost antiretroviral procurement further reduced pricing power. The core U.S. patent estate has expired, and the product has no biosimilar pathway because it is a small-molecule drug rather than a biologic.
What is atazanavir sulfate and how is it used?
Atazanavir sulfate is the sulfate salt of atazanavir, an orally administered HIV-1 protease inhibitor. It prevents maturation of viral polyproteins and is used in combination with other antiretroviral agents.
| Attribute |
Atazanavir sulfate |
| Brand |
Reyataz |
| Original developer |
Bristol-Myers Squibb |
| FDA application |
NDA 021567 |
| FDA approval |
June 20, 2003 |
| Drug class |
HIV-1 protease inhibitor |
| Dosage forms |
Oral capsules; oral powder in selected markets |
| Typical adult regimen |
300 mg once daily with ritonavir 100 mg, or selected unboosted regimens |
| Administration requirement |
With food |
| Key pharmacokinetic issue |
CYP3A metabolism and pH-dependent absorption |
| Main safety concern |
Indirect hyperbilirubinemia; also cardiac conduction and renal risks |
| Current competitive position |
Mature, largely generic, lower-priority regimen option |
Atazanavir was commercially differentiated by once-daily dosing and a relatively favorable lipid profile compared with some earlier protease inhibitors. Its disadvantages include food requirements, extensive drug-interaction management, acid-reducing-agent restrictions, jaundice-related bilirubin elevation, and the need for pharmacokinetic boosting in many patients (U.S. Food and Drug Administration [FDA], 2017).
When did atazanavir lose market exclusivity?
The primary U.S. compound patent protecting atazanavir was US 6,087,383, assigned to Bristol-Myers Squibb and covering the atazanavir chemical class. The patent issued in 2000 and had a nominal 20-year term measured from the earliest effective U.S. filing date. Its effective exclusivity period ended in the late 2010s after applicable patent-term adjustment and pediatric exclusivity.
The practical U.S. loss-of-exclusivity window was approximately 2017-2018. Generic atazanavir products subsequently entered the market, eliminating most of the branded product's ability to sustain premium pricing.
| Exclusivity element |
Timing and commercial effect |
| FDA approval |
2003 |
| Core compound protection |
Expired in the late 2010s |
| Pediatric exclusivity |
Extended protection into approximately 2018 |
| Generic entry |
Began after core regulatory and patent barriers ended |
| Current position |
Mature generic market with limited branded leverage |
The commercial significance of the expiry was greater than the loss of a single capsule patent. Atazanavir's main value was tied to the molecule itself, rather than to a technically difficult delivery system or complex manufacturing process.
What patents protect atazanavir sulfate?
Core composition patents
The principal protection centered on the atazanavir compound and related protease-inhibitor structures. The relevant estate included:
- US 6,087,383, covering atazanavir-related compounds.
- Related foreign counterparts and regional family members.
- Salt, formulation, process, and use claims associated with the active pharmaceutical ingredient.
Core composition protection is the most commercially important category because it restricts direct substitution with the same active ingredient. Once the compound patent expired, secondary patents had limited ability to preserve broad market exclusivity.
Formulation and dosage patents
Atazanavir is administered orally, and its formulations address:
- Salt formation and crystalline properties.
- Capsule composition.
- Oral powder or pediatric administration.
- Stability and manufacturing controls.
- Combination use with pharmacokinetic boosters.
These patents generally provide narrower protection than a composition-of-matter patent. They can affect particular products or manufacturing routes, but they do not ordinarily prevent all generic versions of the active ingredient.
Method-of-use patents
Method-of-use protection has focused on treating HIV infection, dosing with ritonavir, use in treatment-experienced patients, and administration in selected patient populations. HIV treatment patents often face practical limitations because physicians can prescribe a generic product for an indication even when a narrow method claim remains in force.
What is the FDA and Orange Book status of atazanavir?
Reyataz was approved through the FDA's new drug application pathway. Generic atazanavir products are approved through abbreviated new drug applications. The Orange Book historically listed patents associated with the Reyataz NDA, including composition and use-related rights.
Atazanavir is not a biologic and therefore does not have biosimilar competition. The relevant competitive pathway is generic substitution under the Hatch-Waxman framework.
Paragraph IV challenges
The commercial Paragraph IV period was principally relevant before and around the loss-of-exclusivity period. Generic applicants could challenge listed patents by asserting that patents were invalid, unenforceable, or not infringed. After expiration of the core composition protection, the commercial value of further Paragraph IV attacks declined materially.
The market no longer depends on a successful Paragraph IV challenge to unlock the molecule. The key economic question is manufacturing cost and procurement access, not whether a generic applicant can overcome a surviving foundational patent.
How did atazanavir revenue change over time?
Reyataz generated more than $1 billion annually during its peak commercial period, supported by HIV treatment demand and the limited number of once-daily protease-inhibitor alternatives. Sales then declined as physicians moved first-line treatment toward integrase-based regimens and as generic competition approached.
Bristol-Myers Squibb reported the following approximate Reyataz sales in its annual reporting:
| Year |
Approximate global sales |
Main driver |
| 2013 |
About $1.5 billion |
Mature branded HIV franchise |
| 2014 |
About $1.4 billion |
Continued use in combination therapy |
| 2015 |
About $1.2-$1.3 billion |
Regimen migration and pricing pressure |
| 2016 |
About $1.0-$1.1 billion |
Pre-expiry erosion |
| 2017 onward |
Declining sharply |
Generic entry and loss of branded exclusivity |
Reported figures can vary by annual-report presentation and product classification. Bristol-Myers Squibb later reduced the level of product-specific disclosure as Reyataz became less material to group results (Bristol-Myers Squibb, 2014, 2015, 2016, 2017).
The financial trajectory followed the standard pattern for a mature small-molecule antiretroviral:
- Rapid growth after approval and guideline adoption.
- Peak sales above $1 billion.
- Gradual decline from therapeutic substitution.
- Faster erosion near patent expiry.
- Post-expiry commoditization and lower manufacturer revenue.
How did integrase inhibitors affect atazanavir demand?
The largest structural threat was not generic entry. It was therapeutic substitution.
Modern HIV guidelines generally favor integrase inhibitor-based regimens because they provide high antiviral potency, rapid viral-load suppression, fewer interactions, and simpler administration. Common competitors include dolutegravir, bictegravir, and raltegravir-based products. Single-tablet regimens also reduce pill burden and improve treatment convenience.
| Product class |
Commercial effect on atazanavir |
| Integrase inhibitors |
Replaced protease inhibitors in many first-line regimens |
| Single-tablet combinations |
Reduced demand for multi-product regimens |
| Generic boosted protease inhibitors |
Increased price competition |
| Treatment guidelines |
Shifted new starts away from atazanavir |
| Resource-limited markets |
Preserved some demand through low-cost procurement |
Atazanavir remains clinically relevant for selected patients, including individuals with prior treatment history, resistance considerations, or specific regimen constraints. That use does not recreate the earlier branded market.
What generic entry risks exist for atazanavir sulfate?
Generic entry risk is high because the product has several characteristics that favor substitution:
- The active ingredient is chemically defined.
- The dosage form is an oral capsule.
- Manufacturing does not require biologic cell culture.
- The core composition patent has expired.
- The product is administered through a conventional generic pathway.
- Multiple international suppliers can compete on price.
The principal barriers are regulatory quality, bioequivalence, active pharmaceutical ingredient supply, stability, and compliance with antiretroviral procurement standards. These are manufacturing and regulatory barriers, not durable exclusivity barriers.
In the United States, generic manufacturers can compete through abbreviated new drug applications. In lower-income markets, procurement is often shaped by Global Fund tenders, national HIV programs, WHO prequalification, and voluntary or public-health purchasing arrangements.
Which companies compete in the atazanavir market?
Competition varies by jurisdiction. The market includes:
- Bristol-Myers Squibb as the original Reyataz sponsor.
- Teva and other FDA-approved generic suppliers.
- Indian manufacturers serving international and tender markets.
- Regional suppliers producing atazanavir capsules under national approvals.
- Contract manufacturers supplying public-sector programs.
The branded product's competitive position is weak against both generic atazanavir and newer branded combination regimens. Manufacturers with vertically integrated API production, low-cost regulatory operations, and established public-sector distribution have the strongest position in the post-exclusivity market.
What licensing deals affect atazanavir sulfate?
Atazanavir was part of the broader HIV antiretroviral licensing and access environment, including technology transfer, voluntary licensing, public-health procurement, and regional supply arrangements. The financial value of such arrangements is generally lower than the original branded commercial opportunity because generic access depends on volume and low unit cost.
The important distinction is between:
- Original discovery and commercialization rights.
- Regional distribution rights.
- Public-health licensing.
- Generic manufacturing rights.
- Procurement contracts.
No current licensing structure restores the broad commercial exclusivity once provided by the expired composition patent.
What patent litigation and settlement issues affect the product?
Atazanavir's major litigation exposure was concentrated around the pre-expiry period, when generic applicants had an economic incentive to challenge listed patents. After the expiration of the primary compound protection, the litigation value of formulation or narrow method claims declined.
There is no biosimilar litigation risk. Any current patent dispute would more likely involve a specific formulation, manufacturing process, dosage limitation, or jurisdiction rather than ownership of the active molecule itself.
How strong is the atazanavir patent estate today?
The current estate is weak from a commercial-exclusivity perspective.
| Patent-estate factor |
Assessment |
| Core compound protection |
Expired |
| Formulation protection |
Narrow and product-specific |
| Method-of-use protection |
Limited practical blocking effect |
| Manufacturing protection |
Potentially relevant to individual routes |
| Generic substitution risk |
High |
| Biosimilar risk |
Not applicable |
| Ability to support premium pricing |
Low |
| Geographic strength |
Uneven; depends on national expiry and registration status |
Remaining rights may matter for a particular supplier or jurisdiction, but they do not support a broad branded moat.
What is the outlook for atazanavir sulfate revenue?
Atazanavir revenue is likely to remain a low-growth or declining category in high-income markets. Demand will persist where:
- Patients require protease-inhibitor therapy.
- Clinicians use atazanavir for lipid-related considerations.
- Generic supply is reliable.
- Public-health programs prioritize low-cost antiretroviral access.
- Treatment guidelines retain protease inhibitors for selected circumstances.
The product's financial value has shifted from branded margin to volume-based generic supply. Revenue opportunity is concentrated in API efficiency, tender participation, regional registration, and reliable manufacturing rather than premium pricing or lifecycle innovation.
Key Takeaways
- Atazanavir sulfate is the active ingredient in Reyataz, originally developed and marketed by Bristol-Myers Squibb.
- FDA approval occurred in 2003 under NDA 021567.
- The core U.S. patent estate expired in the late 2010s, with pediatric exclusivity extending protection into approximately 2018.
- Reyataz reached annual sales of roughly $1 billion to $1.5 billion before exclusivity erosion.
- Integrase inhibitors caused substantial therapeutic substitution before generic competition fully developed.
- Generic entry risk is high because atazanavir is a conventional oral small molecule.
- Biosimilar competition does not apply.
- Remaining formulation, method, or process patents have limited ability to block broad substitution.
- Future commercial value is concentrated in low-cost manufacturing, public procurement, and selected treatment-experienced patients.
FAQs About Atazanavir Sulfate Market and Patents
Is atazanavir sulfate still sold under the Reyataz brand?
Yes. Reyataz remains the reference product in some markets, but generic atazanavir has substantially reduced the branded product's commercial importance.
Does atazanavir sulfate require ritonavir?
Many adult regimens use atazanavir with ritonavir or another pharmacokinetic booster. Some patients may receive unboosted atazanavir under specific clinical circumstances, subject to treatment guidelines and drug-interaction considerations.
Is atazanavir sulfate included in HIV public-health procurement?
Yes. Generic atazanavir can be included in national HIV programs and international tenders, particularly for patients who require protease-inhibitor-based therapy.
Can a generic manufacturer obtain FDA approval for atazanavir capsules?
Yes. The product is eligible for the abbreviated new drug application pathway, subject to pharmaceutical equivalence, bioequivalence, quality, and manufacturing requirements.
What is the largest commercial threat to atazanavir?
The largest threat is therapeutic substitution by integrase inhibitor regimens and single-tablet combinations. Generic price erosion is the second major threat.
References
-
Bristol-Myers Squibb. (2014). 2013 annual report. Bristol-Myers Squibb Company.
-
Bristol-Myers Squibb. (2015). 2014 annual report. Bristol-Myers Squibb Company.
-
Bristol-Myers Squibb. (2016). 2015 annual report. Bristol-Myers Squibb Company.
-
Bristol-Myers Squibb. (2017). 2016 annual report. Bristol-Myers Squibb Company.
-
U.S. Food and Drug Administration. (2017). Reyataz prescribing information. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. U.S. Department of Health and Human Services.
-
World Health Organization. (2022). Consolidated guidelines on HIV prevention, testing, treatment, service delivery and monitoring. World Health Organization.