Last updated: October 4, 2026
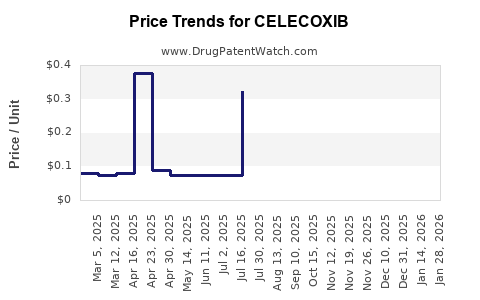
Celecoxib is a mature, largely genericized COX-2 selective nonsteroidal anti-inflammatory drug. Its commercial trajectory moved from blockbuster status under Pfizer’s Celebrex brand to a high-volume, low-price generic market after U.S. patent expiry. Revenue remains supported by osteoarthritis, rheumatoid arthritis, acute pain, and dysmenorrhea demand, but pricing power is limited by multiple generic manufacturers and substitution by other NSAIDs.
The principal commercial variables are generic price erosion, chronic-use volume, cardiovascular and gastrointestinal risk management, branded formulation extensions, and market access in countries where generic competition is less developed.
What is celecoxib and how large is its market?
Celecoxib is a selective cyclooxygenase-2, or COX-2, inhibitor approved by the FDA in 1998. The original U.S. brand was Celebrex, developed by Searle and later commercialized by Pfizer after Pfizer acquired Pharmacia in 2003. The drug is approved for osteoarthritis, rheumatoid arthritis, juvenile rheumatoid arthritis, ankylosing spondylitis, acute pain, and primary dysmenorrhea.[1]
Celecoxib is available mainly as oral capsules in 50 mg, 100 mg, 200 mg, and 400 mg strengths. The generic product is sold by multiple manufacturers, including Teva, Mylan, Amneal, Lupin, Aurobindo, and other FDA-approved suppliers.
Public market-size estimates vary because analysts define the market differently. Some estimates include only celecoxib capsules; others include the wider COX-2 inhibitor or NSAID market. The most reliable commercial conclusion is that celecoxib has moved from a multibillion-dollar branded market to a large-volume generic market with substantially lower unit prices.
| Market attribute |
Current commercial position |
| Primary therapeutic areas |
Osteoarthritis, rheumatoid arthritis, acute pain, dysmenorrhea |
| Drug class |
COX-2 selective NSAID |
| U.S. brand |
Celebrex |
| Main manufacturer of original brand |
Pfizer |
| U.S. regulatory status |
Approved prescription drug; multiple generic ANDAs |
| Dominant dosage form |
Oral capsule |
| Primary revenue driver |
Generic prescription volume |
| Main commercial constraint |
Low generic pricing and broad NSAID substitution |
Celecoxib retains a clinical niche because it can reduce gastrointestinal ulcer risk relative to many nonselective NSAIDs, although it carries important cardiovascular, renal, gastrointestinal, and hypersensitivity risks. Its FDA label contains a boxed warning for serious cardiovascular thrombotic events and serious gastrointestinal adverse events.[1]
How did Celebrex revenue change after patent expiry?
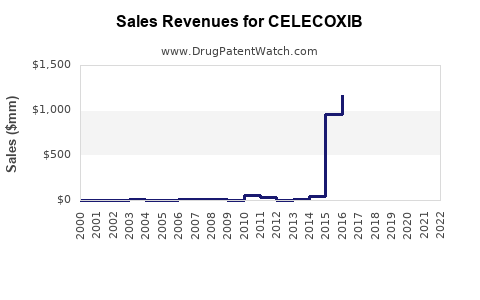
Celebrex generated peak branded revenue before and around the period of patent litigation and market-entry uncertainty. Pfizer reported approximately $2 billion or more in annual Celebrex revenue during several years of the 2000s and early 2010s, supported by chronic arthritis treatment, post-Vioxx demand, and the scale of the U.S. NSAID market.[2]
Revenue declined after generic entry because generic manufacturers competed on price and pharmacy benefit managers substituted lower-cost products. Pfizer’s later filings no longer provide a consistently separate global revenue line for Celebrex, which limits precise current brand-revenue tracking.[3]
| Period |
Financial trajectory |
Main driver |
| 1998-2004 |
Rapid growth toward blockbuster status |
New COX-2 class, broad pain indications, branded pricing |
| 2005-2010 |
High but pressured revenue |
Vioxx withdrawal changed class perception; safety scrutiny increased |
| 2011-2014 |
Mature branded product with patent disputes |
Chronic demand remained high while generic-entry risk increased |
| 2014-2015 |
Sharp transition toward generic competition |
U.S. patent expiry and authorized or independent generic launches |
| 2016-2020 |
Lower branded revenue, stable generic demand |
Price erosion offset by prescription volume |
| 2021-present |
Mature, low-growth market |
Generic supply, low prices, and clinical substitution |
The financial model changed from margin expansion to volume preservation. A branded manufacturer could no longer rely on price increases or exclusive distribution. Generic companies compete primarily on manufacturing cost, supply reliability, wholesaler contracts, and formulary access.
When did celecoxib lose U.S. exclusivity?
The principal U.S. compound patent associated with Celebrex was U.S. Patent No. 5,466,823, covering celecoxib and related substituted pyrazolyl benzenes. The patent was issued in 1995 and reached its ordinary expiration in December 2014, subject to applicable patent-term and pediatric-exclusivity calculations.[4]
The timing of generic entry was shaped by Paragraph IV litigation and settlement agreements rather than by a simple uncontested patent expiry. Teva and other generic companies challenged Pfizer’s patent position. Generic entry began around the end of 2014, materially changing the U.S. price and market structure.[5]
| Exclusivity element |
Approximate timing |
| FDA approval of Celebrex |
1998 |
| Core compound patent issuance |
1995 |
| Core U.S. patent expiration |
December 2014 |
| First major U.S. generic-entry period |
Late 2014 to 2015 |
| Current status |
Generic competition established |
The precise launch date varied by manufacturer, dosage strength, settlement terms, and regulatory approval. Once multiple generic suppliers entered, the commercial value of the original compound patent fell sharply.
What patents protect celecoxib and its formulations?
The original protection centered on the celecoxib chemical entity and related compounds. Later patent and regulatory protections focused on formulations, dosage regimens, manufacturing processes, and new delivery systems rather than on the core molecule.
Core compound patent
U.S. Patent No. 5,466,823 was the principal patent associated with Celebrex’s original exclusivity position.[4] Its expiration removed the main barrier to conventional celecoxib capsule competition.
Formulation and delivery patents
Formulation patents can protect particle size, dissolution, bioavailability, excipients, suspension systems, or liquid delivery. These patents do not automatically block generic capsules. Their commercial value depends on whether the formulation captures a clinically meaningful or commercially relevant patient segment.
The FDA approved Elyxyb, a celecoxib oral solution, for the acute treatment of migraine with or without aura in adults. Elyxyb was developed by Dr. Reddy’s Laboratories and later commercialized by Scilex Holding Company.[6] Its oral-solution format creates a separate product position from conventional celecoxib capsules, but it does not restore broad compound-level exclusivity.
Method-of-use patents
Method-of-use patents may cover treatment of a specific condition, dosing population, or administration schedule. For celecoxib, the commercial effect of method-of-use protection is limited where generic labels can use a skinny-label strategy or where physicians prescribe the generic product for nonprotected indications.
Method-of-use patents are more relevant to new celecoxib products than to the original Celebrex franchise. Their strength depends on claim specificity, infringement evidence, induced-infringement risk, and the ability of the product sponsor to control prescribing or reimbursement.
What is the Orange Book status of Celebrex and generic celecoxib?
Celebrex is an FDA-approved prescription product, and generic celecoxib capsules have been approved through abbreviated new drug applications. The Orange Book distinguishes the reference-listed drug from approved generics and records eligible patent or exclusivity information submitted for listed products.[7]
The practical Orange Book position is:
- The original compound-level exclusivity has expired.
- Multiple generic celecoxib capsule products are approved.
- Current market barriers are primarily manufacturing, supply, regulatory, and commercial rather than basic compound patent barriers.
- Product-specific patents may remain relevant for newer formulations or indications, but they do not generally prevent conventional celecoxib capsule substitution.
Generic applicants that certify Paragraph IV against listed patents can trigger patent litigation under the Hatch-Waxman Act. A sponsor’s ability to delay entry depends on the litigation outcome, settlement terms, and whether the challenged patent is enforceable and infringed.
Which companies challenged Celebrex patents?
Pfizer faced Paragraph IV challenges from major generic manufacturers during the period preceding core patent expiry. Teva was among the most important challengers, and other generic manufacturers pursued approval or market entry as the patent estate weakened.[5]
The competitive field included large U.S. and international generic companies with established NSAID manufacturing capabilities. The relevant commercial question was not whether one company could challenge the patent, but how quickly several suppliers could enter after the first launch.
| Participant type |
Commercial role |
| Pfizer |
Originator, reference-listed drug sponsor, brand owner |
| Teva |
Major generic challenger and supplier |
| Mylan and other large generics |
Additional competitive pressure and supply capacity |
| Regional generic manufacturers |
Country-specific competition outside the U.S. |
| Scilex and other specialty companies |
Reformulated or differentiated celecoxib products |
What patent litigation and settlements affected generic entry?
Celecoxib litigation followed the standard Hatch-Waxman pattern: generic companies filed ANDAs with Paragraph IV certifications, Pfizer sued to protect the listed patent, and settlement or litigation outcomes determined the timing of commercial entry.
The principal economic effect of settlement agreements was timing. A settlement that permits entry before the full patent expiration can preserve some brand value while giving the generic challenger an agreed launch date. Once several generic suppliers enter, price erosion generally accelerates.
Public records and company disclosures should be reviewed on a product-by-product basis because the settlement terms can differ by dosage strength, manufacturer, authorized-generic arrangement, and jurisdiction. The central outcome for celecoxib was clear: U.S. generic entry occurred near the end of the core patent term, and the market did not remain protected by a durable compound-level barrier.
How strong is the current celecoxib patent estate?
The current patent estate is weak for standard celecoxib capsules and stronger only for differentiated products with distinct formulation or indication claims.
| Patent category |
Current strength |
Commercial significance |
| Core chemical entity |
Low after expiry |
Does not block ordinary generic capsules |
| Standard capsule formulation |
Low to moderate |
Depends on product-specific claims, if any |
| Oral solution |
Moderate for product-specific protection |
May support differentiated acute-migraine positioning |
| Method of use |
Variable |
Narrow claims can be difficult to enforce broadly |
| Manufacturing process |
Variable |
Can raise technical barriers but rarely blocks all supply |
| Regulatory exclusivity |
Limited for original product |
New products may obtain separate exclusivity periods |
A formulation patent can be commercially useful without creating a second Celebrex-scale franchise. It must support superior adherence, faster onset, improved tolerability, or a reimbursement advantage. Without those attributes, prescribers and payers can favor inexpensive generic capsules.
How does celecoxib compare with competing NSAIDs?
Celecoxib competes in a broad market that includes generic ibuprofen, naproxen, diclofenac, meloxicam, etodolac, and, outside the United States, etoricoxib. The drug’s main differentiation is COX-2 selectivity, not price.
| Drug |
Selectivity |
Main commercial advantage |
Main limitation |
| Celecoxib |
COX-2 selective |
Lower gastrointestinal ulcer risk than many nonselective NSAIDs |
Cardiovascular, renal, and cost concerns |
| Naproxen |
Nonselective |
Low generic cost and broad use |
Gastrointestinal toxicity |
| Ibuprofen |
Nonselective |
Very low cost and extensive availability |
Shorter duration; gastrointestinal and renal risks |
| Meloxicam |
Preferential COX-2 activity |
Once-daily dosing and low generic cost |
Class safety risks |
| Diclofenac |
Relatively COX-2 preferential |
Strong analgesic and anti-inflammatory effect |
Cardiovascular and hepatic concerns |
| Etoricoxib |
COX-2 selective |
Broad international use and once-daily dosing |
Not approved in the U.S.; cardiovascular concerns |
Celecoxib’s clinical value is most defensible when gastrointestinal risk, dosing convenience, and treatment response justify selection over cheaper nonselective NSAIDs. PRECISION trial results indicated that moderate-dose celecoxib was noninferior to naproxen and ibuprofen for cardiovascular safety in the studied arthritis population, while showing fewer gastrointestinal events than the comparators.[8] The findings support clinical use but do not eliminate the boxed cardiovascular warning.
What FDA regulatory factors influence celecoxib sales?
FDA regulation affects celecoxib demand through labeling, generic approvals, safety communications, and new formulation approvals.
Key regulatory factors include:
- The boxed warning for cardiovascular and gastrointestinal risks.
- Restrictions and clinical caution in patients with cardiovascular disease, renal impairment, or gastrointestinal risk.
- Bioequivalence requirements for generic capsules.
- Labeling differences between conventional celecoxib and newer products such as Elyxyb.
- Prescription-only status and payer controls.
- Post-market pharmacovigilance affecting long-term prescribing.
Celecoxib has no biosimilar issue because it is a small-molecule drug, not a biologic. The relevant competitive pathway is ANDA approval, not the 351(k) biosimilar pathway.
What generic launch risks exist for celecoxib?
Generic launch risk is high for any new conventional capsule entrant because the market already has multiple approved suppliers. The principal risks are commercial rather than patent-related.
Price erosion
Each additional supplier can reduce average selling prices and pharmacy reimbursement. The first entrants may obtain stronger margins, but later entrants typically compete in a low-margin environment.
Supply-chain concentration
Generic NSAID markets can experience shortages when active pharmaceutical ingredient production, facility compliance, or manufacturing capacity is concentrated among a small number of suppliers. A reliable manufacturer can gain share even without the lowest price.
Formulary displacement
Payers can substitute naproxen, meloxicam, or ibuprofen where clinical guidelines permit. A generic celecoxib supplier must compete against both other celecoxib products and therapeutic alternatives.
Regulatory execution
ANDA approval, manufacturing inspections, labeling compliance, and post-approval quality requirements can delay or disrupt market entry. Formulation-specific products face greater technical and regulatory complexity than standard capsules.
What licensing deals and commercial partnerships affect celecoxib?
The major commercial transition involved Pfizer’s ownership and commercialization of Celebrex after its acquisition of Pharmacia. Later activity shifted toward specialty commercialization and reformulation rather than licensing the original compound.
Elyxyb illustrates the newer model: a differentiated celecoxib product can be developed and commercialized separately from the mature generic capsule market.[6] Such products may support licensing, co-promotion, or acquisition interest if they show faster onset, improved convenience, or a defined specialty-market position.
The commercial value of a celecoxib licensing deal depends on whether the asset has enforceable formulation or method-of-use protection. Rights to generic capsules have limited value unless tied to manufacturing scale, regional access, or a supply agreement.
What is the revenue outlook for celecoxib?
The conventional celecoxib capsule market should remain a stable-volume, low-growth generic business. Revenue growth is unlikely to come from broad pricing power. It is more likely to come from:
- Higher prescription volume in aging populations.
- Expanded use in chronic osteoarthritis and rheumatoid arthritis.
- Supply disruptions affecting competitors.
- Geographic expansion in markets with limited generic penetration.
- Specialty formulations such as oral solutions.
- Contract manufacturing and private-label supply.
For Pfizer, Celebrex is no longer a major growth asset. Its value lies in residual branded prescriptions, established physician recognition, and any authorized-generic or regional commercial rights. Pfizer’s recent reporting structure does not separately disclose a current global Celebrex revenue figure, so brand-specific revenue should not be inferred from Pfizer’s aggregate product sales.[3]
For generic manufacturers, the opportunity is operational. The strongest positions are likely to belong to companies with low-cost API access, multiple manufacturing sites, reliable quality records, and established pharmacy distribution.
How does geographic coverage affect market potential?
The United States is a mature generic market with low unit pricing and extensive therapeutic substitution. Europe and other developed markets also have broad generic access, although reimbursement systems and reference pricing vary by country.
Emerging markets can offer better unit growth but present lower prices, local manufacturing requirements, registration costs, and fragmented distribution. Celecoxib adoption depends on physician familiarity, cardiovascular-risk perceptions, reimbursement, and the availability of cheaper NSAIDs.
A company seeking geographic growth should evaluate country-specific patent status, regulatory registration, local procurement rules, pharmacovigilance obligations, and the competitive position of etoricoxib and other COX-2 inhibitors.
Key Takeaways
- Celecoxib is a mature COX-2 selective NSAID with durable demand but limited pricing power.
- Pfizer’s Celebrex franchise declined sharply after U.S. generic entry around late 2014 and 2015.
- U.S. Patent No. 5,466,823 was the principal compound patent and expired in December 2014.
- Standard celecoxib capsules face substantial generic competition and have weak remaining patent protection.
- Formulation and method-of-use patents can protect differentiated products but do not recreate broad compound exclusivity.
- Elyxyb provides a separate oral-solution and migraine-treatment positioning.
- The product has no biosimilar risk because celecoxib is a small molecule.
- Future market value is concentrated in generic manufacturing efficiency, supply reliability, specialty formulations, and geographic expansion.
- Cardiovascular and gastrointestinal safety warnings remain central to prescribing and reimbursement decisions.
FAQs
Is celecoxib still profitable after generic entry?
Yes, but profitability is concentrated in efficient generic manufacturing and differentiated formulations rather than in branded pricing. Pfizer’s original brand economics were materially reduced after generic entry.
Can a generic manufacturer launch celecoxib without patent litigation?
A manufacturer must address listed patents through the appropriate ANDA certification. If it files a Paragraph IV certification, the reference sponsor may initiate Hatch-Waxman litigation. The commercial launch date depends on patent status, settlement terms, and regulatory approval.
Does celecoxib have a biosimilar competitor?
No. Celecoxib is a chemically synthesized small molecule. Competitors enter through the generic-drug pathway, primarily ANDAs, rather than through biosimilar applications.
Is Elyxyb protected by the same patents as Celebrex?
Not necessarily. Elyxyb is a distinct oral-solution product with its own formulation, indication, regulatory, and patent considerations. The expired core compound patent does not by itself determine the protection available to the oral solution.
Which drug is the closest commercial competitor to celecoxib?
Generic meloxicam is a close commercial competitor because it is inexpensive, widely prescribed, and offers convenient dosing. Naproxen and ibuprofen remain broader low-cost substitutes, while etoricoxib is a closer COX-2 competitor in markets where it is approved.
References
- U.S. Food and Drug Administration. (2023). Celecoxib prescribing information. FDA.
- Pfizer Inc. (2004-2015). Annual reports and Form 10-K filings. Pfizer.
- Pfizer Inc. (2023). Annual report and Form 10-K. Pfizer.
- U.S. Patent and Trademark Office. (1995). U.S. Patent No. 5,466,823: Substituted pyrazolyl benzenes.
- U.S. Food and Drug Administration. (2014-2015). Approved drug products with therapeutic equivalence evaluations and abbreviated new drug application records for celecoxib. FDA.
- U.S. Food and Drug Administration. (2020). Elyxyb approval and prescribing information. FDA.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. FDA.
- Nissen, S. E., Yeomans, N. D., Solomon, D. H., et al. (2016). Cardiovascular safety of celecoxib, naproxen, or ibuprofen for arthritis. New England Journal of Medicine, 375(26), 2519-2529.