Last updated: September 7, 2026
Terbutaline sulfate is a mature, largely generic beta-2 adrenergic agonist with limited commercial growth potential. Its US market is driven by low-cost tablets and injectable products, hospital demand, supply continuity, and regulatory restrictions on obstetric use rather than by patent-protected innovation. Standalone revenue is not publicly disclosed because sales are distributed across generic manufacturers and product-level financial reporting is generally unavailable.
What is the current market position of terbutaline sulfate?
Terbutaline sulfate is an established bronchodilator used primarily for bronchospasm associated with asthma and other obstructive airway conditions. It is marketed in several dosage forms, including oral tablets, subcutaneous injection, and, in certain jurisdictions, inhaled or nebulized products.
| Market factor |
Current position |
| Active ingredient |
Terbutaline sulfate |
| Drug class |
Short-acting beta-2 adrenergic agonist |
| Primary use |
Bronchodilation |
| Commercial status |
Mature generic market |
| US brand |
Brethine, no longer a major marketed brand |
| Key dosage forms |
Tablets and injection |
| Patent status |
Core composition and use protection expired |
| Biosimilar exposure |
None; terbutaline is a small molecule |
| Generic competition |
High |
| Revenue transparency |
Low; no reliable standalone global sales disclosure |
| Growth profile |
Flat to declining in routine outpatient use, with resilient hospital demand |
Terbutaline competes with albuterol, levalbuterol, epinephrine, and other bronchodilators. Albuterol has stronger US prescribing familiarity and broader inhaler availability. Terbutaline retains utility where injectable or systemic beta-2 agonist administration is clinically preferred or where formulary and supply conditions support its use.
How large is the terbutaline sulfate market?
No authoritative public source reports a standalone global market value for terbutaline sulfate. Generic companies generally report revenue by broader categories such as respiratory products, injectables, or North American generics rather than by individual mature molecules.
The commercial market is likely divided into four segments:
- US generic tablets.
- US hospital and emergency injectable products.
- International branded and generic respiratory products.
- Limited obstetric use despite regulatory restrictions and warnings.
The injectable segment has greater commercial value per unit than oral tablets but remains a small product category relative to high-volume inhaled bronchodilators. Hospital contracts, government tenders, and wholesaler inventory decisions have a disproportionate effect on annual sales.
What drives demand?
Demand is influenced by:
- Asthma and chronic obstructive pulmonary disease prevalence.
- Emergency-department and inpatient treatment protocols.
- Availability and pricing of albuterol and other alternatives.
- Hospital formulary decisions.
- Product shortages involving competing bronchodilators.
- Regulatory controls on obstetric use.
- Manufacturer participation in low-margin generic contracts.
Routine outpatient demand has limited growth potential because many prescribers favor inhaled albuterol-based therapies. Terbutaline injection can benefit from temporary shortages of alternative products, but those gains are usually episodic rather than structural.
What is the financial trajectory for terbutaline sulfate?
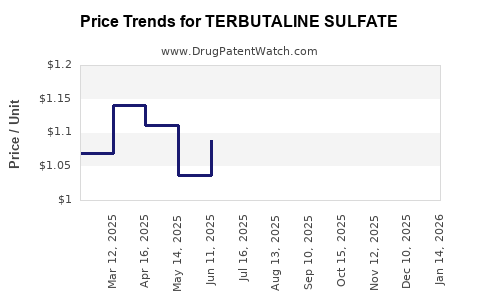
The financial trajectory is that of a mature, low-price generic: declining nominal pricing, stable or declining unit demand, and intermittent revenue increases caused by shortages or supplier exits.
| Period |
Financial pattern |
Principal drivers |
| 1970s-1990s |
Brand-led commercial phase |
Brethine and international branded products |
| 2000s |
Generic conversion |
Patent expiry, multiple suppliers, price erosion |
| 2010s |
Mature low-margin market |
Strong generic competition and obstetric-use restrictions |
| 2020-2022 |
Volatile hospital demand |
COVID-era supply disruption, hospital procurement changes |
| 2023 onward |
Stable-to-low-growth profile |
Generic pricing pressure, product continuity, episodic shortages |
The most likely revenue pattern is:
- Flat or declining tablets revenue.
- Greater volatility in sterile injectable sales.
- Temporary price increases during shortages.
- Limited ability to sustain premium pricing without differentiated supply, packaging, or manufacturing reliability.
- No meaningful patent-driven revenue period.
Generic manufacturers can still generate acceptable returns when they have efficient API sourcing, low-cost production, established hospital contracts, or limited competition in a dosage form. The product is unlikely to support significant investment in new clinical development absent a specialized delivery technology or a new indication.
When does terbutaline sulfate lose exclusivity?
Terbutaline sulfate lost meaningful market exclusivity decades ago. The active pharmaceutical ingredient is an old small molecule, and the core composition and traditional bronchodilator-use patents have expired.
There is no current exclusivity period comparable to:
- New chemical entity exclusivity.
- Orphan-drug exclusivity.
- Biologic reference-product exclusivity.
- Modern branded inhaler-device exclusivity.
Any remaining protection would likely relate to a specific formulation, delivery device, manufacturing process, or combination product rather than to terbutaline sulfate itself.
What patents protect terbutaline sulfate?
The core terbutaline sulfate molecule is not protected by a commercially significant US patent estate. Legacy patent protection covered the compound and pharmaceutical uses during the original branded-product period. Those rights expired long before the current generic market developed.
| Patent category |
Commercial relevance |
| Compound patents |
Expired |
| Salt or basic formulation patents |
Expired or no longer commercially material |
| Traditional asthma-use patents |
Expired |
| Oral tablet patents |
No meaningful current exclusivity |
| Injectable formulation patents |
No broad, molecule-level exclusivity identified |
| Device patents |
Potentially relevant only to a particular product or jurisdiction |
| Manufacturing patents |
Possible in isolated cases, but not a broad barrier to generic entry |
A patent covering a manufacturing process generally does not prevent competition if manufacturers can use a non-infringing process. The strongest remaining barriers are therefore operational rather than legal.
How strong is the patent estate for terbutaline sulfate?
The patent estate is weak from an originator-defense perspective. It does not provide a credible basis for extended US market exclusivity, premium pricing, or broad protection against ANDA competition.
Commercial strength depends more on:
- Sterile manufacturing capacity.
- API qualification.
- FDA inspection history.
- Hospital contracting.
- Product availability.
- NDC-level competition.
- Ability to maintain supply during shortages.
What is the FDA regulatory status of terbutaline sulfate?
FDA-approved terbutaline products are regulated as prescription drugs. Tablets and injectable products have been used for bronchodilation. The FDA has not approved terbutaline for prolonged prevention of preterm labor.
In 2011, FDA warned against prolonged use of terbutaline in pregnant women for prevention or treatment of preterm labor because of serious maternal cardiovascular risks, including arrhythmias and death. FDA stated that injectable terbutaline should not be used for prevention or prolonged treatment of preterm labor and that oral terbutaline should not be used for acute or prolonged obstetric treatment [1].
The warning materially reduced the commercial and clinical attractiveness of obstetric use. Short-term, monitored use in selected clinical circumstances may continue under physician judgment, but that use does not create a patent or exclusivity opportunity.
What is the Orange Book status of terbutaline sulfate?
The FDA Orange Book lists approved drug products and relevant patent and exclusivity information for eligible products. For a mature generic ingredient such as terbutaline sulfate, the key commercial conclusion is that current competition is based on abbreviated approvals rather than active originator patent protection.
The Orange Book does not provide a consolidated market-share view. It also does not capture every international patent, process patent, device right, or regulatory barrier affecting a product.
The relevant US regulatory characteristics are:
- No active new chemical entity exclusivity.
- No practical originator monopoly.
- Generic products approved through ANDA pathways.
- Limited commercial relevance of legacy branded listings.
- No biosimilar framework because terbutaline is not a biologic.
Are there Paragraph IV challenges involving terbutaline sulfate?
Paragraph IV litigation is unlikely to be a material current market issue for terbutaline sulfate. The molecule is already broadly generic, and the commercial opportunity is too limited to support the type of high-value patent challenge common in blockbuster markets.
A Paragraph IV certification can still arise for a specific listed product, formulation, or device-linked product. That event would concern the challenged reference product rather than the entire terbutaline sulfate market.
The more relevant risks are ordinary ANDA competition, product discontinuation, manufacturing delays, and procurement changes. Public FDA and federal court records do not indicate a major current Paragraph IV campaign centered on conventional terbutaline sulfate tablets or injection.
Which companies compete in the terbutaline sulfate market?
Competition is fragmented across generic drug manufacturers, contract manufacturers, and regional suppliers. The precise supplier set changes by dosage form, country, NDC, and procurement contract.
The competitive landscape generally includes:
- US generic manufacturers supplying tablets.
- Injectable specialists supplying hospitals.
- International companies marketing Bricanyl or generic equivalents.
- Contract manufacturers supplying private-label and institutional products.
- Regional distributors serving government and hospital tenders.
The market does not have a single dominant global terbutaline franchise comparable to a branded respiratory product. Supplier concentration can nevertheless become high at the dosage-form level, particularly for sterile injection.
How does terbutaline sulfate compare with albuterol?
| Factor |
Terbutaline sulfate |
Albuterol |
| Market maturity |
Mature generic |
Mature generic |
| Dominant use |
Bronchodilation, selected systemic use |
Broad outpatient and emergency bronchodilation |
| Inhaler penetration |
Lower in the US |
Much higher |
| Injectable role |
More commercially relevant than inhaled terbutaline |
Broad emergency use through multiple presentations |
| Prescriber familiarity |
Lower |
High |
| Patent opportunity |
Minimal |
Device and formulation patents may remain product-specific |
| Pricing power |
Low |
Low for generics, higher for selected devices |
| Growth outlook |
Flat or declining |
Larger and more resilient market |
Albuterol has a larger addressable market and stronger outpatient brand recognition. Terbutaline's relative advantage is availability in systemic presentations and selected hospital applications.
What formulation patents protect terbutaline sulfate?
No broadly important formulation patent appears to protect conventional terbutaline sulfate tablets or injection as a class. A particular inhalation device, extended-release formulation, combination product, or manufacturing method could have separate rights, but those rights would not automatically cover standard generic products.
Potential technical differentiation includes:
- Modified-release oral dosage forms.
- Inhalation delivery systems.
- Nebulizer formulations.
- Ready-to-use injectable presentations.
- Stability-enhanced sterile products.
- Combination respiratory products.
These opportunities face limited commercial upside because terbutaline is inexpensive and competes with established alternatives. The development economics favor incremental manufacturing or delivery improvements rather than major clinical programs.
What manufacturing and supply barriers affect terbutaline sulfate?
Manufacturing barriers are more important than patent barriers. The main risks differ by dosage form.
Tablets
Tablet production has low technical complexity and multiple potential manufacturers. Price competition is intense, and suppliers may exit when net prices fall below sustainable levels.
Injectable products
Injectables require:
- Sterile formulation and filling.
- Validated aseptic processing.
- Container-closure integrity.
- Stability data.
- FDA-compliant manufacturing systems.
- Reliable API and packaging supply.
These requirements reduce the number of qualified suppliers. A manufacturer with an approved sterile line can obtain temporary pricing leverage during a shortage, although that leverage usually declines when competitors return.
API supply
Terbutaline sulfate API is a mature commodity. The principal risks are supplier qualification, quality deviations, production interruptions, and regulatory inspection findings rather than scarcity caused by intellectual property.
What generic entry risks exist for terbutaline sulfate?
Generic entry risk is already realized for conventional terbutaline sulfate products. The key commercial threats are therefore not future patent expiry but further erosion of supplier economics.
| Risk |
Probability |
Commercial effect |
| New tablet entrant |
Medium |
Further price erosion |
| New injectable entrant |
Low to medium |
Reduced hospital contract share |
| Supplier discontinuation |
Medium |
Temporary price and availability volatility |
| API quality event |
Low to medium |
Possible shortage or recall |
| Albuterol substitution |
High |
Limits demand growth |
| New patent barrier |
Low |
Unlikely to affect conventional products |
| Regulatory restriction expansion |
Low to medium |
Could reduce obstetric-related use |
Generic launch economics are weak unless the entrant has a differentiated channel, a supply contract, or a shortage-based opportunity. A new entrant would face low prices, established competitors, and limited clinical differentiation.
What patent litigation or settlement agreements affect terbutaline sulfate?
No major current patent litigation or settlement agreement appears to shape the conventional US terbutaline sulfate market. Historical brand-to-generic disputes, if any, have little remaining commercial significance because the underlying exclusivity period has ended.
The market is more exposed to:
- FDA manufacturing enforcement.
- Product recalls.
- Hospital contracting disputes.
- Supply and shortage investigations.
- Antitrust scrutiny involving generic pricing or coordinated conduct.
The absence of meaningful litigation does not mean the product has no regulatory risk. It means legal competition is no longer the primary determinant of market value.
Is there biosimilar risk for terbutaline sulfate?
There is no biosimilar risk because terbutaline sulfate is a chemically synthesized small molecule, not a biologic. Competition occurs through generic-drug pathways, principally ANDAs in the United States.
This distinction matters commercially:
- No biologic reference-product exclusivity applies.
- No biosimilar interchangeability designation applies.
- Manufacturing similarity is assessed under small-molecule generic standards.
- Price competition can begin once an ANDA is approved and commercialized.
What licensing deals involve terbutaline sulfate?
Terbutaline sulfate has limited licensing appeal. The active ingredient is generic, and the product lacks a substantial patent moat. Licensing opportunities would be most plausible for:
- Regional commercialization rights.
- Hospital distribution.
- Private-label supply.
- Inhalation-device technology.
- Combination respiratory products.
- Specialized sterile manufacturing.
Large, publicly disclosed licensing transactions centered specifically on terbutaline sulfate are not a meaningful feature of the market. Commercial arrangements are more likely to be supply, distribution, or contract-manufacturing agreements than asset acquisitions.
What is the geographic market outlook?
The United States is a mature generic market with limited pricing power. International markets vary more widely because terbutaline remains marketed under branded names, including Bricanyl in some jurisdictions.
| Region |
Market outlook |
| United States |
Generic, low-price, hospital-sensitive |
| Europe |
Country-specific reimbursement and branded/generic mix |
| United Kingdom |
Established Bricanyl and generic presence, subject to local prescribing |
| Emerging markets |
Potentially stronger unit growth but lower prices and variable regulation |
| Hospital tender markets |
Volume-driven, vulnerable to supplier concentration |
| Private retail markets |
Competitive and increasingly exposed to alternative bronchodilators |
Geographic growth is more likely to come from expanded access in emerging markets than from premium pricing in the US or Western Europe.
Key Takeaways
- Terbutaline sulfate is a mature generic bronchodilator with no meaningful remaining molecule-level exclusivity.
- Standalone global revenue is not publicly reported.
- The financial trajectory is flat to declining, with episodic increases during injectable shortages.
- Tablets face intense price competition and substitution by albuterol and other bronchodilators.
- Injectable products have higher operational barriers because of sterile manufacturing requirements.
- The FDA has restricted prolonged obstetric use because of serious maternal cardiovascular risks.
- Paragraph IV litigation, biosimilar competition, and major licensing transactions are not central market drivers.
- Supply reliability, hospital tenders, API quality, and sterile manufacturing capacity determine commercial performance.
- The strongest potential for value lies in differentiated delivery systems, private-label supply, or reliable injectable manufacturing rather than in new molecule patents.
FAQs
Does terbutaline sulfate have patent protection in the United States?
The core molecule and conventional bronchodilator uses are no longer protected by commercially meaningful US patents. Specific delivery systems or formulations could have separate rights.
Is terbutaline sulfate still profitable for generic manufacturers?
It can be profitable when supplied through hospital contracts or during shortages, but routine tablets are generally low-margin. Injectable products may offer better economics because qualified sterile suppliers are fewer.
Can terbutaline sulfate be used to stop preterm labor?
FDA has not approved terbutaline for prolonged prevention or treatment of preterm labor. FDA warned of serious maternal cardiovascular risks associated with obstetric use [1].
What drug most directly competes with terbutaline sulfate?
Albuterol is the most important US competitor because it has broader outpatient use, stronger prescriber familiarity, and extensive inhaled and emergency presentations.
Is terbutaline sulfate a good target for pharmaceutical licensing?
The conventional generic product has limited licensing value. The strongest opportunities are regional distribution, hospital supply, sterile manufacturing, or differentiated inhalation and delivery technologies.
References
-
U.S. Food and Drug Administration. (2011, February 17). FDA drug safety communication: New warnings against use of terbutaline to treat preterm labor. https://www.fda.gov/drugs/drug-safety-and-availability/fda-drug-safety-communication-new-warnings-against-use-terbutaline-treat-preterm-labor
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
-
National Library of Medicine. (2024). DailyMed: Terbutaline sulfate prescribing information. https://dailymed.nlm.nih.gov/dailymed/
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (2024). Drug shortages database. https://www.accessdata.fda.gov/scripts/drugshortages/