Last updated: August 28, 2026
Ibandronate sodium is a mature bisphosphonate used to prevent and treat postmenopausal osteoporosis. Its commercial profile is defined by long-expired or expiring small-molecule exclusivity, extensive generic competition, low manufacturing complexity relative to biologics, and declining branded revenue. The oral 150 mg monthly tablet and intravenous injection remain commercially relevant, but the product has shifted from an innovation-driven market to a price-sensitive generic market.
What is ibandronate sodium and how is it used?
Ibandronate sodium is the sodium salt of ibandronic acid, a nitrogen-containing bisphosphonate that inhibits osteoclast-mediated bone resorption. It was developed for osteoporosis treatment and marketed in the United States under the brand name Boniva by Roche and Genentech.
The principal dosage forms are:
| Dosage form |
Typical strength |
Administration |
Main market |
| Oral tablet |
150 mg |
Once monthly |
Retail and mail-order pharmacy |
| Intravenous injection |
3 mg/3 mL |
Every three months |
Physician office and outpatient care |
The U.S. label indicates that the tablet is administered at least 60 minutes before food, beverages other than water, or other oral medicines. The injection is administered by a healthcare professional every three months and requires renal and calcium-related precautions.[1]
Ibandronate competes with alendronate, risedronate, and zoledronic acid. Its monthly oral dosing and quarterly intravenous schedule were designed to differentiate it from daily or weekly oral bisphosphonates. That convenience advantage did not prevent substantial generic erosion after patent and regulatory protections weakened.
When did ibandronate sodium lose exclusivity?
U.S. market exclusivity ended in stages rather than on one date.
| Milestone |
Approximate period |
Commercial effect |
| U.S. approval of Boniva tablets |
2003 |
Originator launch |
| U.S. approval of Boniva injection |
2005 |
Expansion into physician-administered therapy |
| Generic litigation and ANDA activity |
Late 2000s to early 2010s |
Accelerated generic entry risk |
| First broad generic tablet competition |
Early 2010s |
Rapid price and share erosion |
| Mature generic injection market |
2010s onward |
Lower prices and fragmented supply |
The FDA approved Boniva tablets in 2003 and the injection in 2005.[1] By the early 2010s, generic ibandronate sodium products had entered or were positioned to enter the U.S. market. The precise commercial impact varied by dosage form, patent certification, settlement terms, and individual ANDA approval timing.
Unlike a biologic, ibandronate sodium did not require a biosimilar pathway. Generic manufacturers could use the abbreviated new drug application, or ANDA, pathway by demonstrating pharmaceutical equivalence and bioequivalence to the reference product.
What patents protected Boniva and ibandronate sodium?
Ibandronate sodium was protected by composition, pharmaceutical formulation, treatment-method, and manufacturing patents. The principal commercial patent estate was developed before the product reached the market and was subject to the limited statutory term applicable to small-molecule medicines.
Representative historical U.S. patent families associated with ibandronate and Boniva included patents covering:
- Ibandronic acid and related bisphosphonate compounds.
- Pharmaceutical salts and compositions.
- Oral dosage forms.
- Methods for treating osteoporosis.
- Dosing regimens involving intermittent or monthly administration.
- Injectable formulations and administration protocols.
Patent term depended on the earliest effective nonprovisional filing date, patent-term adjustment, terminal disclaimers, and any patent-term extension. FDA Orange Book listings, rather than the existence of a patent alone, determined the principal regulatory patent barriers for an ANDA applicant.[2]
The commercial patent estate is now mature. Core composition and use patents have generally expired or ceased to be meaningful barriers to ordinary generic entry. Any remaining patent issue would more likely involve a narrow formulation, manufacturing process, dosage regimen, or jurisdiction-specific right than the basic active ingredient.
What is the Orange Book status of ibandronate sodium?
The Orange Book identifies approved reference-listed drugs and associated patents and exclusivity information. Boniva is the historical reference product for U.S. ibandronate sodium tablets and injection.[2]
The current competitive significance of Orange Book listings is limited because:
- The active ingredient is an established small molecule.
- The major commercial dosage forms have been genericized.
- Any remaining listed patents must be evaluated for expiration, delisting, litigation, or relevance to a specific strength and dosage form.
- A generic applicant can use Paragraph III, Paragraph IV, or other applicable certifications depending on the patent record.
A Paragraph IV certification states that a listed patent is invalid, unenforceable, or will not be infringed by the proposed generic product. A first filer may receive 180-day generic exclusivity if the statutory conditions are satisfied. That exclusivity can materially affect early market pricing, but it does not protect the originator from all generic competition indefinitely.
Which companies have challenged or competed with Boniva?
The competitive field has included large generic manufacturers and specialty pharmaceutical suppliers. Companies that have marketed or pursued generic bisphosphonate products have included major ANDA manufacturers such as Teva, Mylan, Sandoz, Sun Pharmaceutical, and other U.S. and international suppliers, depending on dosage form and market period.
Competition has occurred across two channels:
Retail oral tablets
The 150 mg tablet is relatively straightforward to manufacture. Multiple suppliers can compete through pharmacy benefit managers, wholesalers, chain pharmacies, and mail-order channels. Price declines are typically sharper when several suppliers are approved and interchangeable at the pharmacy level.
Physician-administered injection
The 3 mg/3 mL injection has more operational requirements. Manufacturers must manage sterile production, container closure, quality control, and distribution to physician practices. These factors create greater manufacturing and supply-chain risk than the oral tablet, but they do not create the level of technical barrier associated with complex biologics.
How strong is the ibandronate sodium patent estate?
The patent estate is weak as a current broad-market exclusivity platform and stronger only for narrow, claim-specific positions.
| Patent category |
Current strategic strength |
| Core compound patents |
Low; historical protection has expired |
| Oral tablet composition |
Low to moderate for narrow claims |
| Monthly dosing methods |
Low where claims are expired or vulnerable |
| Intravenous formulation |
Moderate only if an unexpired, enforceable claim remains |
| Manufacturing processes |
Moderate for process-specific enforcement |
| Trade secrets |
Limited commercial importance for a mature small molecule |
| Regulatory exclusivity |
None of material current significance |
The absence of a biologic manufacturing platform also reduces the value of process secrecy. Generic companies can often reproduce the active pharmaceutical ingredient and finished dosage form using established chemistry and quality systems.
Patent strength should therefore be assessed by product presentation, jurisdiction, and claim scope. A patent that covers a particular injection formulation may not block an oral tablet. A method-of-use patent may not prevent a generic from selling the product for an approved indication if the applicant uses an appropriate label strategy.
What formulation patents protect ibandronate sodium?
Formulation protection has historically focused on stability, dosage form, administration frequency, and injectable delivery.
The major commercial formulation distinctions are:
- Monthly oral administration.
- Low-dose tablet delivery with fasting requirements.
- Sterile intravenous injection.
- Container and packaging requirements for injectable use.
- Stability and impurity-control specifications.
Formulation patents have limited defensive value once the market contains multiple therapeutically interchangeable products. They can still delay a specific generic formulation if the claims are valid and enforceable, but they rarely preserve the original brand price after the active ingredient becomes broadly available.
The injection can retain somewhat stronger commercial protection because sterile manufacturing, regulatory compliance, and institutional purchasing create practical barriers. Those barriers are commercial rather than necessarily patent-based.
What patent litigation affected ibandronate sodium?
Ibandronate sodium followed the standard litigation pattern for branded small-molecule products. Generic applicants could file ANDAs with Paragraph IV certifications against relevant Orange Book patents, prompting infringement litigation under the Hatch-Waxman framework.
The key business consequences were:
- Potential 30-month stays of ANDA approval after timely patent litigation.
- Possible 180-day exclusivity for a qualifying first Paragraph IV filer.
- Settlement agreements that could establish a negotiated generic launch date.
- Earlier competition if patents were invalidated, not infringed, or removed from the Orange Book.
- Product-specific outcomes for tablets and injection.
Publicly available commercial information does not indicate an ongoing, market-defining U.S. patent dispute comparable to litigation involving high-revenue oncology, autoimmune, or antiviral products. The principal litigation risk is historical or product-specific rather than a current block on the entire ibandronate market.
How did ibandronate sodium revenue change over time?
Boniva generated meaningful revenue during the branded osteoporosis market’s expansion in the mid-2000s. Revenue declined as generic competition, safety scrutiny, formulary pressure, and competing bisphosphonates reduced brand demand.
The financial trajectory can be divided into four phases:
Launch and adoption
Boniva entered a market dominated by established weekly and daily bisphosphonates. Monthly dosing provided a clear adherence and convenience proposition. Roche and Genentech promoted the product through primary-care, gynecology, and osteoporosis channels.
Peak branded sales
The product reached its strongest commercial period before broad generic erosion. Public company reporting often grouped Boniva or Bonviva with regional product categories, which limits precise global revenue reconstruction.[3]
Generic erosion
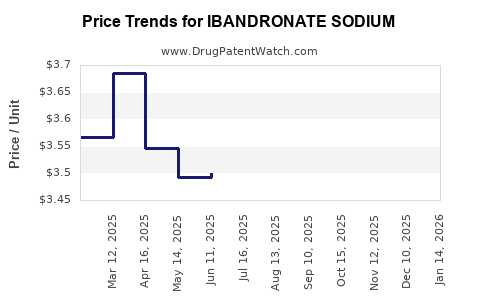
Once generic ibandronate became available, payer substitution and lower pharmacy reimbursement reduced brand volume and net price. Oral tablet revenue was particularly exposed because the product was easy to substitute at the pharmacy.
Mature generic market
Current revenue is distributed among generic manufacturers, wholesalers, pharmacies, institutional buyers, and specialty suppliers. Roche does not report ibandronate as a major standalone growth product in current corporate reporting. The market has shifted from brand promotion to supply reliability, contract pricing, channel access, and regulatory compliance.[4]
What is the current market outlook for ibandronate sodium?
Ibandronate sodium is a low-growth, mature generic market. The principal demand drivers are:
- Aging populations.
- Ongoing osteoporosis diagnosis.
- Fracture prevention programs.
- Continued use of oral monthly therapy where adherence is acceptable.
- Use of injectable therapy when oral administration is unsuitable.
The principal constraints are:
- Generic price erosion.
- Competition from alendronate, risedronate, and zoledronic acid.
- Use of denosumab and anabolic osteoporosis therapies in higher-risk patients.
- Safety and administration restrictions associated with bisphosphonates.
- Treatment discontinuation and medication persistence problems.
- Payer preference for lower-cost weekly or yearly alternatives.
Ibandronate has a narrower fracture-evidence profile than some competing bisphosphonates. The U.S. label supports reduction of vertebral fracture risk, while evidence for nonvertebral fracture reduction is more limited.[1] That distinction affects guideline positioning and prescriber choice.
How does ibandronate compare with competing osteoporosis drugs?
| Product |
Administration |
Competitive position |
Patent and market status |
| Ibandronate |
Monthly oral or quarterly IV |
Convenience-oriented bisphosphonate |
Mature generic |
| Alendronate |
Weekly oral or periodic IV |
Low-cost first-line option |
Mature generic |
| Risedronate |
Weekly or monthly oral |
Alternative oral bisphosphonate |
Mature generic |
| Zoledronic acid |
Annual IV |
Strong adherence and persistence profile |
Mature generic |
| Denosumab |
Six-month injection |
Higher-cost branded and biosimilar-linked segment |
Biologic competition |
| Teriparatide and abaloparatide |
Daily injection |
High-risk or anabolic therapy |
Generic and follow-on competition |
| Romosozumab |
Monthly injection |
High-risk osteoporosis segment |
Branded biologic |
Ibandronate’s strongest differentiator is administration frequency relative to weekly oral therapy. Its weakest commercial factor is that yearly zoledronic acid can offer greater convenience and broader fracture-prevention positioning for selected patients.
What generic launch risks exist for ibandronate sodium?
Generic launch risk is high for oral ibandronate and moderate to high for injection.
Oral tablet risk
A new ANDA entrant can intensify price competition quickly if the product is therapeutically equivalent and obtains broad pharmacy substitution. The most important variables are:
- Number of approved suppliers.
- First-filer status.
- Wholesale acquisition cost.
- Rebate and purchasing contracts.
- Pharmacy benefit manager placement.
- Supply continuity.
Injection risk
Injection entrants face higher costs and manufacturing controls. Risks include:
- Sterile manufacturing capacity.
- Inspection and compliance outcomes.
- Injectable supply shortages.
- Hospital and clinic purchasing contracts.
- Administration reimbursement.
- Product-specific stability and container requirements.
These factors can preserve margins temporarily, but they do not create durable originator-like pricing power.
What licensing deals and commercial partnerships affect ibandronate?
Ibandronate has been commercialized through regional licensing, distribution, and generic supply arrangements. Roche and Genentech historically controlled the Boniva brand in major markets, while generic manufacturers supplied products after loss of exclusivity.
Unlike newer specialty medicines, ibandronate has limited current licensing value. The asset is unlikely to attract a large strategic deal based on innovation or exclusivity. Potential transaction value would depend on:
- Access to regulated markets.
- Existing ANDA approvals.
- Manufacturing capacity.
- Injectable production capability.
- Hospital contracts.
- Geographic supply rights.
- Portfolio synergies with other osteoporosis products.
The most credible commercial opportunities are regional generic acquisitions, contract manufacturing, and portfolio consolidation rather than originator licensing.
What geographic markets remain commercially relevant?
The United States, Europe, Japan, and selected emerging markets have different pricing and regulatory dynamics.
| Region |
Market condition |
| United States |
Mature generic market; pharmacy substitution and payer pricing dominate |
| European Union |
Generic competition with country-level reimbursement and tendering |
| Japan |
Established osteoporosis market with local reimbursement controls |
| China |
Volume opportunity but intense price pressure and procurement reforms |
| Latin America |
Brand and generic coexistence varies by country |
| Middle East and Africa |
Import dependence and distributor access are important |
Geographic value is higher where regulatory approval, local manufacturing, or distribution access is difficult. Those barriers can support margins even when the underlying molecule is unprotected.
What is the FDA regulatory status of ibandronate sodium?
The FDA-approved reference product is Boniva. Generic ibandronate sodium products can be approved through the ANDA pathway if they meet FDA requirements for pharmaceutical equivalence, bioequivalence, labeling, manufacturing quality, and facility compliance.[1][5]
The product is not a biologic and does not require a biosimilar application. Biosimilar risk is therefore not applicable in the legal sense. The relevant competitive risk is generic substitution.
The regulatory risk profile is moderate. The active ingredient is well characterized, but injectable products carry greater quality and inspection exposure than tablets. Recalls, manufacturing observations, or supply interruptions can change market shares temporarily.
Key Takeaways
- Ibandronate sodium is a mature generic bisphosphonate with limited current patent-based exclusivity.
- Boniva launched in the United States in 2003 as a monthly oral tablet and expanded to quarterly intravenous injection in 2005.
- Core compound and broad use protection have ceased to provide meaningful market-wide exclusivity.
- Oral generic competition is intense and creates high price and share erosion risk.
- Injectable ibandronate has greater manufacturing and supply-chain barriers but remains exposed to generic competition.
- No biosimilar pathway applies because ibandronate is a conventional small molecule.
- Revenue peaked during the branded osteoporosis period and declined after generic entry.
- Current commercial value lies in manufacturing scale, regulatory approvals, distribution, and institutional contracts.
- Alendronate and zoledronic acid remain important low-cost competitors, while denosumab and anabolic agents compete in higher-risk populations.
- Licensing value is limited; regional generic supply and portfolio transactions are more commercially plausible.
FAQs About Ibandronate Sodium Market and Patent Risk
Is ibandronate sodium still under patent protection?
Broad commercial protection for the active ingredient and original product has expired or become commercially immaterial. Any remaining rights must be assessed by patent number, claim scope, dosage form, and jurisdiction.
Can a generic manufacturer launch ibandronate sodium without a Paragraph IV challenge?
Yes. An ANDA applicant can use an applicable certification, including Paragraph III where relevant patents remain unexpired. A Paragraph IV filing is required only when the applicant disputes a listed patent’s validity, enforceability, or infringement.
Which ibandronate formulation has the stronger commercial barrier?
The 3 mg intravenous injection has a stronger practical barrier because sterile manufacturing and physician-channel distribution are more demanding. The 150 mg tablet remains easier to manufacture and substitute.
Is ibandronate sodium interchangeable with alendronate?
The products are in the same therapeutic class but are not identical products. Interchangeability depends on the specific product, FDA therapeutic-equivalence rating, clinical indication, dosing schedule, and prescriber judgment.
Does ibandronate sodium have meaningful future revenue growth potential?
Standalone growth potential is limited. Revenue opportunities are more likely to come from market-share gains, supply reliability, injectable capacity, geographic expansion, or portfolio consolidation than from price increases or new patent exclusivity.
References
- U.S. Food and Drug Administration. (2024). Boniva (ibandronate sodium) prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- Genentech, Inc. (2007). Annual report and product sales disclosures.
- Roche Holding Ltd. (2023). Annual report 2023.
- U.S. Food and Drug Administration. (2024). Abbreviated new drug application process and generic drug approval standards.