Last updated: September 29, 2026
Glycopyrrolate is a mature anticholinergic drug with limited value as a standalone generic and greater commercial value in branded respiratory combinations. Injectable and oral products face substantial generic competition. The strongest remaining commercial positions are combination inhalers, particularly AstraZeneca's Breztri Aerosphere, which combines budesonide, glycopyrrolate, and formoterol. The market is shifting from ingredient-level competition to device, formulation, manufacturing, and combination-product barriers.
What is glycopyrrolate and how is it used?
Glycopyrrolate is a synthetic muscarinic antagonist that reduces cholinergic activity in the respiratory tract, gastrointestinal tract, and perioperative setting. Its principal product categories are:
| Product category |
Typical use |
Competitive status |
| Injectable glycopyrrolate |
Preoperative secretion reduction, vagal reflex control, reversal of neuromuscular blockade |
Mature generic market |
| Oral glycopyrrolate tablets |
Hyperhidrosis and other off-label uses |
Generic market |
| Cuvposa oral solution |
Chronic severe drooling in pediatric patients with neurologic conditions |
Branded and generic oral-solution competition |
| Long-acting inhaled glycopyrrolate |
Maintenance treatment of chronic obstructive pulmonary disease |
Combination and device-driven market |
| Glycopyrrolate/formoterol |
Maintenance COPD treatment |
Branded combination product |
| Budesonide/glycopyrrolate/formoterol |
Triple therapy for COPD |
Largest commercial opportunity |
Glycopyrrolate is not a biologic and does not create a biosimilar market. Competition proceeds through abbreviated new drug applications, 505(b)(2) applications, combination-product development, and device or formulation differentiation.
What FDA-approved glycopyrrolate products are commercially important?
The commercial importance of glycopyrrolate depends heavily on dosage form.
Injectable and oral glycopyrrolate
Glycopyrrolate injection was approved decades ago and is available from multiple generic manufacturers. The product has low barriers to entry because the active ingredient, route of administration, and basic formulation are established.
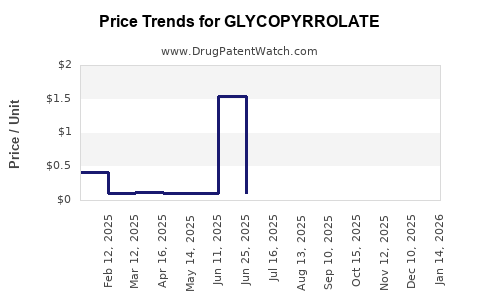
Oral glycopyrrolate tablets are also mature products. Demand is supported by hyperhidrosis treatment, although much use remains off-label. Pricing pressure is high because manufacturers compete largely on supply reliability and wholesaler access.
Cuvposa, an oral glycopyrrolate solution, received FDA approval in 2010 for chronic severe drooling in pediatric patients aged 3 to 16 years with neurologic conditions. Its commercial position is stronger than that of ordinary tablets because the product provides a pediatric liquid formulation and a labeled indication. The advantage is limited by the availability of compounded and generic oral solutions.
Inhaled glycopyrrolate products
The respiratory market is more commercially durable because inhaled products require device compatibility, dose uniformity, stability data, human-factor validation, and manufacturing scale.
Important U.S. products include:
| Product |
Active ingredients |
Sponsor or manufacturer |
FDA approval |
| Bevespi Aerosphere |
Glycopyrrolate/formoterol fumarate |
AstraZeneca |
2016 |
| Seebri Neohaler |
Glycopyrrolate |
Novartis |
2015 |
| Lonhala Magnair |
Glycopyrrolate inhalation solution |
Sunovion Pharmaceuticals |
2018 |
| Breztri Aerosphere |
Budesonide/glycopyrrolate/formoterol fumarate |
AstraZeneca |
2020 |
The single-agent inhaled products face a weaker long-term commercial position than combination inhalers. COPD treatment is increasingly concentrated in dual and triple therapies, where the full product, inhaler, clinical evidence, and regulatory package are protected rather than the glycopyrrolate molecule alone.
How large is the glycopyrrolate market?
There is no single reliable global revenue figure for glycopyrrolate because public companies generally report sales by brand or respiratory franchise rather than by active ingredient. Generic injectable and oral products are fragmented across manufacturers and are rarely reported as standalone revenue lines.
The market has three distinct economic tiers:
- Generic injection and tablets, where revenue is volume-driven and margins are constrained.
- Pediatric oral solution, where labeled use and formulation convenience support higher pricing.
- Branded inhaled combinations, where revenue is driven by COPD prevalence, formulary access, device performance, and treatment guidelines.
AstraZeneca's Breztri franchise is the clearest public indicator of the ingredient's commercial potential in a branded combination. AstraZeneca reported approximately $1 billion in global Breztri sales in 2023, reflecting the value of the triple-therapy product rather than glycopyrrolate alone (AstraZeneca, 2024). This revenue should not be attributed entirely to glycopyrrolate because Breztri also contains budesonide and formoterol.
The financial trajectory is therefore bifurcated:
| Segment |
Revenue trajectory |
Margin profile |
| Injectable glycopyrrolate |
Stable to declining in real terms |
Low |
| Oral tablets |
Stable, fragmented |
Low to moderate |
| Cuvposa and oral solution |
Niche, formulation-dependent |
Moderate |
| Single-agent inhalers |
Vulnerable to discontinuation and limited uptake |
Moderate |
| Dual and triple inhalers |
Growth driven by COPD treatment migration |
High relative to generics |
When does glycopyrrolate lose exclusivity?
Glycopyrrolate as an active ingredient is already off patent in the United States. The commercial question is whether a particular product has remaining protection covering its formulation, delivery device, combination, manufacturing method, or labeled use.
Core molecule
The original glycopyrrolate molecule and early injectable formulations do not provide meaningful current patent protection. Generic manufacturers can compete through ANDA filings, subject to applicable product-specific requirements.
Cuvposa
Cuvposa's original commercial protection was based on the pediatric oral-solution formulation, FDA approval, and regulatory exclusivity rather than a new molecular entity exclusivity period. Any early clinical-investigation exclusivity associated with approval has expired. Current competition depends on formulation patents, Orange Book listings, manufacturing capability, and generic approval status.
Bevespi and Breztri
The important intellectual-property assets for Bevespi and Breztri are product-specific. They may cover:
- Metered-dose inhaler composition.
- Aerosol suspension characteristics.
- Propellant and excipient systems.
- Dose delivery and valve performance.
- Combination therapy.
- Device components.
- Manufacturing and filling processes.
- Pediatric or other labeled-use claims.
These rights can expire later than the original glycopyrrolate patents. A generic manufacturer may challenge some claims while designing around others, producing a staggered entry risk rather than a single patent cliff.
What is the Orange Book status of glycopyrrolate products?
Orange Book analysis must be performed by product and application number. Glycopyrrolate itself does not have a single Orange Book position.
The relevant categories are:
| Product type |
Orange Book significance |
| Generic injection |
Reference-listed drug and therapeutic-equivalence competition |
| Generic tablets |
Standard ANDA pathway |
| Oral solution |
Potential formulation and dosage-form patents |
| Metered-dose inhaler |
Device, formulation, and drug-delivery patents |
| Combination inhaler |
Multiple active ingredients and product-specific patents |
| Fixed-dose triple therapy |
Combination claims, formulation patents, device rights, and regulatory exclusivity |
For Breztri and Bevespi, Orange Book listings are more commercially significant than for old injectable products because the listed patents can delay approval or generate Paragraph IV litigation. A current diligence review should use the FDA Orange Book patent and exclusivity listings for the specific reference-listed drug and application number (U.S. Food and Drug Administration, 2024a).
How many patents cover glycopyrrolate?
No meaningful single patent count exists for the glycopyrrolate market. Patent scope varies by product.
A practical patent-estate classification is:
| Patent layer |
Relevance to glycopyrrolate |
| Composition-of-matter patents |
Expired for the core molecule |
| Salt and crystal-form patents |
Usually limited commercial importance |
| Oral-liquid formulation patents |
Relevant to Cuvposa-type products |
| Inhaler formulation patents |
Material for Bevespi, Breztri, and related products |
| Device patents |
Potentially material for metered-dose and nebulized delivery |
| Combination patents |
Material for glycopyrrolate/formoterol and triple therapy |
| Method-of-use patents |
May protect COPD maintenance or specific patient populations |
| Manufacturing patents |
Can raise technical barriers without blocking all generic entry |
The strongest estate is generally the one surrounding a branded inhaler system, not the active ingredient. Patent strength depends on claim breadth, validity, remaining term, prosecution history, prior-art exposure, and whether a generic can launch with a non-infringing device or formulation.
Which companies are challenging glycopyrrolate exclusivity?
Generic manufacturers are most likely to challenge mature oral and injectable products through ANDA filings. The more significant strategic challengers for inhaled products include large generic and respiratory companies with inhaler manufacturing capability, such as Viatris, Teva, Cipla, Lupin, Glenmark, and Sandoz.
Public records do not establish a single consolidated challenger list for every glycopyrrolate product. Paragraph IV activity must be assessed by reference product, patent number, ANDA applicant, and litigation docket. A Paragraph IV certification can trigger litigation but does not itself establish invalidity or guarantee an early launch.
Paragraph IV risk by product category
| Product |
Paragraph IV risk |
Reason |
| Generic injection |
High historic entry risk, low patent risk |
Old molecule and simple dosage form |
| Oral tablets |
High |
Mature product with limited formulation complexity |
| Cuvposa |
Moderate |
Oral-liquid formulation and labeled-use issues |
| Bevespi |
Moderate to high |
Inhaler formulation and device complexity |
| Breztri |
Moderate |
Triple combination, device, and multiple patent layers |
| Single-agent inhaled glycopyrrolate |
Product-specific |
Commercial viability depends on remaining market and patent scope |
What generic launch scenarios exist for glycopyrrolate?
The likely entry sequence differs by dosage form.
Injectable and tablet launch
Generic entry is already established. Competition is based on manufacturing cost, hospital contracts, wholesaler supply, and shortage management. Price erosion is typically more severe when several approved suppliers are active.
Oral-solution launch
A generic oral solution can enter after satisfying formulation, stability, bioequivalence, and labeling requirements. The market may sustain more than one supplier because pediatric dosing and product availability matter, but the addressable population remains relatively narrow.
Inhaler launch
An inhaled generic faces higher development costs and regulatory risk. The applicant must demonstrate equivalent drug delivery, device performance, and, where required, substitutability under FDA standards. A first entrant may obtain a temporary commercial advantage, but later entrants can drive substantial price erosion.
Authorized-generic scenario
A branded manufacturer may use an authorized generic or licensing arrangement to preserve channel access and reduce the commercial impact of an independent Paragraph IV entrant. This strategy is more plausible for products with significant residual brand demand and manufacturing capacity.
What patent litigation and settlement issues affect glycopyrrolate?
Litigation risk is concentrated in branded inhalers. The typical dispute involves:
- Patent validity.
- Infringement by an inhaler device or formulation.
- Whether an ANDA applicant can use a carve-out label.
- Whether a generic device is sufficiently different.
- Whether the patent is properly listed in the Orange Book.
- Whether a settlement restricts the generic launch date.
Settlement agreements can provide a negotiated launch date before patent expiry. The commercial value of such agreements depends on the size of the COPD market, the number of potential entrants, and the remaining life of the brand's formulation and device patents. FTC and FDA review of settlement arrangements remains relevant where a payment-for-delay concern exists (Federal Trade Commission, 2024).
No biosimilar litigation applies because glycopyrrolate is a small molecule. The central legal risks are ANDA litigation, patent-term calculation, device equivalence, and regulatory exclusivity.
What is the FDA regulatory status of glycopyrrolate?
Glycopyrrolate is FDA-approved in multiple dosage forms and combinations. The regulatory pathway varies by product:
- ANDA for conventional generic injection, tablets, or oral solution.
- 505(b)(2) NDA for reformulated or repositioned products.
- Full or supplemental NDA for combination inhalers and new delivery systems.
- Device-drug combination review for metered-dose inhalers and nebulized systems.
FDA approval does not guarantee therapeutic equivalence across inhaled products. Inhaler substitution depends on the product's approved substitutability designation and applicable state pharmacy rules. Combination inhalers may require more extensive comparative performance data than tablets or injections (U.S. Food and Drug Administration, 2024b).
How does glycopyrrolate compare with competing COPD anticholinergics?
Glycopyrrolate competes primarily with other long-acting muscarinic antagonists, including tiotropium, umeclidinium, aclidinium, and revefenacin.
| Drug |
Typical positioning |
Commercial implication |
| Glycopyrrolate |
Dual and triple inhaler component |
Strongest in combination products |
| Tiotropium |
Established single-agent and combination use |
Broad clinical recognition |
| Umeclidinium |
Inhaled maintenance and combination products |
Strong branded respiratory platform |
| Aclidinium |
Maintenance COPD therapy |
More limited commercial scale |
| Revefenacin |
Nebulized LAMA |
Differentiated delivery for selected patients |
Glycopyrrolate's competitive advantage is not necessarily superior molecule-level efficacy. Its value is tied to formulation, device usability, combination compatibility, and inclusion in guideline-supported triple therapy.
What licensing deals and partnerships matter?
Commercial partnerships are more important for glycopyrrolate inhalers than for generic injection or tablets. Relevant structures include:
- Licensing of inhaler technology.
- Contract manufacturing for metered-dose inhalers.
- Regional commercialization agreements.
- Co-development of fixed-dose combinations.
- Device supply agreements.
- Authorized-generic arrangements.
AstraZeneca's respiratory portfolio illustrates the value of integrating glycopyrrolate into a broader COPD franchise. The combination product can leverage existing sales infrastructure, payer relationships, and clinical-trial data. By contrast, generic suppliers compete primarily through manufacturing scale and distribution.
How strong is the glycopyrrolate patent estate?
The estate is weak for the molecule and mature generic dosage forms but stronger for branded delivery systems.
| Asset |
Patent strength |
Main vulnerability |
| Core glycopyrrolate |
Weak or expired |
Long prior-art history |
| Injection |
Weak |
Multiple generic suppliers |
| Tablets |
Weak |
Straightforward formulation |
| Oral solution |
Moderate |
Design-around and compounding |
| Single-agent inhaler |
Moderate |
Limited market and device substitution |
| Dual inhaler |
Moderate to strong |
Device and formulation challenges |
| Triple inhaler |
Stronger commercially |
Multiple patents but complex validity analysis |
The principal manufacturing barrier is not synthesis of glycopyrrolate. It is reproducible inhaler filling, suspension control, valve performance, container-closure integrity, and regulatory validation. These barriers can delay generic entry even when molecule-level patent protection has ended.
What is the long-term financial trajectory for glycopyrrolate?
The likely trajectory is stable or declining for standalone generic products and positive for selected branded COPD combinations.
Base case
Generic injection and oral products remain available at low prices. Oral-solution demand persists as a niche pediatric market. Branded respiratory combinations generate the majority of economic value associated with glycopyrrolate.
Downside case
Inhaler patents expire, several generic entrants obtain approval, and payer substitution accelerates. Breztri and other combination products experience price erosion while generic standalone products remain commoditized.
Upside case
COPD diagnosis improves, triple therapy adoption expands, and branded inhalers retain formulary preference because of device performance or clinical positioning. Revenue growth continues even after molecule-level patents have expired.
The most important financial metric is therefore not total glycopyrrolate unit volume. It is the share of units delivered through protected or differentiated inhaler combinations.
Key Takeaways
- Glycopyrrolate is an off-patent molecule with mature generic competition.
- Injectable and tablet products have low barriers and limited pricing power.
- Cuvposa retains niche value through its pediatric oral-solution formulation.
- The main commercial opportunity is in branded COPD inhalers.
- Breztri is the most important public commercial asset containing glycopyrrolate.
- Patent risk centers on inhaler formulations, devices, combinations, manufacturing, and method-of-use claims.
- Paragraph IV challenges are product-specific and should be evaluated through current Orange Book listings and court dockets.
- Glycopyrrolate has no biosimilar pathway because it is a small molecule.
- Generic entry is already established for conventional dosage forms but remains technically more difficult for inhalers.
- The financial trajectory is bifurcated: commodity economics for standalone glycopyrrolate and higher-value franchise economics for protected respiratory combinations.
Frequently Asked Questions
Is glycopyrrolate a biologic drug?
No. Glycopyrrolate is a small-molecule drug. Generic competition proceeds through ANDAs or related small-molecule pathways, not biosimilar applications.
Is glycopyrrolate still patent protected?
The original glycopyrrolate molecule is not meaningfully patent protected. Some branded inhalers and formulations may retain active product, device, combination, or manufacturing patents.
Which glycopyrrolate product has the greatest commercial value?
Breztri Aerosphere has the greatest publicly visible commercial value because it contains glycopyrrolate in a branded triple-therapy COPD product with substantial reported sales.
Can a generic manufacturer substitute a glycopyrrolate inhaler automatically?
Not necessarily. Substitution depends on the FDA-approved substitutability status of the specific product and applicable state law. Inhaled products require closer analysis than conventional tablets or injections.
What is the main investment risk in glycopyrrolate?
The main risk is confusing glycopyrrolate ingredient demand with branded combination-product revenue. Generic ingredient sales are vulnerable to price erosion, while branded inhaler value depends on patent durability, payer access, device differentiation, and COPD treatment adoption.
References
-
AstraZeneca. (2024). Annual report and Form 20-F 2023. AstraZeneca plc.
-
Federal Trade Commission. (2024). Agreements filed with the Federal Trade Commission under the Medicare Prescription Drug, Improvement, and Modernization Act. Federal Trade Commission.
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations: Orange Book. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024b). Product-specific guidances for generic drug development. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2010). Cuvposa prescribing information. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2016). Bevespi Aerosphere prescribing information. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2020). Breztri Aerosphere prescribing information. U.S. Department of Health and Human Services.