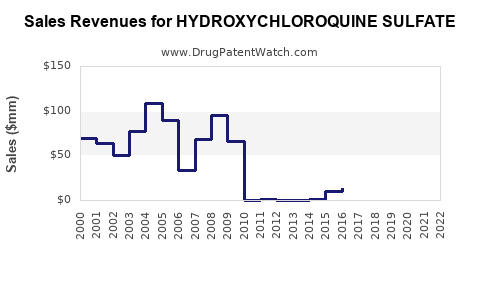
Last updated: September 7, 2026
Hydroxychloroquine sulfate is a mature, low-cost generic drug with no meaningful remaining core patent exclusivity in the United States. Its commercial trajectory has been shaped by three forces: chronic demand for lupus and rheumatoid arthritis, periodic malaria demand, and the sharp but temporary COVID-19 demand shock in 2020. Generic competition, low unit prices, limited manufacturer differentiation, and safety-monitoring requirements constrain long-term revenue growth.
What is the current market position of hydroxychloroquine sulfate?
Hydroxychloroquine sulfate is an established 4-aminoquinoline drug sold primarily as 200 mg oral tablets. Its FDA-approved uses include:
- Malaria treatment and prophylaxis for susceptible strains
- Rheumatoid arthritis
- Systemic lupus erythematosus
- Chronic discoid lupus erythematosus
The drug is marketed in the United States under generic names and historically under Sanofi’s Plaquenil brand. Generic hydroxychloroquine sulfate accounts for the commercial market because the active ingredient and tablet formulation are long established and multiple manufacturers have FDA-approved products.
Hydroxychloroquine is not a biologic and does not face biosimilar competition. It is an abbreviated new drug application, or ANDA, product market in the United States.
Market structure
| Market characteristic |
Hydroxychloroquine sulfate |
| Primary dosage form |
Immediate-release oral tablet |
| Common strength |
200 mg |
| U.S. regulatory pathway |
NDA originator and ANDA generics |
| Major therapeutic markets |
Lupus, rheumatoid arthritis, malaria |
| Biosimilar exposure |
None |
| Core patent status |
Expired |
| Current competitive basis |
Price, supply reliability, wholesaler access |
| Key commercial constraint |
Low generic pricing |
| Main safety issue |
Retinal toxicity with prolonged exposure |
Demand is relatively stable in autoimmune diseases because lupus and rheumatoid arthritis patients often use the drug chronically. Malaria demand is more dependent on geography, resistance patterns, public-health procurement, and travel medicine.
The drug has a broad clinical footprint but limited pricing power. Prescribers can generally choose among several generic suppliers, and pharmacy benefit managers have little reason to favor one supplier unless it offers lower cost or better supply continuity.
How did COVID-19 change hydroxychloroquine sales?
COVID-19 produced an exceptional short-term demand spike in early 2020. Prescriptions increased as clinicians, patients, governments, and hospitals acquired hydroxychloroquine for potential COVID-19 treatment or prophylaxis, despite limited evidence at the time.
The FDA issued an emergency use authorization for hydroxychloroquine and chloroquine products for certain hospitalized COVID-19 patients in March 2020. The agency revoked that authorization on June 15, 2020, after available evidence showed that the drugs were unlikely to be effective for the authorized COVID-19 uses and raised safety concerns, including cardiac arrhythmias.[1]
Randomized clinical evidence later showed no meaningful benefit for prevention or treatment of COVID-19 in the studied settings. The RECOVERY trial stopped its hydroxychloroquine treatment arm after finding no clinical benefit in hospitalized patients.[2] A Cochrane review also concluded that hydroxychloroquine did not provide meaningful benefit for COVID-19 treatment or prevention and could increase adverse events.[3]
Financial effect of the COVID-19 surge
The 2020 surge created a temporary volume event rather than a durable market expansion.
| Period |
Market effect |
| Pre-2020 |
Stable, mature generic demand |
| First quarter 2020 |
Sharp prescription and stockpiling increase |
| Second quarter 2020 |
High visibility, supply constraints, regulatory scrutiny |
| Second half 2020 |
Demand contraction after negative clinical evidence and EUA revocation |
| 2021 onward |
Return toward chronic autoimmune and malaria demand |
Sanofi reported increased Plaquenil demand during the early pandemic period but did not establish COVID-19 as a sustainable commercial indication. Public company reporting generally does not disclose hydroxychloroquine revenue as a separate, long-term operating segment, limiting precise calculation of manufacturer-specific financial exposure.[4]
What patents protect hydroxychloroquine sulfate?
No active U.S. composition-of-matter patent protects hydroxychloroquine sulfate. The drug’s core intellectual property expired decades ago.
The historical Plaquenil estate covered the active ingredient and conventional oral product concepts. Those rights are no longer capable of blocking generic entry. Current competition is therefore based on approved product quality, manufacturing capacity, supply reliability, distribution, and price.
Orange Book status
The FDA Orange Book identifies approved reference and generic drug products, patent listings, and exclusivity information. Hydroxychloroquine sulfate has no current Orange Book exclusivity capable of preventing ordinary ANDA competition.[5]
The practical patent position is:
| IP category |
Current commercial impact |
| Active ingredient patent |
None |
| Original product patent |
Expired |
| Pediatric exclusivity |
None of material commercial relevance |
| New chemical entity exclusivity |
Expired |
| Formulation patents |
No broad, commercially blocking estate identified |
| Method-of-use patents |
No active broad indication patent blocking approved generic uses |
| Manufacturing patents |
Potentially relevant to individual suppliers, but not a general market barrier |
| Trade secrets |
May affect manufacturing cost and quality but do not block generic substitution |
A manufacturer could seek protection for a new formulation, delivery system, combination product, or narrow method of use. Such a patent would not restore exclusivity to standard 200 mg hydroxychloroquine tablets.
What formulations are protected by hydroxychloroquine patents?
The commercially dominant product is the conventional immediate-release tablet. It is not protected by a current broad formulation patent that prevents generic substitution.
Potential formulation opportunities include:
- Modified-release tablets
- Pediatric liquid formulations
- Taste-masked oral suspensions
- Fixed-dose combinations
- Alternative dosage forms for patients with swallowing difficulty
- Formulations designed to reduce gastrointestinal intolerance
These concepts face limited commercial upside because hydroxychloroquine is inexpensive, the patient population is accustomed to tablets, and payers may resist premium pricing without clear clinical or adherence benefits.
A new formulation would also need to demonstrate pharmaceutical equivalence, stability, bioavailability, and a commercially defensible clinical advantage. A formulation patent could protect a specific product but would not materially strengthen the legacy tablet market.
When does hydroxychloroquine sulfate lose exclusivity?
Hydroxychloroquine sulfate lost meaningful U.S. exclusivity before the modern generic market developed. The drug is therefore already post-exclusivity in the United States, Europe, and other major pharmaceutical markets.
There is no upcoming loss-of-exclusivity event comparable to a branded drug approaching patent expiry. Instead, the relevant commercial question is whether supply, regulatory, or manufacturing events temporarily reduce generic competition.
Exclusivity timeline
| Milestone |
Timing |
Commercial consequence |
| Original hydroxychloroquine development |
20th century |
Established the active ingredient |
| Plaquenil commercialization |
1950s |
Created the branded reference product |
| Core patent protection |
Expired decades ago |
Removed composition-level barriers |
| Generic entry |
Historical |
Converted the market to commodity competition |
| COVID-19 EUA |
March 2020 |
Created temporary demand expansion |
| EUA revocation |
June 2020 |
Removed COVID-19 regulatory support |
| Current market |
Mature generic |
No pending core patent cliff |
Which companies manufacture hydroxychloroquine sulfate?
Manufacturers and labelers have changed over time as companies enter, exit, acquire products, or transfer ANDAs. U.S. market participants have included large generic companies and specialty manufacturers such as Teva, Sandoz, Amneal, Zydus, and Hikma, although product availability varies by period and market.
The manufacturer landscape is fragmented. No single company has a durable monopoly based on intellectual property.
Competitive advantages among generic suppliers
Manufacturers compete through:
- Reliable access to hydroxychloroquine sulfate active pharmaceutical ingredient.
- FDA-compliant tablet production.
- Inventory management and shortage avoidance.
- Wholesale and retail distribution.
- Contract supply to hospitals, government agencies, and pharmacies.
- Ability to maintain margins at low prices.
A supplier with a low-cost manufacturing base can remain competitive, but the market generally does not support substantial premium pricing. FDA quality findings, plant interruptions, or API shortages can have a greater short-term effect on commercial performance than patent developments.
What is the FDA regulatory status of hydroxychloroquine sulfate?
Hydroxychloroquine sulfate remains FDA-approved for malaria, rheumatoid arthritis, and lupus-related indications. The COVID-19 EUA is no longer active.
The FDA-approved label includes warnings related to retinal toxicity, cardiomyopathy, conduction disorders, hypoglycemia, neuropsychiatric effects, and drug interactions. Retinal toxicity risk increases with cumulative exposure, making ophthalmologic monitoring important for chronic users.[6]
The American Academy of Ophthalmology recommends baseline and periodic screening based on dose, duration, renal function, and other risk factors.[7] These requirements do not prevent use but can increase total treatment-management costs and influence prescribing.
Regulatory factors affecting demand
- Continued autoimmune disease prevalence supports baseline demand.
- Resistance to chloroquine-class drugs limits malaria use in some regions.
- Retinal and cardiac safety concerns constrain off-label expansion.
- COVID-19 prescribing has largely returned to pre-pandemic standards.
- Generic approval requirements keep product quality and bioequivalence central to competition.
How strong is the patent estate for hydroxychloroquine sulfate?
The patent estate is weak for the standard product and offers no meaningful barrier to generic entry.
| Patent-strength factor |
Assessment |
| Core molecule |
Very weak; long expired |
| Standard tablet |
Very weak |
| Approved autoimmune indications |
Weak; generic competition established |
| New formulations |
Potentially moderate if clinically differentiated |
| Manufacturing process |
Potentially relevant to a specific supplier |
| Regulatory exclusivity |
None of material current value |
| Litigation leverage |
Low |
| Generic launch risk |
High for any branded standard tablet |
The absence of active core patents means a company cannot defend a conventional hydroxychloroquine tablet through patent litigation alone. A litigation strategy would have to rely on a specific formulation, manufacturing process, or narrow method-of-use claim.
Are there Paragraph IV challenges involving hydroxychloroquine sulfate?
Hydroxychloroquine sulfate has no current Paragraph IV event of major commercial significance because the reference product’s core patent protection has already expired and generic products are established.
Paragraph IV certifications are most commercially important before generic launch, when an ANDA applicant challenges an unexpired Orange Book patent. For hydroxychloroquine sulfate, generic competition is already mature. Any future Paragraph IV case would likely involve a new formulation or a newly patented delivery system rather than the conventional tablet.
What patent litigation affects hydroxychloroquine sulfate?
No active, market-defining patent litigation currently controls access to standard hydroxychloroquine sulfate tablets in the United States.
The most consequential legal and regulatory event was not a patent dispute but the COVID-19 EUA revocation and the related litigation and public controversy over off-label prescribing. That episode affected demand, inventory, procurement, and public perception but did not create durable exclusivity.
For investors and generic manufacturers, the principal legal risks are more likely to involve:
- Product liability claims involving retinal or cardiac injury
- FDA manufacturing or quality enforcement
- False advertising or unsupported COVID-19 claims
- Pharmacy dispensing and reimbursement disputes
- State restrictions on off-label dispensing during shortages
- Contract disputes involving public-health procurement
Are there licensing deals for hydroxychloroquine sulfate?
No major current licensing transaction is required to commercialize standard hydroxychloroquine sulfate tablets in the United States. The product is broadly available through generic ANDAs, and no active originator license is needed for ordinary generic entry.
Licensing could become relevant if a company develops:
- A proprietary extended-release formulation
- A combination product
- A pediatric product with differentiated delivery
- A novel topical or localized formulation
- A product supported by a new patent-protected indication
Those opportunities would involve new product development rather than licensing access to the legacy molecule.
What revenue exposure does hydroxychloroquine sulfate create for manufacturers?
Hydroxychloroquine sulfate has limited standalone revenue significance for diversified pharmaceutical companies. Generic manufacturers typically report revenue by segment rather than by individual mature molecule, and public filings rarely disclose hydroxychloroquine sales separately.
The drug can still affect financial performance in specific circumstances:
- A temporary shortage can increase shipment volume and price.
- A government procurement contract can concentrate demand.
- A supplier disruption can shift market share.
- A quality recall can remove a product from distribution.
- A pandemic or malaria outbreak can create short-term volume changes.
- Price compression can reduce revenue even when prescription volume remains stable.
For Sanofi, Plaquenil was historically part of a broader portfolio and did not become a material long-term revenue driver after the COVID-19 episode. For generic manufacturers, the product is more likely to contribute incremental portfolio revenue than to determine company valuation.
What generic launch risks exist for hydroxychloroquine sulfate?
Generic launch risk is high in the sense that entry barriers are low, but commercial returns are limited.
Principal risks
- Multiple established suppliers
- Low wholesale acquisition prices
- Pharmacy benefit manager price pressure
- Limited differentiation among tablet products
- FDA inspection and compliance exposure
- API sourcing concentration
- Inventory volatility during public-health events
- Small market opportunity for premium formulations
A new entrant may obtain approval but fail to gain meaningful share because pharmacies already have established suppliers. Market entry is most attractive when a company has a low-cost manufacturing platform, existing distribution relationships, or a strategy to address a supply shortage.
How does hydroxychloroquine compare with competing lupus and rheumatoid arthritis drugs?
Hydroxychloroquine competes clinically with conventional disease-modifying antirheumatic drugs and, in more severe disease, biologic therapies. It is usually less expensive than methotrexate alternatives, biologic agents, and targeted synthetic disease-modifying drugs.
| Drug category |
Typical role |
Relative cost position |
Patent profile |
| Hydroxychloroquine |
Lupus and mild-to-moderate inflammatory disease |
Low |
Expired |
| Methotrexate |
Rheumatoid arthritis and other autoimmune diseases |
Low |
Mature generic |
| Leflunomide |
Rheumatoid arthritis |
Low to moderate |
Mature generic |
| Biologic DMARDs |
Moderate-to-severe autoimmune disease |
High |
Product-specific patents and exclusivity |
| JAK inhibitors |
Targeted autoimmune treatment |
High |
Active or recently expired estates vary |
Hydroxychloroquine retains clinical value because it is familiar, orally administered, inexpensive, and useful in long-term lupus management. Its weakness is limited potency for severe disease and the need for ophthalmologic monitoring.
Key Takeaways
- Hydroxychloroquine sulfate is a mature generic drug with no meaningful remaining core patent exclusivity.
- The U.S. market is driven mainly by chronic lupus and rheumatoid arthritis use, with malaria demand varying by geography.
- COVID-19 created a sharp but temporary sales and prescription surge in 2020.
- The FDA revoked the COVID-19 EUA on June 15, 2020.
- No active Orange Book patent or Paragraph IV dispute materially blocks standard generic tablets.
- Standard tablet economics are controlled by price, supply reliability, manufacturing quality, and distribution.
- New formulation patents could create a niche opportunity but would not restore exclusivity to the legacy product.
- Public companies generally do not disclose hydroxychloroquine revenue separately, limiting molecule-level financial attribution.
- The largest commercial risks are price compression, supply disruption, regulatory enforcement, and product liability rather than patent expiration.
FAQs
Is hydroxychloroquine sulfate still profitable for pharmaceutical companies?
It can generate incremental revenue for generic manufacturers, but low prices and established competition limit profitability. It is rarely a major standalone earnings driver for diversified companies.
Is Plaquenil still patent protected?
No. The original Plaquenil and hydroxychloroquine composition patents expired long ago. Current market access is not blocked by the historical branded product patents.
Can a company patent a new hydroxychloroquine product?
Yes. A company may patent a specific formulation, delivery system, combination, or narrow method of use if it satisfies patentability standards. Such protection would cover the new product, not ordinary hydroxychloroquine sulfate tablets.
Does hydroxychloroquine have biosimilar competition?
No. Hydroxychloroquine sulfate is a small-molecule drug, so the relevant competitors are generic products approved through ANDAs, not biosimilars.
What would increase hydroxychloroquine sulfate market value?
A sustained supply shortage, a validated new indication, a clinically superior formulation, or a differentiated pediatric or modified-release product could increase value. None has displaced the low-cost generic tablet market.
References
-
U.S. Food and Drug Administration. (2020, June 15). FDA revokes emergency use authorization for chloroquine and hydroxychloroquine. https://www.fda.gov
-
Horby, P., Mafham, M., Linsell, L., Bell, J. L., Staplin, N., Emberson, J. R., Palmer, T., Spiess, A., and others. (2020). Effect of hydroxychloroquine in hospitalized patients with Covid-19. New England Journal of Medicine, 383(21), 2030-2040. https://doi.org/10.1056/NEJMoa2022926
-
Singh, B., Ryan, H., Kredo, T., Chaplin, M., Fletcher, T., and Scott, J. A. (2021). Chloroquine or hydroxychloroquine for prevention and treatment of COVID-19. Cochrane Database of Systematic Reviews, 2021(2), CD013587. https://doi.org/10.1002/14651858.CD013587.pub2
-
Sanofi. (2021). 2020 annual report. https://www.sanofi.com
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov
-
U.S. Food and Drug Administration. (2020). Plaquenil hydroxychloroquine sulfate tablets prescribing information. https://www.accessdata.fda.gov
-
Marmor, M. F., Kellner, U., Lai, T. Y. Y., Lyons, J. S., and Mieler, W. F. (2016). Recommendations on screening for chloroquine and hydroxychloroquine retinopathy. Ophthalmology, 123(6), 1386-1394. https://doi.org/10.1016/j.ophtha.2016.01.058