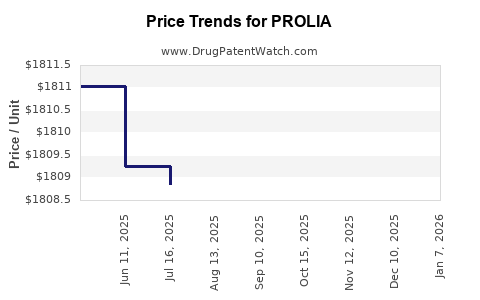
Last updated: November 7, 2026
Prolia, Amgen's denosumab injection for osteoporosis, generated approximately $4.5 billion in global sales in 2024, up from about $4.0 billion in 2023. Its commercial growth has been driven by aging populations, persistent osteoporosis undertreatment, six-month dosing, and expansion in male osteoporosis and glucocorticoid-induced osteoporosis. The principal medium-term risk is biosimilar competition rather than small-molecule generic substitution.
The U.S. biologic exclusivity period has expired, and the FDA approved Sandoz's denosumab biosimilars in March 2025. Prolia remains commercially resilient because of physician familiarity, established reimbursement, a large treated population, and Amgen's ability to defend the product through lifecycle management and contracting. Revenue is likely to peak or flatten as biosimilar adoption expands, with erosion depending on launch timing, interchangeability, payer controls, and the degree to which Prolia patients remain on branded therapy.
What is Prolia and how does it generate revenue?
Prolia is a 60-mg subcutaneous injection of denosumab administered once every six months. Amgen markets it primarily for postmenopausal women with osteoporosis at high fracture risk. U.S. labeling also covers men with osteoporosis, men and women receiving glucocorticoid therapy, and patients receiving adjuvant aromatase-inhibitor therapy or androgen-deprivation therapy who are at high fracture risk.[1]
Denosumab is a monoclonal antibody that inhibits RANK ligand, reducing osteoclast formation and bone resorption. Its six-month dosing schedule differentiates it from weekly or monthly oral bisphosphonates and supports administration in physician offices, hospital outpatient departments, and specialty practices.
Revenue sources include:
- U.S. office-based administration and specialty pharmacy distribution.
- International sales through national reimbursement systems.
- Repeat dosing from an established patient base.
- Expansion into men and patients receiving cancer-related hormone therapies.
- Price and mix benefits from branded biologic status before biosimilar entry.
Prolia is also strategically linked to Xgeva, Amgen's higher-dose denosumab product used in oncology. The two products share the same active antibody but have different doses, indications, dosing schedules, and commercial channels.
How has Prolia's financial trajectory developed?
Amgen has reported sustained Prolia growth over the last several years, although the product is moving toward a more mature stage of its lifecycle.
| Fiscal year |
Approximate global Prolia sales |
Commercial interpretation |
| 2021 |
About $3.0 billion |
Continued post-pandemic recovery and broader osteoporosis demand |
| 2022 |
About $3.6 billion |
Strong volume and pricing contribution |
| 2023 |
About $4.0 billion |
Growth from U.S. demand and international expansion |
| 2024 |
About $4.5 billion |
Continued volume growth before meaningful biosimilar erosion |
Sources: Amgen annual reports and earnings disclosures.[2-5]
The increase from roughly $3.0 billion in 2021 to approximately $4.5 billion in 2024 represents a compound annual growth rate of about 15%. This growth rate is unlikely to continue after biosimilar launches. Prolia's financial profile is shifting from expansion to erosion management.
What is the revenue exposure to Prolia?
Prolia is one of Amgen's largest products and a major contributor to the company's non-oncology growth portfolio. It is smaller than Enbrel and several other historical franchise products in some reporting periods, but its growth has been faster and its administration model supports predictable recurring demand.
Key financial sensitivities include:
- The percentage of patients receiving injections on schedule.
- U.S. payer coverage and buy-and-bill economics.
- Physician willingness to switch stable patients to biosimilars.
- Biosimilar discounts and contracting terms.
- The rate at which patients discontinue therapy or switch to oral alternatives.
- International reimbursement and tender pricing.
Prolia's six-month schedule creates recurring revenue, but it also increases the financial consequences of missed injections. FDA labeling warns that multiple vertebral fractures can occur after discontinuation, particularly when alternative antiresorptive treatment is not provided.[1] This clinical consideration can reduce rapid switching and support continuity of therapy.
When does Prolia lose exclusivity?
Prolia's FDA approval date was June 1, 2010. The U.S. biologic reference-product exclusivity period under the Biologics Price Competition and Innovation Act ended in 2022, 12 years after first licensure.[6]
The end of biologic exclusivity did not produce immediate market erosion because biosimilar developers still had to complete development, obtain FDA approval, and resolve patent and regulatory issues. Prolia's practical loss of exclusivity therefore occurs later than the statutory end of reference-product exclusivity.
| Milestone |
Date or status |
| FDA approval of Prolia |
June 1, 2010 |
| U.S. 12-year biologic exclusivity |
Expired in 2022 |
| First FDA-approved denosumab biosimilars |
March 2025 |
| Main commercial risk period |
2025 onward |
| Expected erosion pattern |
Gradual initially, potentially accelerating with payer adoption |
The exact pace of decline depends on the commercial terms governing biosimilar launches and the number of competing products.
What is the FDA and Orange Book status of Prolia?
Prolia is a biologic drug and is not listed in the FDA Orange Book in the same manner as a conventional small-molecule drug. The Orange Book primarily identifies approved small-molecule drug products, their therapeutic equivalence information, and listed patents.
Biologic competition is governed through the FDA's Purple Book and the BPCIA. The relevant regulatory pathway is a 351(k) biosimilar application, not an abbreviated new drug application under section 505(j).[6,7]
What is the Purple Book status of Prolia?
Prolia is the reference product for denosumab biosimilar development. Sandoz received FDA approval in March 2025 for two denosumab products:
- Jubbonti, denosumab-bbdz, referencing Prolia.
- Wyost, denosumab-bbdz, referencing Xgeva.
Jubbonti is directed to Prolia's osteoporosis-related indications, while Wyost is directed to Xgeva's oncology indications. The products are based on the same denosumab molecule but are approved for different reference-product uses.[8]
The approval of Jubbonti establishes the first direct FDA-approved biosimilar competition to Prolia. It also creates a commercial platform for Sandoz across both osteoporosis and oncology denosumab markets.
What patents protect Prolia?
Prolia's relevant protection consists of a combination of biologic exclusivity, formulation and manufacturing know-how, clinical data, antibody-related patent claims, and litigation rights under the BPCIA. Unlike an Orange Book-listed tablet, the full commercial patent position is not captured in a single public FDA patent table.
The earliest foundational denosumab patents have expired or have limited remaining value. The commercially important questions are whether later-issued patents cover:
- Specific denosumab formulations.
- Stabilizers, concentrations, and storage conditions.
- Container and prefilled-syringe configurations.
- Manufacturing and purification methods.
- Antibody sequence or binding characteristics.
- Dosing regimens and treatment methods.
- Particular osteoporosis patient populations.
How strong is the Prolia patent estate?
The estate is strongest where patents cover manufacturing processes, formulation attributes, or clinically relevant dosing methods that are difficult to design around. It is weaker where claims broadly cover the underlying antibody or basic osteoporosis use, because foundational biologic and method claims face earlier expiration dates and validity challenges.
The practical value of Prolia's remaining patent position is therefore less about blocking all biosimilar development and more about controlling launch timing, settlement terms, and the risk-adjusted cost of entry.
Amgen's biologic patent position is also supported by manufacturing complexity. Denosumab is a large, glycosylated antibody requiring cell-line development, process control, comparability testing, and validated analytical methods. Those factors do not prevent biosimilar approval, but they can slow development and complicate rapid substitution.
Which companies are challenging Prolia's market position?
Sandoz is the first clearly identified FDA-approved direct challenger. Other major biosimilar developers have pursued denosumab programs or have been associated with denosumab development, including Celltrion, Samsung Bioepis, Organon and Biocon Biologics, depending on jurisdiction and indication.
The competitive field is divided into four groups:
| Competitor type |
Examples |
Main competitive mechanism |
| Denosumab biosimilars |
Sandoz Jubbonti and Wyost |
Lower net price and payer substitution |
| Other osteoporosis biologics |
Evenity, romosozumab |
Different mechanism and monthly dosing |
| Oral bisphosphonates |
Alendronate, risedronate |
Low-cost generic treatment |
| Intravenous bisphosphonates |
Zoledronic acid |
Annual or periodic infusion |
Biosimilars pose the greatest direct threat because they reproduce the denosumab treatment model. Oral and intravenous bisphosphonates are indirect competitors and are more relevant for treatment initiation, tolerability, adherence, renal considerations, and patient preference.
What generic entry risks exist for Prolia?
Traditional generic entry is not available for Prolia. The relevant threat is biosimilar entry.
How will biosimilars affect Prolia pricing?
The initial effect is likely to be a reduction in net price rather than an immediate collapse in gross sales. Physicians and payers may retain Prolia for patients who are clinically stable, while directing new patients toward lower-cost biosimilars.
Potential erosion scenarios include:
| Scenario |
Commercial result |
| Slow payer adoption |
Prolia retains most volume but gives up rebates and price |
| Moderate substitution |
New starts shift to biosimilars; stable patients remain on Prolia |
| Rapid substitution |
Formularies prefer biosimilars and Prolia loses both volume and price |
| Multi-biosimilar competition |
Greater discounts, lower net price, and faster share loss |
The absence of automatic pharmacy substitution for many physician-administered biologics can slow switching. Payer policies, buy-and-bill margins, electronic ordering systems, and state-level substitution rules will determine the speed of adoption.
What patent litigation and settlement issues affect Prolia?
Denosumab biosimilar litigation is governed by the BPCIA patent-exchange process, often called the patent dance. A biosimilar applicant can disclose its application and manufacturing information to the reference-product sponsor, allowing the parties to identify patents for potential litigation. The applicant can also provide notice of commercial marketing before launch.
Potential disputes involve:
- Patent validity.
- Patent infringement.
- Whether a claim covers the biosimilar manufacturing process.
- Whether the applicant complied with BPCIA procedures.
- Launch timing under a settlement agreement.
- Allocation of indications and commercial channels.
Publicly disclosed settlement terms can materially affect revenue forecasting because they may permit a biosimilar launch before the last asserted patent expires while preserving selected patent rights. Analysts should distinguish an FDA approval date from the actual permitted commercial launch date.
No conventional Orange Book Paragraph IV certification controls Prolia because Prolia is a biologic. Biosimilar challenges instead rely on the 351(k) pathway and BPCIA litigation mechanisms.
What formulation patents and manufacturing barriers matter?
The most commercially relevant formulation and manufacturing barriers are likely to involve:
- Protein stability during refrigerated storage.
- Prevention of aggregation and degradation.
- Syringe and container compatibility.
- Sterility assurance.
- Consistent glycosylation and charge profiles.
- Comparability of critical quality attributes.
- Scaled cell-culture and purification processes.
A biosimilar sponsor does not need to duplicate every manufacturing step, but it must demonstrate high similarity and exclude clinically meaningful differences. Manufacturing patents can therefore delay entry even when composition-of-matter protection has expired.
For Prolia, the prefilled syringe and low-frequency dosing model may also support device, packaging, and administration differentiation. These protections generally have less blocking power than core biologic patents but can support brand retention and contracting.
How does Prolia compare with competing osteoporosis drugs?
| Product |
Active ingredient |
Dosing |
Competitive position |
| Prolia |
Denosumab |
Every six months |
Established biologic with recurring administration |
| Jubbonti |
Denosumab-bbdz |
Every six months |
First FDA-approved Prolia biosimilar |
| Evenity |
Romosozumab |
Monthly for 12 months |
Anabolic and antiresorptive activity; cardiovascular warnings limit use |
| Fosamax and generics |
Alendronate |
Usually weekly |
Low-cost first-line therapy |
| Reclast and generics |
Zoledronic acid |
Usually annually |
Infusion option with durable dosing |
| Forteo and generics |
Teriparatide |
Daily |
Anabolic therapy for selected high-risk patients |
Prolia's main advantages are dosing convenience, broad physician familiarity, and effectiveness in patients who cannot tolerate or adhere to oral bisphosphonates. Its main disadvantages include injection administration, higher cost, hypocalcemia and osteonecrosis-related safety monitoring, and the need for follow-on antiresorptive therapy after discontinuation.
What is Prolia's geographic coverage and international outlook?
The United States is the primary profit pool, but Prolia is marketed broadly across Europe, Japan, Canada, and other regulated markets. International biosimilar timing will differ because of:
- National reimbursement procedures.
- Local patent and supplementary protection rules.
- Tender systems.
- Reference-product pricing.
- Regional requirements for extrapolation.
- Physician and hospital procurement practices.
Europe typically has stronger biosimilar uptake in hospital and reimbursed settings, but osteoporosis treatment is often fragmented across primary care, specialists, and outpatient providers. The United States may preserve higher branded pricing for longer while facing larger absolute revenue exposure.
What is the likely Prolia financial trajectory?
Prolia is likely to follow a three-stage trajectory:
- Continued growth or stability through the early biosimilar transition.
- Net-price pressure as payers negotiate preferred status.
- Volume erosion as multiple biosimilars gain access and physicians switch new and existing patients.
A reasonable commercial framework is:
| Period |
Expected direction |
| 2025 |
Sales remain supported by the installed base; launch and contracting pressure begin |
| 2026-2027 |
Biosimilar share gains become visible in U.S. volume and net price |
| 2028 onward |
Erosion depends on the number of competitors and substitution policy |
Amgen's response will likely include contracting, patient-support programs, supply reliability, evidence generation, and continued promotion of adherence and continuity of care. The company may also use its broader denosumab manufacturing and commercial infrastructure to defend both Prolia and Xgeva.
Key Takeaways
- Prolia is a major Amgen growth product with approximately $4.5 billion in 2024 global sales.
- U.S. biologic exclusivity expired in 2022, but direct competition arrived later.
- Sandoz's Jubbonti was FDA-approved in March 2025 as a Prolia biosimilar.
- Biosimilar entry, not conventional generic substitution, is the central commercial risk.
- Prolia's recurring six-month dosing and physician-administered model may slow switching.
- Revenue erosion is likely to begin with rebates and new-patient substitution before broad displacement of stable patients.
- Manufacturing complexity and formulation, device, and process patents remain relevant barriers.
- The product's long-term value depends on payer policy, biosimilar competition, and Amgen's ability to preserve treatment continuity.
FAQs About Prolia Market Exclusivity and Biosimilar Competition
Is Prolia still patent protected?
Prolia's commercial protection is based on a combination of patent rights, biologic exclusivity history, manufacturing know-how, formulation protection, and litigation rights. Foundational protection has diminished, but later patents and process claims can still affect biosimilar launch timing.
Is Jubbonti interchangeable with Prolia?
FDA biosimilar approval and pharmacy-level interchangeability are separate regulatory concepts. The commercial effect of Jubbonti depends on its approved status, payer rules, state substitution laws, and physician or health-system policies.
Will Prolia lose market share to Evenity?
Evenity is a clinical competitor but not a direct biosimilar substitute. Its monthly dosing, treatment duration, and safety considerations position it for selected high-risk patients rather than broad replacement of Prolia.
Why can Prolia sales keep growing after patent exclusivity ends?
Biosimilar development takes time, and physician-administered biologics do not always undergo automatic pharmacy substitution. Brand familiarity, reimbursement contracts, clinical continuity, and patient-support programs can preserve demand after statutory exclusivity ends.
What happens when a patient stops Prolia?
Stopping Prolia without a suitable follow-on treatment can lead to rapid rebound in bone turnover and increased vertebral-fracture risk. FDA labeling recommends transition planning with another antiresorptive therapy.[1]
References
- U.S. Food and Drug Administration. (2024). Prolia prescribing information. https://www.accessdata.fda.gov
- Amgen Inc. (2022). 2021 annual report.
- Amgen Inc. (2023). 2022 annual report.
- Amgen Inc. (2024). 2023 annual report.
- Amgen Inc. (2025). 2024 annual report.
- Biologics Price Competition and Innovation Act of 2009, 42 U.S.C. § 262.
- U.S. Food and Drug Administration. (2024). Purple Book: Database of licensed biological products. https://purplebooksearch.fda.gov
- U.S. Food and Drug Administration. (2025). FDA approves denosumab biosimilars Jubbonti and Wyost. https://www.fda.gov