Last updated: November 8, 2026
Zerbaxa, the brand name for ceftolozane and tazobactam, is a hospital antibiotic marketed by Merck & Co. for serious Gram-negative bacterial infections. Its commercial value is supported by activity against difficult-to-treat Pseudomonas aeruginosa, but sales are constrained by antimicrobial stewardship, restricted hospital use, competition from other beta-lactam/beta-lactamase inhibitor products, and limited disclosure of product-level revenue by Merck.
The principal commercial question is not near-term demand collapse. It is whether Zerbaxa can sustain premium pricing and formulary preference through the late 2020s before U.S. patent protection begins to weaken. No broadly available U.S. generic version had displaced the branded product in public FDA market information through 2024.
What is Zerbaxa approved to treat?
Zerbaxa combines two components:
| Component |
Role |
| Ceftolozane |
A cephalosporin antibiotic with strong activity against Pseudomonas aeruginosa |
| Tazobactam |
A beta-lactamase inhibitor that protects ceftolozane from selected beta-lactamases |
The FDA approved Zerbaxa in December 2014 for complicated intra-abdominal infections, in combination with metronidazole, and complicated urinary tract infections, including pyelonephritis. In June 2019, the FDA expanded the label to hospital-acquired bacterial pneumonia and ventilator-associated bacterial pneumonia in adults. The pneumonia indication materially broadened Zerbaxa’s hospital use case, but it also placed the product in a highly competitive and stewardship-sensitive market.[1]
Zerbaxa is administered intravenously. It is used primarily in hospitals and other acute-care settings rather than through retail pharmacies.
What pathogens and resistance mechanisms does Zerbaxa address?
Zerbaxa is positioned against serious infections caused by susceptible Gram-negative organisms, including:
- Pseudomonas aeruginosa
- Escherichia coli
- Klebsiella pneumoniae
- Enterobacter cloacae complex
- Certain other Enterobacterales
Its strongest commercial differentiation is its antipseudomonal profile. The drug is not a universal solution for carbapenem-resistant Enterobacterales or all beta-lactamase-producing pathogens. Its activity is limited against organisms producing certain enzymes, including many metallo-beta-lactamases and some carbapenemases. Clinical laboratories and infectious-disease specialists therefore use susceptibility data and resistance-mechanism testing to determine treatment selection.
How large is the Zerbaxa market?
Zerbaxa competes in the hospital anti-infective segment, where annual revenue is driven by infection incidence, resistance patterns, formulary rules, hospital budgets, and the availability of lower-cost alternatives.
The addressable market has several layers:
- Broad hospital antibiotic demand, including pneumonia, urinary tract infections, and intra-abdominal infections.
- Resistant Gram-negative infections requiring newer or specialized agents.
- The narrower subgroup of patients with confirmed or suspected difficult-to-treat Pseudomonas infections.
- Salvage or escalation therapy after failure or resistance to older beta-lactams.
The third and fourth segments are the most commercially relevant for Zerbaxa. They support price and clinical differentiation but limit volume because hospitals generally reserve newer antibiotics for patients with resistant pathogens or a high risk of treatment failure.
How does Zerbaxa compare with competing antibiotics?
| Product |
Active ingredients |
Principal competitive position |
| Zerbaxa |
Ceftolozane/tazobactam |
Strong antipseudomonal positioning; used for resistant Gram-negative infections |
| Avycaz |
Ceftazidime/avibactam |
Broad activity against several resistant Enterobacterales and selected Pseudomonas strains |
| Vabomere |
Meropenem/vaborbactam |
Strong position against KPC-producing Enterobacterales |
| Fetroja |
Cefiderocol |
Siderophore cephalosporin for complicated resistant Gram-negative infections |
| Recarbrio |
Imipenem/cilastatin/relebactam |
Broad hospital use against selected resistant Gram-negative pathogens |
| Cefepime, piperacillin/tazobactam, meropenem |
Older generic agents |
Lower-cost empiric and directed-treatment alternatives |
Zerbaxa’s principal differentiation is not broad-spectrum coverage across every resistance mechanism. It is targeted antipseudomonal performance, particularly when standard agents are unreliable. Avycaz is its most direct branded comparator in many hospital formulary decisions, while cefiderocol and Recarbrio compete for resistant Gram-negative cases.
What is the FDA regulatory status of Zerbaxa?
Zerbaxa is an FDA-approved small-molecule intravenous antibiotic marketed under NDA 206829. Its principal regulatory milestones are:
| Date |
Regulatory or commercial event |
| December 19, 2014 |
FDA approval for complicated intra-abdominal infections and complicated urinary tract infections |
| June 2019 |
FDA approval for hospital-acquired bacterial pneumonia and ventilator-associated bacterial pneumonia |
| 2015 |
Merck acquired Cubist Pharmaceuticals and assumed control of Zerbaxa commercialization |
| 2020-2021 |
Hospital utilization was affected by pandemic-driven changes in elective procedures, admissions, and antibiotic prescribing |
| 2022-2024 |
Commercial focus remained on resistant Gram-negative infections and acute-care hospital use |
The product originated with Cubist Pharmaceuticals. Merck acquired Cubist in 2015 for approximately $9.5 billion, expanding its hospital anti-infective portfolio.[2]
Zerbaxa does not have the biologic complexity associated with a monoclonal antibody or other biologic product. Biosimilar risk is therefore not relevant. The principal future threat is an ANDA-based generic, not a biosimilar.
What patents protect Zerbaxa?
Zerbaxa’s protection is based primarily on patents covering ceftolozane, pharmaceutical compositions, combinations with tazobactam, and related manufacturing or formulation subject matter. The composition and product-related patent estate extends well beyond the original 2014 approval date.
A representative public patent record includes the following U.S. patent family:
| Patent |
General subject matter |
Commercial relevance |
| US 8,183,208 |
Ceftolozane compounds and related pharmaceutical applications |
Core active-ingredient protection |
| Related continuation and divisional filings |
Ceftolozane compositions, combinations, and use claims |
Potential additional barriers to ANDA launch |
| Product-specific Orange Book listings |
Approved drug, composition, and method-of-use claims |
Creates certification obligations for generic applicants |
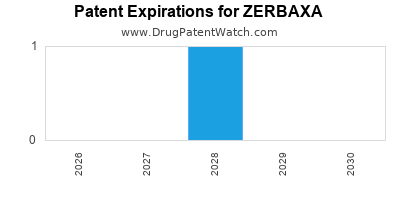
Public patent databases generally place the core U.S. patent protection in the 2029 range, subject to patent-term adjustment, patent-term extension, pediatric exclusivity, and the precise claim or patent being evaluated.[3]
The effective generic-entry date can therefore differ from the simple expiration date of the earliest patent. A generic applicant must address each relevant Orange Book patent through a Paragraph III certification, Paragraph IV certification, or, where applicable, a statement that the patent is not infringed or is invalid.
What formulations are protected by Zerbaxa patents?
The commercially important formulation is an intravenous powder for reconstitution. Patent protection may cover:
- Ceftolozane and tazobactam combinations
- Specific ratios or salt forms
- Stable injectable compositions
- Lyophilized or powder formulations
- Manufacturing processes and purification steps
- Methods for treating infections caused by susceptible Gram-negative pathogens
Formulation and process patents usually create less durable protection than a valid active-ingredient patent, but they can complicate generic development. An ANDA sponsor can sometimes design around formulation claims while still facing core compound claims.
When does Zerbaxa lose exclusivity?
Zerbaxa’s practical U.S. exclusivity timeline has three separate elements:
| Exclusivity category |
Expected impact |
| FDA regulatory exclusivity |
Original approval did not create a long orphan-drug exclusivity period because Zerbaxa was not approved as an orphan product |
| Patent exclusivity |
Core protection is publicly reported into approximately 2029 |
| Pediatric exclusivity |
Any applicable six-month pediatric extension would attach to eligible patents or exclusivity periods and could shift the effective date |
Zerbaxa’s patent protection is therefore more important than statutory FDA exclusivity. The first commercially meaningful U.S. generic launch is most likely to depend on:
- The final Orange Book patent list.
- The validity and scope of the core ceftolozane patent claims.
- The timing of any Paragraph IV filing.
- The outcome of patent litigation.
- Whether the generic applicant receives a 180-day first-filer period.
A 2029 patent expiration does not guarantee immediate generic availability. Litigation, regulatory review, manufacturing readiness, and hospital contracting can shift the actual launch date.
Are there Paragraph IV challenges to Zerbaxa?
A Paragraph IV certification asserts that an Orange Book-listed patent is invalid, unenforceable, or not infringed. It is the principal mechanism through which an ANDA applicant seeks to launch before listed patent expiration.
Publicly available information through 2024 did not show a widely reported, market-disrupting U.S. Paragraph IV litigation campaign against Zerbaxa comparable to the litigation activity involving major retail drugs. There was also no broadly commercialized generic ceftolozane/tazobactam product publicly identified in the U.S. market during that period.
The absence of a visible challenge does not eliminate future risk. Zerbaxa’s relatively specialized hospital market may reduce the economic incentive for early litigation. An ANDA sponsor must spend heavily on sterile injectable development, regulatory work, manufacturing validation, and hospital commercialization before it can capture revenue. That investment is more attractive when the expected post-launch volume is large enough to support a rapid payback.
How strong is the Zerbaxa patent estate?
Zerbaxa’s patent estate is commercially meaningful but not uniformly strong across every claim type.
Strengths
- Core ceftolozane composition protection provides the most important barrier.
- Intravenous formulation and combination claims can create additional litigation targets.
- Complex sterile manufacturing requirements raise the cost of generic entry.
- Hospital antibiotic products can retain brand demand after initial generic launch when clinical protocols are conservative.
Weaknesses
- The product is a small molecule, so it is legally exposed to the ANDA pathway rather than the more complex biosimilar pathway.
- Older antibiotic patents may face validity attacks based on obviousness, written description, enablement, or prior-art arguments.
- Hospitals generally favor lower-cost generics when clinical interchangeability is established.
- Method-of-use claims may have limited commercial value if a generic can rely on a section viii carve-out or omit the patented indication.
Patent strength is highest for a valid compound claim that covers the active ceftolozane structure. It is lower for narrow treatment claims or formulation claims that can be designed around.
What generic entry risks exist for Zerbaxa?
The generic-entry risk profile is moderate before core patent expiry and high after the core patent barrier falls.
Pre-expiration risk
Before 2029, the principal risks are:
- Paragraph IV litigation
- An at-risk launch after a favorable court decision
- Narrow-label entry that omits protected indications
- Competing branded products gaining formulary preference
- Hospital purchasing pressure forcing net-price concessions
Post-expiration risk
After core patent expiry, Zerbaxa may face:
- One or more ANDA-approved sterile injectables
- Rapid price erosion through group purchasing organizations
- Hospital substitution protocols
- Reduced Merck promotional spending
- Loss of premium pricing for resistant-infection use
The market may not experience the extreme erosion seen in large-volume oral drugs. Sterile injectable antibiotics require more complex manufacturing and quality control. Supply reliability can also support continued branded or authorized-generic demand. Even so, a successful generic competitor would likely reduce Zerbaxa’s net price and market share materially.
What is the financial trajectory of Zerbaxa?
Merck does not consistently disclose Zerbaxa revenue as a separate, recurring line item in the same detail it provides for Keytruda, Gardasil, Januvia, Bridion, or other major products. Zerbaxa is generally included within broader hospital acute-care or other pharmaceutical product categories.
That reporting structure limits the ability to calculate a precise annual Zerbaxa revenue series from Merck’s consolidated filings. The available financial picture is directional:
| Period |
Financial interpretation |
| 2015-2019 |
Commercial expansion after the Cubist acquisition, supported by the pneumonia indication and growing focus on resistant Gram-negative infections |
| 2020-2021 |
Hospital disruption from COVID-19 affected procedure volumes, admissions, diagnostic patterns, and antibiotic utilization |
| 2022-2024 |
Recovery in hospital activity, offset by stewardship restrictions, competition, and limited use outside high-risk infections |
| 2025-2028 |
Likely mature-brand period, with value dependent on formulary position, resistance epidemiology, and price discipline |
| Around 2029 onward |
Material generic-entry and price-erosion risk if core patent protection expires without a successful challenge or new exclusivity |
Zerbaxa is unlikely to be a major driver of Merck’s total corporate revenue. Its financial importance is strategic rather than transformational. It provides an established hospital product with clinical value in resistant infections, but it does not approach the scale of Merck’s oncology, vaccine, or immunology franchises.
The asset’s profitability depends on specialty pricing and hospital access rather than high prescription volume. Its economics are supported by low manufacturing volume relative to mass-market antibiotics, but that advantage is balanced by specialized sales infrastructure and hospital procurement pressure.
What licensing deals affect Zerbaxa?
The key transaction was Merck’s acquisition of Cubist Pharmaceuticals in 2015. Cubist had developed and commercialized Zerbaxa as part of its hospital-focused anti-infective portfolio. Merck’s acquisition transferred the product, related intellectual property, commercial infrastructure, and development programs to Merck.[2]
No later licensing transaction is as commercially central to Zerbaxa as the Cubist acquisition. The product is marketed by Merck rather than through a widely reported partner-led commercialization structure.
What patent litigation affects Zerbaxa?
No major publicly reported U.S. patent judgment had reset Zerbaxa’s commercial timeline through 2024. The key litigation risk remains prospective rather than historical:
- A future ANDA Paragraph IV filing could trigger a Hatch-Waxman suit.
- A timely lawsuit could impose a statutory 30-month stay on FDA approval, subject to court action and other statutory exceptions.
- A successful generic challenge could move entry ahead of the listed patent expiration date.
- A settlement could establish a negotiated entry date, potentially with an authorized generic or other commercial restrictions.
Settlement terms in antibiotic patent cases can materially change market value even when a brand retains nominal patent protection. The economic result depends on entry timing, volume limits, authorized-generic provisions, and the number of settling ANDA sponsors.
How does Zerbaxa compare with Avycaz and Fetroja?
| Factor |
Zerbaxa |
Avycaz |
Fetroja |
| Core strength |
Pseudomonas coverage |
Selected resistant Enterobacterales and Pseudomonas |
Difficult-to-treat Gram-negative infections |
| Dosage form |
Intravenous |
Intravenous |
Intravenous |
| Main buyer |
Acute-care hospitals |
Acute-care hospitals |
Acute-care hospitals |
| Stewardship position |
Reserved use for resistant infections |
Reserved use for resistant infections |
Highly targeted use |
| Generic risk |
Small-molecule ANDA risk near patent expiry |
Small-molecule ANDA risk |
Small-molecule ANDA risk |
| Main commercial constraint |
Restricted use and competition |
Resistance-mechanism differentiation |
Narrow clinical positioning and evidence requirements |
Zerbaxa has the clearest commercial identity in difficult-to-treat Pseudomonas infections. Avycaz is often favored when the resistance mechanism points toward avibactam-sensitive beta-lactamases. Fetroja competes as a later-line option when resistance limits conventional beta-lactam choices.
What geographic coverage does Zerbaxa have?
Zerbaxa is marketed internationally, but the United States is the most important reference market for its regulatory, patent, and pricing profile. European and other markets are governed by separate national or regional patent rights, reimbursement rules, hospital tenders, and antimicrobial stewardship policies.
International revenue can decline earlier than U.S. revenue where:
- Patent terms expire sooner.
- Hospital tenders force lower prices.
- Reimbursement agencies impose stricter restrictions.
- Generic or local injectable competitors enter the market.
- Zerbaxa is reserved for narrower indications.
The U.S. remains the central market for assessing Paragraph IV risk and the value of the Orange Book patent estate.
Key Takeaways
- Zerbaxa is Merck’s ceftolozane/tazobactam intravenous antibiotic for serious Gram-negative infections.
- Its main differentiation is activity against difficult-to-treat Pseudomonas aeruginosa.
- FDA approval covers complicated intra-abdominal infections, complicated urinary tract infections, and hospital- or ventilator-associated bacterial pneumonia.
- Zerbaxa competes with Avycaz, Vabomere, Fetroja, Recarbrio, and lower-cost generic antibiotics.
- Merck does not provide a consistently separate public revenue series for Zerbaxa, so exact annual product sales cannot be established from standard consolidated disclosures.
- The product’s commercial trajectory is mature and specialty-focused rather than high-volume.
- Core U.S. patent protection is publicly reported into approximately 2029, subject to the specific patent, patent-term adjustments, and any applicable pediatric extension.
- No major U.S. generic displacement or market-resetting Paragraph IV outcome was publicly evident through 2024.
- The largest future financial risk is sterile-injectable generic entry after core patent expiry.
- Biosimilar risk does not apply because Zerbaxa is a small-molecule drug.
FAQs About Zerbaxa Patent and Market Risk
Does Zerbaxa have orphan-drug exclusivity?
No. Zerbaxa’s commercial protection is driven primarily by patents and hospital-market positioning rather than orphan-drug exclusivity.
Is there a generic version of Zerbaxa?
No broadly commercialized U.S. generic version had displaced the branded product in public market information through 2024. Future ANDA entry remains possible as the core patent estate approaches expiration.
What is the main clinical advantage of Zerbaxa?
Its main advantage is targeted activity against susceptible difficult-to-treat Gram-negative pathogens, especially Pseudomonas aeruginosa, where older beta-lactam antibiotics may be unreliable.
Can hospitals substitute a generic Zerbaxa automatically?
Substitution would depend on FDA approval, the generic label, state pharmacy law, hospital policy, formulary rules, procurement contracts, and clinical interchangeability assessments. Intravenous hospital products may require institutional approval even after generic approval.
Will Zerbaxa revenue grow materially before patent expiry?
Material growth is unlikely without increased resistance-driven utilization, stronger formulary preference, or additional approved uses. Merck’s sales trajectory is more likely to reflect stable specialty demand, hospital volume recovery, pricing pressure, and eventual generic-entry risk.
References
- U.S. Food and Drug Administration. (2014). Zerbaxa prescribing information. FDA.
- Merck & Co., Inc. (2015). Merck to acquire Cubist Pharmaceuticals. Merck investor relations.
- U.S. Patent and Trademark Office. (n.d.). U.S. Patent No. 8,183,208 and related ceftolozane patent records. USPTO.
- Merck & Co., Inc. (2024). 2023 annual report. Merck & Co.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. FDA.
- Infectious Diseases Society of America. (2024). Guidance on the treatment of antimicrobial-resistant Gram-negative infections. IDSA.