Last updated: September 14, 2026
Oleptro, the extended-release formulation of trazodone hydrochloride, achieved FDA approval but failed to establish a durable commercial position against low-cost immediate-release trazodone and other generic antidepressants. The product was launched in the United States by Zogenix after licensing rights from Labopharm. Its commercial value declined as prescribers and payers favored inexpensive generic trazodone. The FDA lists the original Oleptro product as discontinued, while trazodone remains widely available in immediate-release generic formulations.[1]
What is Oleptro and how does it compare with generic trazodone?
Oleptro is an extended-release tablet containing trazodone hydrochloride. It was developed to provide once-daily dosing for major depressive disorder and to improve tolerability relative to conventional trazodone dosing.
| Attribute |
Oleptro |
Generic trazodone immediate release |
| Active ingredient |
Trazodone hydrochloride |
Trazodone hydrochloride |
| Dosage form |
Extended-release tablet |
Immediate-release tablet |
| FDA indication |
Major depressive disorder |
Major depressive disorder |
| Typical dosing concept |
Once daily, usually at bedtime |
Divided or bedtime dosing |
| Original commercial sponsor |
Labopharm |
Multiple generic manufacturers |
| U.S. FDA approval |
2010 |
Earlier approvals for immediate-release products |
| Reimbursement position |
Branded product |
Low-cost generic |
| Market status |
Discontinued as an active branded product |
Widely marketed |
Oleptro’s principal commercial proposition was convenience. The formulation used proprietary extended-release technology intended to reduce peak-related adverse effects and permit once-daily administration. That differentiation was limited because generic immediate-release trazodone was inexpensive, familiar to prescribers, and frequently used off-label for insomnia.
When did Oleptro launch and lose commercial momentum?
The FDA approved Oleptro in November 2010 under NDA 022411. Labopharm developed the product and licensed U.S. commercialization to Zogenix. Zogenix launched Oleptro in 2011.[1][2]
Oleptro commercial timeline
| Year |
Event |
Commercial effect |
| 2010 |
FDA approval of Oleptro |
Created a branded extended-release trazodone market |
| 2011 |
U.S. launch by Zogenix |
Initial specialty-pharmaceutical commercialization |
| 2011-2013 |
Promotional and payer-access period |
Limited uptake against generic trazodone |
| 2014 onward |
Declining strategic importance within the commercial portfolio |
Lower revenue contribution and reduced promotional rationale |
| Later period |
Product discontinued from active commercial distribution |
Branded market opportunity effectively ended |
Oleptro did not generate the scale normally associated with a successful differentiated antidepressant. Its market faced three structural constraints:
- The active ingredient was already familiar and inexpensive.
- Immediate-release trazodone was prescribed for both depression and insomnia, expanding generic competition beyond the labeled indication.
- The extended-release benefit was convenient but not sufficiently valuable to overcome payer and prescriber price sensitivity.
What was Oleptro’s financial trajectory?
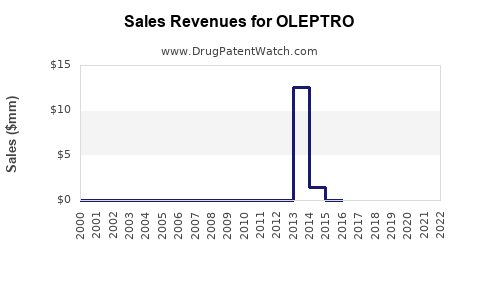
Oleptro produced modest branded revenue during the early Zogenix commercialization period, but the product did not become a major contributor to corporate sales. Public-company disclosures indicate that Oleptro revenue was meaningful enough to be reported during the launch period, but it remained substantially smaller than revenue from Zogenix’s higher-priority commercial products and did not support a long-term standalone franchise.[2][3]
Financial trajectory
| Phase |
Revenue profile |
Main driver |
| Pre-launch |
Development and licensing asset |
Labopharm investment in formulation and regulatory approval |
| 2011 launch |
Initial product revenue |
Market introduction and promotional activity |
| 2012-2013 |
Modest commercial revenue |
Early prescription adoption, limited differentiation |
| 2014 onward |
Declining strategic value |
Generic substitution, low reimbursement leverage, portfolio reprioritization |
| Discontinuation |
No continuing branded revenue base |
Withdrawal from active commercialization |
The commercial economics were unfavorable. The product required branded sales, medical education, payer contracting, and distribution support, but it competed with a molecule whose immediate-release versions were available at generic prices. That created a narrow pricing window. A branded extended-release product could command a premium only if it produced measurable adherence, tolerability, or clinical outcomes that payers considered worth reimbursing.
Zogenix’s filings show that Oleptro was not positioned as the company’s principal growth asset. The company’s strategic emphasis shifted toward specialty products and controlled-substance therapies with greater revenue potential.[2][3]
What competitive forces affected Oleptro sales?
Generic trazodone substitution
Generic trazodone was the central competitive threat. Physicians could prescribe immediate-release trazodone for depression at materially lower cost. Pharmacies and insurers also had strong incentives to substitute generic products.
Off-label insomnia use
Trazodone has long been used off label for insomnia. That practice increased the visibility of low-cost immediate-release products and reduced the need for a branded extended-release version. Oleptro was approved for depression, not insomnia, but it competed indirectly with the same molecule used for sleep-related prescribing.
Limited clinical differentiation
Oleptro’s principal advantage was delivery technology rather than a new pharmacological mechanism. It did not offer a new active ingredient, a novel therapeutic class, or a clearly superior antidepressant efficacy profile. Formulation differentiation generally has a shorter commercial life when the underlying molecule is mature and inexpensive.
Payer controls
A branded extended-release antidepressant faced formulary restrictions, prior authorization risk, and higher patient co-payments. Those barriers were difficult to overcome without strong comparative data or a substantial adherence benefit.
What patents protected Oleptro?
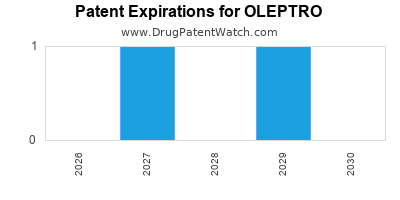
Oleptro was protected primarily by formulation and controlled-release technology rather than by composition-of-matter protection for trazodone. The active ingredient had been known for decades, so the commercial patent strategy depended on the extended-release dosage form, release profile, and related formulation claims.
Formulation patent exposure
The relevant patent estate was designed to cover:
- Extended-release trazodone tablets
- Controlled release of trazodone over a defined dosing interval
- Pharmaceutical compositions using specified excipients
- Once-daily administration
- Release characteristics intended to reduce peak plasma concentrations
The formulation-based nature of the estate limited exclusivity strength. A generic applicant could challenge the listed patents, design around particular excipient or release-profile claims, or seek approval for a different dosage form.
The most important commercial distinction was between FDA approval of the branded product and enforceable patent protection. Even where formulation patents remained listed, they did not protect the underlying trazodone molecule from generic use in immediate-release products.
What was the Orange Book status of Oleptro?
Oleptro was approved under FDA NDA 022411. The FDA Drugs@FDA database and Orange Book framework identify the product’s regulatory history, patents, and marketing status.[1]
The key regulatory points are:
- Oleptro was an NDA product, not a biologic.
- It was subject to the Hatch-Waxman framework.
- Generic competitors could file ANDAs, including Paragraph IV certifications against listed patents.
- The discontinuation of the branded product did not eliminate the market for trazodone.
- No biosimilar pathway applies because trazodone is a small-molecule drug.
An important distinction is that a product can be discontinued for commercial reasons without being withdrawn for safety or efficacy reasons. Oleptro’s commercial decline is consistent with market economics rather than a widely reported safety-based regulatory removal.
Were there Paragraph IV challenges or generic launches?
The principal generic risk was an ANDA challenge to the extended-release formulation patents. The public commercial record does not show a successful generic franchise that replaced Oleptro at significant scale. Immediate-release trazodone generics, however, provided a strong substitute throughout the product’s commercial life.
Generic entry scenarios
| Scenario |
Market effect |
| Immediate-release trazodone substitution |
Persistent pressure on branded prescriptions |
| Extended-release ANDA approval |
Direct price erosion against Oleptro |
| Formulation patent challenge |
Potential early entry and loss of premium pricing |
| Brand discontinuation without direct ER generic |
Continued use of generic immediate-release trazodone |
| Authorized generic strategy |
Possible price control, but limited value in a low-price molecule |
Because generic immediate-release trazodone was already available, Oleptro had less economic protection than a new chemical entity. Even a successful formulation patent position would not have insulated the brand from therapeutic substitution.
What patent litigation affected Oleptro?
Oleptro did not become associated with a major, high-value patent litigation campaign comparable to blockbuster drugs with billions of dollars in annual sales. The principal legal risk was conventional Hatch-Waxman exposure involving formulation patents and ANDA filings.
The absence of material litigation value reflects the product’s economics:
- Low expected branded sales reduced the incentive for prolonged litigation.
- Formulation patents are narrower than composition-of-matter patents.
- Generic immediate-release trazodone created a practical substitute.
- The commercial upside from defending the extended-release product was limited.
No major settlement agreement appears to have transformed the market position of Oleptro. The product’s decline was driven more by market substitution and portfolio economics than by a litigation settlement that preserved a defined period of exclusivity.
Did Oleptro have biosimilar risk?
No. Biosimilar risk is not applicable to Oleptro because trazodone is a chemically synthesized small molecule. The relevant competitive pathway was generic drug approval through an ANDA, not biosimilar approval under the Public Health Service Act.
The competitive risk hierarchy was:
- Generic immediate-release trazodone
- Potential generic extended-release trazodone
- Therapeutic substitution by other antidepressants
- Off-label use of generic trazodone for insomnia
Which companies competed with Oleptro?
Oleptro competed with several groups rather than a single branded rival.
Direct and indirect competitors
- Generic manufacturers of immediate-release trazodone
- Branded antidepressants, including selective serotonin reuptake inhibitors
- Serotonin-norepinephrine reuptake inhibitors
- Other sedating antidepressants used at bedtime
- Low-cost generic sleep therapies
- Specialty pharmacies and payer formularies favoring generic substitution
The most important competitor was not another branded extended-release trazodone product. It was generic immediate-release trazodone, supported by decades of physician familiarity and broad prescribing flexibility.
What licensing deals affected Oleptro?
Labopharm licensed U.S. commercialization rights to Zogenix, which assumed responsibility for launching and promoting Oleptro in the United States.[2] The arrangement allowed Labopharm to commercialize an internally developed formulation without building a large U.S. sales organization.
The licensing structure also affected value distribution:
- Labopharm retained development and intellectual-property interests.
- Zogenix incurred commercialization costs and assumed market-execution risk.
- The limited branded market constrained royalty and milestone potential.
- Zogenix’s later portfolio priorities reduced the strategic value assigned to Oleptro.
The deal was commercially rational at launch because it transferred U.S. commercialization to a specialty pharmaceutical company. It did not solve the underlying problem of weak differentiation against generic trazodone.
How strong was the Oleptro patent estate?
Oleptro’s patent estate was moderate to weak from a commercial perspective.
Strengths
- The extended-release dosage form created a legally distinct product.
- Formulation claims could delay or complicate direct generic entry.
- The FDA-approved once-daily product had a clear regulatory identity.
Weaknesses
- No new chemical entity protection existed for trazodone.
- Immediate-release generic competition remained available.
- Formulation patents were more vulnerable to design-around strategies.
- The product’s premium depended on convenience rather than a major clinical outcome advantage.
- Low revenue reduced the economic rationale for aggressive enforcement.
The estate could protect a specific extended-release product, but it could not protect the broader trazodone market.
What is the outlook for Oleptro revenue and generic launch risk?
Oleptro has no meaningful current branded-growth thesis. Its commercial opportunity ended with the erosion of branded demand and discontinuation of active marketing. Any residual value would depend on a reintroduction strategy, a new formulation, or a licensing transaction, not on the legacy product’s existing market position.
A relaunch would face:
- Established generic trazodone pricing
- Limited payer willingness to reimburse a premium
- Weak prescriber switching incentives
- No biosimilar or biologic barrier
- Limited remaining brand equity
- Possible need for new clinical evidence to support adherence or tolerability claims
The most realistic commercial scenario is continued dominance by generic immediate-release trazodone, with limited demand for any extended-release product unless it demonstrates a measurable clinical or adherence advantage.
Key Takeaways
- Oleptro is an extended-release trazodone product approved by the FDA in 2010.
- Zogenix launched the product in the United States after licensing rights from Labopharm.
- Sales remained modest and declined as generic trazodone dominated prescribing and reimbursement.
- The patent estate focused on formulation and controlled-release technology, not the trazodone molecule.
- Immediate-release generic trazodone was the main commercial threat throughout Oleptro’s life.
- Paragraph IV and formulation-patent risks were secondary to the broader problem of therapeutic substitution.
- Biosimilar competition does not apply because trazodone is a small molecule.
- Oleptro’s current commercial value is negligible absent a substantially differentiated relaunch.
FAQs
Is Oleptro still available in the United States?
The original Oleptro branded product is listed as discontinued in FDA product databases. Trazodone remains available primarily through immediate-release generic products.[1]
Is Oleptro the same as trazodone?
Oleptro contains trazodone hydrochloride but uses an extended-release formulation. Conventional generic trazodone is generally immediate release.
Can generic trazodone replace Oleptro?
Physicians may consider generic trazodone as an alternative, but substitution depends on dosage, release characteristics, clinical response, and prescribing instructions.
Did Oleptro qualify for new chemical entity exclusivity?
No. Oleptro used the previously known active ingredient trazodone. Its commercial protection depended on formulation-related rights rather than new chemical entity exclusivity.
Is there an investment case based on Oleptro patents?
The legacy Oleptro asset has limited standalone investment value. Generic competition, product discontinuation, and the absence of composition-of-matter protection materially reduce the likelihood of significant future revenue.
References
- U.S. Food and Drug Administration. (2010). Oleptro prescribing information and Drugs@FDA application data, NDA 022411.
- Zogenix, Inc. (2011). Annual report on Form 10-K. U.S. Securities and Exchange Commission.
- Zogenix, Inc. (2014). Annual report on Form 10-K. U.S. Securities and Exchange Commission.
- Labopharm Inc. (2010). Annual report and product licensing disclosures.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. FDA Orange Book.