Last updated: September 7, 2026
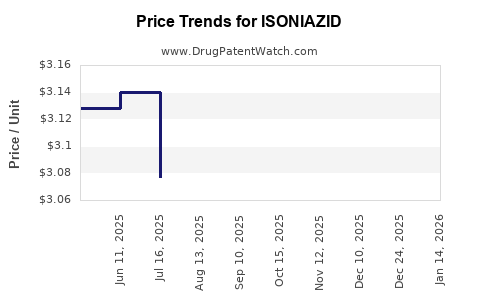
Isoniazid is a mature, low-cost tuberculosis medicine with limited commercial growth potential. Its market is driven by public-health procurement, tuberculosis incidence, latent tuberculosis infection screening, and national treatment programs rather than branded pricing or patent exclusivity. Standalone isoniazid has no meaningful current patent barrier in the United States, and generic competition keeps prices low. Financial upside is concentrated in reliable supply, combination products, government tenders, and manufacturing scale.
What is isoniazid used for?
Isoniazid is a first-line antituberculosis medicine used to treat active tuberculosis as part of combination therapy and to prevent tuberculosis in people with latent infection. It is available as a tablet, oral solution, and injectable formulation in certain markets. It is also combined with rifapentine, rifampin, and pyrazinamide in tuberculosis treatment or preventive regimens.
Isoniazid inhibits mycolic-acid synthesis in Mycobacterium tuberculosis. Resistance develops rapidly when it is used alone for active tuberculosis, so standard treatment combines isoniazid with other agents.
The main commercial demand segments are:
| Segment |
Commercial role |
| Active tuberculosis treatment |
Core volume demand, usually through public-health procurement |
| Latent tuberculosis infection treatment |
Important in high-income countries and targeted screening programs |
| Fixed-dose combinations |
Supports procurement efficiency and adherence |
| Pediatric treatment |
Smaller volume, with demand for dispersible tablets and liquid formulations |
| Drug-resistant tuberculosis |
Isoniazid-resistant disease reduces use, although susceptibility-guided treatment can retain a role |
| Private retail market |
Limited relative to government and institutional purchasing |
The Centers for Disease Control and Prevention recommends several latent tuberculosis infection regimens, including isoniazid-based treatment and shorter rifamycin-based alternatives. The shorter regimens have reduced the relative role of isoniazid in some prevention markets, particularly where adherence and completion rates are priorities (CDC, 2020).
How large is the isoniazid market?
No major pharmaceutical company reports standalone global revenue for isoniazid. The product is sold mainly as a generic active pharmaceutical ingredient, finished dosage form, or component of fixed-dose combinations. Public companies generally report it within broader infectious-disease, hospital, emerging-market, or government-contract revenue categories.
The addressable market is better measured through disease burden and treatment volumes than through branded sales. The World Health Organization estimated that approximately 10.6 million people developed tuberculosis globally in 2022, including about 7.5 million people newly diagnosed and reported for treatment. Tuberculosis caused approximately 1.3 million deaths among HIV-negative people and another 167,000 deaths among people with HIV in that year (WHO, 2023).
Demand for isoniazid therefore depends on:
- The number of patients diagnosed with drug-susceptible tuberculosis.
- The number of people treated for latent tuberculosis infection.
- National use of isoniazid-containing fixed-dose combinations.
- Procurement policies favoring shorter rifamycin-based prevention regimens.
- Availability of rifampin, rifapentine, pyrazinamide, and other companion drugs.
- The prevalence of isoniazid resistance.
The market is structurally large in treatment volume but small in commercial value per patient.
What drives isoniazid market growth?
Isoniazid volume growth is linked to tuberculosis control programs, not conventional pharmaceutical market expansion.
Tuberculosis incidence and diagnosis
Higher case detection increases demand for first-line treatment. Expanded screening among household contacts, migrants, prisoners, health-care workers, and people with HIV can increase latent-infection treatment volumes.
Public-health funding
The Global Fund, national tuberculosis programs, the U.S. President’s Emergency Plan for AIDS Relief, and other institutional purchasers influence procurement volumes. Government tenders commonly prioritize unit price, registration status, quality certification, delivery reliability, and inclusion in treatment guidelines.
Fixed-dose combinations
Fixed-dose combinations reduce pill burden and can improve procurement and adherence. Isoniazid is commonly included with rifampin, pyrazinamide, and ethambutol during the intensive or continuation phases of tuberculosis treatment.
Pediatric formulations
Dispersible tablets and age-appropriate formulations are commercially relevant because pediatric tuberculosis diagnosis and treatment remain operationally difficult. The market is smaller than the adult market but can command better pricing than basic adult tablets when formulation quality and regulatory approval are differentiated.
Supply security
Shortages of tuberculosis medicines can shift procurement toward suppliers with validated manufacturing capacity, regulatory compliance, and inventory. This creates an opportunity for dependable manufacturers even when product prices remain low.
When does isoniazid lose exclusivity?
Isoniazid lost meaningful market exclusivity decades ago. The active ingredient was introduced in the early 1950s, and the current market is generic.
There is no commercially significant originator exclusivity period for conventional isoniazid tablets or oral solution in the United States. Generic manufacturers compete primarily through abbreviated new drug applications, manufacturing cost, supply reliability, and procurement access.
The relevant commercial position is:
| Exclusivity category |
Current position |
| Active-ingredient patent |
Expired |
| Original product patent |
Expired |
| New chemical entity exclusivity |
Expired |
| Current brand protection |
Generally absent for commodity products |
| Pediatric exclusivity |
Not a current market barrier for conventional products |
| Orphan exclusivity |
Not applicable |
| Biosimilar exclusivity |
Not applicable |
| Formulation exclusivity |
Possible only for specific newer combinations or delivery technologies |
What is the FDA regulatory status of isoniazid?
Isoniazid is an FDA-approved prescription antituberculosis drug. FDA-approved labeling identifies it for active tuberculosis treatment in combination with other antituberculosis agents and for latent tuberculosis infection treatment under appropriate clinical protocols (FDA, 2023).
The FDA-approved product category includes conventional oral dosage forms. Regulatory requirements focus on:
- Demonstration of pharmaceutical equivalence for generic products.
- Assay, dissolution, impurity, and stability controls.
- Manufacturing compliance.
- Bioequivalence where required.
- Accurate warnings concerning hepatotoxicity and peripheral neuropathy.
- Appropriate labeling for combination treatment.
Isoniazid is associated with clinically important liver toxicity. Pyridoxine supplementation is commonly used for patients at higher risk of neuropathy, including some people with diabetes, malnutrition, HIV infection, pregnancy, renal disease, alcoholism, or seizure disorders.
What patent protections cover isoniazid?
The conventional isoniazid molecule has no material surviving patent protection. Patent risk is concentrated in specific product configurations rather than the active ingredient.
Potentially relevant patent categories include:
| Patent category |
Relevance |
| Fixed-dose combinations |
May cover ratios, compositions, release profiles, or manufacturing processes |
| Pediatric dispersible formulations |
May protect excipient systems or taste-masking technology |
| Long-acting delivery systems |
Could cover implants, depot systems, or specialized release technologies |
| Combination prevention regimens |
May cover combinations involving rifapentine or rifampin, although protection generally attaches to the combination rather than isoniazid itself |
| Manufacturing processes |
May protect a process in limited jurisdictions if still enforceable |
| Diagnostic-linked treatment methods |
Usually commercial value is limited and claim scope is narrow |
For ordinary isoniazid tablets, patent litigation and Paragraph IV activity are unlikely to be major commercial factors. Any challenge would normally concern a specific branded combination, formulation, or delivery platform rather than generic isoniazid itself.
How strong is the isoniazid patent estate?
The patent estate is weak for standalone isoniazid and potentially more relevant for newer combinations or delivery technologies.
Standalone product strength
Standalone isoniazid has:
- No meaningful active-ingredient exclusivity.
- Multiple generic suppliers.
- Low switching costs for purchasers.
- Limited differentiation among standard tablets.
- High exposure to tender pricing.
Combination-product strength
Combination products can have stronger intellectual-property positions when they incorporate:
- Novel dosing schedules.
- Improved pharmacokinetics.
- Pediatric delivery systems.
- Taste-masking technology.
- Extended-release formulations.
- New combinations with rifapentine or other tuberculosis agents.
Even where patents exist, enforcement may have limited commercial effect because public-health procurement often favors low-cost alternatives and because generic suppliers can avoid narrow formulation claims.
What generic entry risks exist for isoniazid?
Generic entry risk is already realized rather than prospective. The market contains multiple generic manufacturers across the United States, Europe, India, China, Africa, and other regions.
The principal risks to a supplier are commercial:
- Price compression in government tenders.
- Loss of contracts after quality or delivery failures.
- Substitution by fixed-dose combinations.
- Reduced latent-infection use because of shorter rifamycin-based regimens.
- Manufacturing interruptions involving active ingredient or companion drugs.
- Increased isoniazid resistance.
- Procurement consolidation by international organizations and national programs.
The main barrier is not patent infringement. It is achieving adequate manufacturing economics while meeting quality standards and maintaining uninterrupted supply.
Which companies and manufacturers compete in isoniazid?
Competition is fragmented. It includes generic pharmaceutical companies, contract manufacturers, regional tuberculosis specialists, and suppliers participating in government procurement.
Relevant competitive groups include:
- Indian generic manufacturers with large tuberculosis portfolios.
- Chinese active pharmaceutical ingredient producers.
- European and U.S. generic suppliers.
- Regional manufacturers supplying national tuberculosis programs.
- Contract manufacturers producing fixed-dose combinations.
- International procurement suppliers qualifying products for Global Fund-supported programs.
Company-level revenue attribution is difficult because most suppliers do not disclose isoniazid sales separately. The commercially relevant differentiators are product registration, World Health Organization prequalification where applicable, national tender eligibility, manufacturing scale, and supply reliability.
What is the financial trajectory for isoniazid?
The expected financial trajectory is stable to declining in unit value, with periodic volume increases caused by public-health programs or tuberculosis outbreaks.
| Financial factor |
Expected effect |
| Unit price |
Downward pressure from generic competition |
| Treatment volume |
Stable or modestly increasing with tuberculosis incidence and diagnosis |
| Gross margin |
Low for standard tablets; higher for specialized formulations |
| Revenue visibility |
Moderate under government contracts, weak in open-market retail |
| Growth potential |
Limited for standalone product |
| Supply-chain value |
High during shortages or procurement disruptions |
| Combination-product value |
Higher than standalone isoniazid |
| R&D return |
Low for conventional formulations, potentially higher for differentiated delivery |
A manufacturer with efficient production may generate recurring revenue from high-volume contracts, but isoniazid is unlikely to produce material branded-pharmaceutical margins. Financial performance depends on capacity utilization, raw-material prices, tender wins, currency exposure, regulatory compliance, and logistics.
The most attractive commercial opportunities are:
- Prequalified or nationally approved fixed-dose combinations.
- Pediatric dispersible formulations.
- Reliable supply into underserved markets.
- Contract manufacturing for public-health programs.
- Products paired with rifapentine or other newer prevention regimens.
- Regional production supported by government localization policies.
How does isoniazid compare with rifampin and rifapentine?
| Attribute |
Isoniazid |
Rifampin |
Rifapentine |
| Market maturity |
Very mature |
Very mature |
Newer commercial position |
| Standalone patent value |
Minimal |
Minimal for original molecule |
More relevant in certain formulations and regimens |
| Role in active TB |
Core first-line component |
Core first-line component |
More limited, regimen-dependent |
| Role in latent TB |
Established |
Established |
Important in shorter regimens |
| Pricing power |
Low |
Low to moderate |
Higher relative value |
| Resistance concern |
Significant |
Significant |
Significant |
| Commercial differentiation |
Low |
Low to moderate |
Higher |
| Growth potential |
Limited |
Limited to moderate |
Better, depending on access and guidelines |
Rifapentine-based shorter regimens can displace longer isoniazid-only or isoniazid-heavy prevention regimens where affordability, availability, and guideline adoption permit. Isoniazid remains important because of its low cost, established manufacturing base, and role in combination treatment.
What litigation and settlement issues affect isoniazid?
No major current patent-litigation trend is associated with conventional generic isoniazid. Paragraph IV litigation is generally not central to the standalone product because its core patents expired long ago.
Potential disputes may arise around:
- Fixed-dose combination patents.
- Manufacturing-process claims.
- Pediatric formulations.
- Extended-release delivery systems.
- Regulatory exclusivity for newer tuberculosis products.
Settlement agreements, if any, are more likely to concern a branded combination or a newer rifamycin-based regimen than ordinary isoniazid tablets. A company evaluating entry should treat formulation and combination claims separately from the public-domain status of the isoniazid molecule.
What are the main geographic markets?
Demand is concentrated in countries with high tuberculosis incidence and in countries with active latent-infection screening.
High-volume markets include:
- India.
- China.
- Indonesia.
- Pakistan.
- Bangladesh.
- Nigeria.
- South Africa.
- The Philippines.
- Other countries with large national tuberculosis programs.
High-value prevention markets include the United States, Canada, Western Europe, Australia, and selected Middle Eastern markets. These markets have lower patient volumes but stronger regulatory requirements and greater use of screening programs among high-risk populations.
Geographic patent risk is low for standalone isoniazid because core exclusivity has expired globally. Regulatory and procurement requirements remain country-specific.
Key Takeaways
- Isoniazid is a mature generic tuberculosis medicine with no meaningful standalone patent moat.
- Commercial demand is tied to tuberculosis incidence, diagnosis, latent-infection programs, and public procurement.
- Global treatment volume is substantial, but standalone revenue is low and rarely reported separately.
- Generic competition limits pricing power and compresses margins.
- Shorter rifamycin-based preventive regimens create substitution risk.
- Fixed-dose combinations and pediatric formulations offer greater differentiation than standard tablets.
- The largest commercial risks are tender pricing, supply disruption, resistance, and formulation substitution.
- The financial outlook is stable in volume but weak in unit economics, with better opportunities in reliable supply and differentiated combinations.
FAQs
Is isoniazid still commercially important?
Yes. It remains a core component of tuberculosis treatment and an established latent-infection therapy, especially in low- and middle-income countries.
Can a company obtain a new patent on isoniazid?
A new patent could potentially cover a novel formulation, delivery system, manufacturing process, or combination. A patent cannot generally be obtained for the old isoniazid molecule itself.
Is isoniazid a high-margin pharmaceutical product?
No. Conventional isoniazid is a low-margin generic product. Higher margins are more likely in specialized pediatric formulations, fixed-dose combinations, or supply-constrained contracts.
Does isoniazid face biosimilar competition?
No. Isoniazid is a small-molecule chemical drug, not a biologic. It faces generic competition rather than biosimilar competition.
What could increase isoniazid demand?
Higher tuberculosis diagnosis rates, expanded latent-infection screening, increased public-health funding, national stockpiling, and supply disruptions affecting competing products could increase demand.
References
-
Centers for Disease Control and Prevention. (2020). Latent tuberculosis infection: A guide for primary health care providers. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2023). Isoniazid prescribing information. U.S. Department of Health and Human Services.
-
World Health Organization. (2023). Global tuberculosis report 2023. World Health Organization.
-
World Health Organization. (2022). WHO consolidated guidelines on tuberculosis: Module 5, management of tuberculosis in children and adolescents. World Health Organization.