Share This Page
FENOFIBRIC ACID Drug Patent Profile
✉ Email this page to a colleague
Which patents cover Fenofibric Acid, and what generic alternatives are available?
Fenofibric Acid is a drug marketed by Actavis Elizabeth, Alembic, Aurobindo Pharma Ltd, Chartwell Rx, Impax Labs Inc, Macleods Pharms, Micro Labs, Ph Health, Pharmobedient, Rising, Twi Pharms, and Yichang Humanwell. and is included in twelve NDAs.
The generic ingredient in FENOFIBRIC ACID is choline fenofibrate. There is one drug master file entry for this compound. Six suppliers are listed for this compound. Additional details are available on the choline fenofibrate profile page.
AI Deep Research
Questions you can ask:
- What is the 5 year forecast for FENOFIBRIC ACID?
- What are the global sales for FENOFIBRIC ACID?
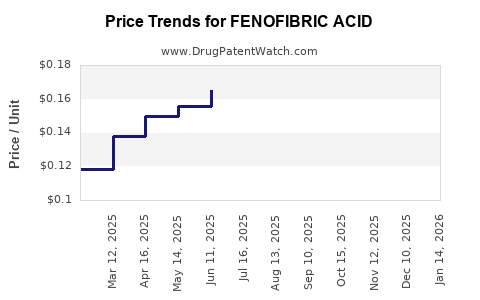
- What is Average Wholesale Price for FENOFIBRIC ACID?
Summary for FENOFIBRIC ACID
| US Patents: | 0 |
| Applicants: | 12 |
| NDAs: | 12 |
| Finished Product Suppliers / Packagers: | 6 |
| Raw Ingredient (Bulk) Api Vendors: | 1 |
| Clinical Trials: | 21 |
| Patent Applications: | 2,873 |
| Drug Prices: | Drug price information for FENOFIBRIC ACID |
| What excipients (inactive ingredients) are in FENOFIBRIC ACID? | FENOFIBRIC ACID excipients list |
| DailyMed Link: | FENOFIBRIC ACID at DailyMed |
US Patents and Regulatory Information for FENOFIBRIC ACID
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | TE | Type | RLD | RS | Patent No. | Patent Expiration | Product | Substance | Delist Req. | Exclusivity Expiration |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Actavis Elizabeth | FENOFIBRIC ACID | choline fenofibrate | CAPSULE, DELAYED RELEASE;ORAL | 200920-001 | Oct 7, 2015 | AB | RX | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Pharmobedient | FENOFIBRIC ACID | choline fenofibrate | CAPSULE, DELAYED RELEASE;ORAL | 200913-002 | Mar 25, 2013 | DISCN | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| Yichang Humanwell | FENOFIBRIC ACID | choline fenofibrate | CAPSULE, DELAYED RELEASE;ORAL | 212562-002 | Dec 23, 2020 | AB | RX | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Chartwell Rx | FENOFIBRIC ACID | choline fenofibrate | CAPSULE, DELAYED RELEASE;ORAL | 200750-001 | Dec 4, 2013 | AB | RX | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >TE | >Type | >RLD | >RS | >Patent No. | >Patent Expiration | >Product | >Substance | >Delist Req. | >Exclusivity Expiration |
Fenofibric Acid Market Dynamics, Patent Expiration, Generic Competition, and Financial Trajectory
Fenofibric acid is a mature fibrate market with limited branded value and substantial generic erosion. The active moiety is marketed primarily as fenofibric acid choline in delayed-release capsules and tablets, including the former branded products Trilipix and Fibricor. U.S. revenue has shifted from branded products to low-cost generic prescriptions, while overall demand remains tied to hypertriglyceridemia, mixed dyslipidemia, and adjunctive lipid management.
No public company reports standalone global revenue for fenofibric acid. The commercial trajectory must therefore be assessed through FDA approvals, generic availability, prescription-volume trends, branded-product disclosures, and the broader fenofibrate class.
What is fenofibric acid and how is it used?
Fenofibric acid is the active metabolite of fenofibrate and a peroxisome proliferator-activated receptor alpha, or PPAR-alpha, agonist. Fenofibric acid choline is used in delayed-release oral products.
U.S. labeling covers treatment of:
- Severe hypertriglyceridemia
- Primary hypercholesterolemia or mixed dyslipidemia
- Dyslipidemia in selected patients receiving statin therapy
Treatment is used with diet and exercise. Fenofibric acid is not a statin and does not occupy the same therapeutic or commercial position as atorvastatin, rosuvastatin, or simvastatin.
Key products and dosage forms
| Product | Active ingredient | Dosage form | Historical sponsor or marketer | Current commercial position |
|---|---|---|---|---|
| Trilipix | Fenofibric acid choline | Delayed-release capsules, 45 mg and 135 mg | Abbott, later AbbVie | Branded product with substantial generic substitution |
| Fibricor | Fenofibric acid | Tablets, 35 mg and 105 mg | Multiple historical sponsors | Genericized product |
| Generic fenofibric acid choline | Fenofibric acid choline | Delayed-release capsules | Multiple ANDA holders | Primary U.S. volume channel |
| Fenofibrate | Fenofibrate | Tablets, capsules, micronized formulations | Multiple manufacturers | Larger and broader competing fibrate market |
Trilipix received FDA approval in 2008 under NDA 022224. The product was approved for lipid disorders and later positioned for use with statins in mixed dyslipidemia. [1]
When did fenofibric acid lose branded exclusivity?
Fenofibric acid lost practical U.S. exclusivity through the expiration and weakening of branded patent protection, followed by approval of abbreviated new drug applications. The commercial loss of exclusivity occurred before the current market period, and generic fenofibric acid products are now available.
The important distinction is between:
- Regulatory exclusivity, such as new chemical entity exclusivity.
- Listed patent protection in the FDA Orange Book.
- Commercial exclusivity, which ends when multiple therapeutically substitutable generics enter.
- Residual branded demand, which can persist after generic launch through prescribing habits, contracts, and reimbursement.
For a mature product such as fenofibric acid, the fourth category is usually small compared with the first three.
Fenofibric acid exclusivity timeline
| Event | Approximate timing | Commercial effect |
|---|---|---|
| Fibricor approval | 2005 | Established fenofibric acid tablet market |
| Trilipix approval | 2008 | Added branded delayed-release capsule product |
| Initial branded market development | 2008-2011 | Abbott promoted Trilipix as a differentiated fibrate option |
| Generic entry and patent erosion | 2010s | Reduced branded pricing power and volume |
| Mature generic market | 2020s | Low-cost supply dominates U.S. prescriptions |
The FDA Orange Book remains the controlling source for current listed patents and exclusivity entries for approved products. Patent status should be evaluated by NDA and dosage form rather than by active ingredient alone. [2]
What patents protect fenofibric acid products?
The historical patent estate focused on fenofibric acid formulations, compositions, salts, dosage forms, and methods of treatment. The strongest commercial claims were directed to the specific delayed-release product architecture rather than to the underlying fibrate pharmacology.
Patent categories relevant to fenofibric acid
Active ingredient and salt patents
Fenofibric acid is closely related to fenofibrate, an older compound. Broad composition-of-matter protection for the fibrate class is no longer commercially relevant in the United States.
Later patents focused on fenofibric acid salts, including fenofibric acid choline, and pharmaceutical compositions containing the active moiety. These claims could delay generic approval if listed and enforceable, but their value declined as the relevant patent terms expired.
Formulation patents
Trilipix used delayed-release capsules. Formulation protection addressed dissolution, release characteristics, dosage strength, and oral delivery of fenofibric acid choline.
Formulation patents can create a narrower barrier than composition-of-matter patents. An ANDA applicant may avoid infringement through a different release mechanism or by filing a Paragraph IV certification against listed patents.
Method-of-use patents
Method claims covered treatment of dyslipidemia, hypertriglyceridemia, mixed dyslipidemia, and certain statin-combination uses. Their commercial value depends on whether the indication is carved out of the generic label and whether physicians prescribe the generic for the patented use.
Skinny-label strategies can reduce method-of-use exposure. They do not necessarily eliminate litigation risk where the generic manufacturer’s marketing, promotional materials, or product labeling supports the patented indication.
How strong is the current fenofibric acid patent estate?
The current patent estate is commercially weak relative to an active branded drug. The reasons are:
- The product is orally administered and chemically simple.
- Fenofibrate and related fibrates have long clinical histories.
- Several manufacturers can supply alternative fibrate products.
- Generic delayed-release versions are available.
- The principal value is in manufacturing scale, regulatory status, and distribution rather than in enforceable exclusivity.
The remaining risk is product-specific. A patent covering a particular release profile, salt, or manufacturing process may still affect one product or one ANDA, but it does not recreate broad market exclusivity for fenofibric acid.
What is the Orange Book status of Trilipix and Fibricor?
The FDA Orange Book lists approved drug products, therapeutic-equivalence evaluations, patents submitted by sponsors, and exclusivity information. Current Orange Book status must be checked against the relevant NDA and the latest FDA publication because listings can change after patent expiration, delisting, administrative corrections, or sponsor submissions. [2]
Trilipix was approved under NDA 022224. Fibricor was approved under a separate NDA and represented an earlier fenofibric acid tablet formulation. Generic approvals are tied to the reference listed drug, dosage form, strength, and labeling.
A generic may be rated therapeutically equivalent only when it meets FDA requirements for pharmaceutical equivalence, bioequivalence, manufacturing quality, and labeling. Orange Book therapeutic-equivalence ratings influence pharmacy substitution and are central to commercial generic uptake. [2]
Which companies are challenging fenofibric acid patents?
The fenofibric acid market is no longer characterized by high-value, active Paragraph IV litigation comparable with major oncology, immunology, or metabolic brands. Generic manufacturers have entered after patent barriers weakened or expired.
Potential ANDA participants have included large generic companies and specialty manufacturers active in lipid-lowering products. The relevant competitive set can change because:
- ANDA approvals may be transferred between owners.
- Products may be approved but not actively marketed.
- Labeling may be discontinued.
- National distribution may be limited by manufacturing capacity or commercial contracts.
The FDA Drugs@FDA database and Orange Book provide the most reliable records for approved generic sponsors and reference products. [2,3]
Paragraph IV risk
Paragraph IV risk was most relevant before generic launch. An ANDA applicant could certify that a listed patent was invalid, unenforceable, or not infringed. That certification could trigger litigation and a potential 30-month stay of approval under the Hatch-Waxman framework. [4]
For fenofibric acid, the economic impact of a Paragraph IV challenge was limited by the relatively small size of the branded market and the availability of other fibrate products. A first-filer could obtain 180-day generic exclusivity in certain circumstances, but that advantage would be temporary and dependent on the applicable statutory conditions.
What generic entry risks exist for fenofibric acid?
Generic entry risk is high because the U.S. market already has multiple low-cost alternatives. The main risk to a branded fenofibric acid product is not a single generic launch. It is cumulative price and volume erosion as additional suppliers enter.
Generic launch scenarios
| Scenario | Likely market effect |
|---|---|
| One generic supplier | Moderate price erosion; some branded retention |
| Two to four suppliers | Rapid pharmacy substitution and lower net prices |
| More than four suppliers | Commodity pricing, contract-driven distribution |
| Supply disruption | Temporary price recovery or allocation advantages |
| Branded relaunch | Limited effect unless supported by a differentiated indication or formulation |
Generic products can erode branded revenue through:
- Automatic pharmacy substitution
- Formulary exclusion
- Lower patient copays
- Wholesaler substitution
- Health-plan step therapy
- Reduced physician attention to brand-specific formulation benefits
How does fenofibric acid compare with fenofibrate?
Fenofibric acid and fenofibrate are closely related but have different formulation and pharmacokinetic profiles. Fenofibric acid is the active metabolite generated from fenofibrate. Both are fibrates, and both compete for treatment in triglyceride-rich dyslipidemia.
| Factor | Fenofibric acid | Fenofibrate |
|---|---|---|
| Drug class | PPAR-alpha agonist | PPAR-alpha agonist |
| Main U.S. use | Hypertriglyceridemia and mixed dyslipidemia | Hypertriglyceridemia and mixed dyslipidemia |
| Product history | Newer fenofibric acid formulations | Older, larger generic class |
| Formulations | Delayed-release capsules and tablets | Multiple tablets, capsules, micronized products |
| Patent strength | Mature and limited | Mature and limited |
| Generic competition | High | Very high |
| Commercial differentiation | Formulation, dosing, and compatibility positioning | Price, availability, and physician familiarity |
Fenofibrate has a broader generic footprint and more dosage-form competition. Fenofibric acid products can retain niche demand where prescribers value a particular strength, delayed-release profile, or statin-combination positioning, but those factors rarely support substantial price premiums.
What is the financial trajectory of fenofibric acid?
The financial trajectory is a transition from branded pharmaceutical revenue to low-margin generic revenue.
Branded period
Trilipix was introduced into a competitive lipid market dominated by statins. Its commercial opportunity depended on treatment of residual triglyceride and mixed-dyslipidemia populations, not on replacing statin therapy.
Abbott reported pharmaceutical sales at the segment level, while public reporting did not consistently disclose standalone Trilipix revenue. After Abbott separated its research-based pharmaceutical operations into AbbVie in 2013, Trilipix was included within broader pharmaceutical reporting rather than presented as a separately material product. [5,6]
Post-exclusivity period
After generic entry, the economic value of the product moved toward:
- Generic manufacturer volume
- API and finished-dose manufacturing
- Wholesale and pharmacy contracts
- Formulation know-how
- Regulatory approvals
- Supply reliability
The originator’s revenue exposure declined because branded prescriptions became less defensible and net pricing fell. Generic suppliers can still generate positive cash flow, but the economics depend on manufacturing cost, supplier concentration, and price discipline.
Revenue exposure assessment
| Revenue source | Current exposure |
|---|---|
| Originator branded sales | Low |
| Generic delayed-release capsules | Moderate volume, low unit price |
| Generic tablets | Low-to-moderate volume, low unit price |
| Active pharmaceutical ingredient | Commodity-oriented |
| Combination products | Limited direct fenofibric acid exposure |
| Licensing royalties | No major publicly disclosed royalty stream identified |
There is no widely reported standalone market size for fenofibric acid. IQVIA prescription data, CMS claims, and company-level product sales would be required to calculate a precise current market value. Public filings do not provide a reliable standalone revenue series for the molecule. [5,7]
What manufacturing and intellectual-property barriers remain?
Manufacturing barriers are more important than patent barriers. Fenofibric acid products require control of:
- Active ingredient purity
- Salt formation
- Particle size and solid-state properties
- Delayed-release coating performance
- Dissolution specifications
- Content uniformity
- Stability through shelf life
- Bioequivalence across strengths
Delayed-release products can impose greater development complexity than immediate-release tablets. A manufacturer may need specialized coating equipment, validated dissolution methods, and experience with scale-up.
These requirements can limit the number of commercially reliable suppliers even when patents no longer block entry. The result is a market with many potential ANDA holders but fewer consistently available products.
What FDA regulatory issues affect fenofibric acid?
Fenofibric acid is regulated as a small-molecule prescription drug. Generic manufacturers use the ANDA pathway and must demonstrate bioequivalence to the relevant reference listed drug. [3]
Key regulatory issues include:
- Correct reference product selection
- Strength-specific bioequivalence
- Delayed-release dissolution
- Labeling alignment
- Renal dosing and contraindications
- Drug interaction warnings
- Liver and muscle safety monitoring
- Manufacturing compliance
- Postapproval changes to suppliers or facilities
Unlike monoclonal antibodies, fenofibric acid has no biosimilar pathway. The relevant competitive mechanism is generic substitution, not interchangeability under the FDA Purple Book.
Does biosimilar risk affect fenofibric acid?
No. Fenofibric acid is a chemically synthesized small molecule, so biosimilar competition does not apply. Competitive risk comes from ANDA-approved generics, therapeutic alternatives, and prescribing substitution within the fibrate class.
The absence of biosimilar exposure does not improve the product’s exclusivity position. Generic competition is typically faster and more direct for small molecules once patents and regulatory exclusivities expire.
What patent litigation affects fenofibric acid?
Historical disputes were likely concentrated around formulation and use patents associated with branded fenofibric acid products. The litigation value of those disputes declined as the relevant patent terms expired and generic products reached the market.
There is no current, broadly material patent case comparable with litigation surrounding major protected drugs. Any active dispute should be evaluated at the NDA, ANDA, patent, and product level rather than inferred from the molecule’s history.
What licensing deals involve fenofibric acid?
No major current licensing transaction has created a significant standalone commercial franchise around fenofibric acid. Historical commercialization involved the originator’s internal development and marketing structure rather than a widely disclosed, high-value external license.
Any remaining commercial arrangements are more likely to involve:
- Generic supply agreements
- Contract manufacturing
- API sourcing
- Regional distribution
- Product transfers between generic companies
These agreements generally do not create durable exclusivity unless they control a scarce manufacturing source or a differentiated formulation.
How does fenofibric acid fit into the competitive lipid market?
Fenofibric acid competes in a mature segment with several lower-cost therapies:
- Fenofibrate
- Gemfibrozil
- High-intensity statins
- Ezetimibe
- Prescription omega-3 products
- Icosapent ethyl
- PCSK9 inhibitors for selected LDL-driven populations
The commercial opportunity is constrained because treatment guidelines prioritize statins for atherosclerotic cardiovascular disease risk reduction. Fibrates retain clinical relevance in patients with severe hypertriglyceridemia or selected mixed-dyslipidemia profiles, but their use is narrower than that of statins.
Key Takeaways
- Fenofibric acid is a mature, genericized fibrate market.
- Trilipix and Fibricor established the principal U.S. branded products.
- Branded revenue declined after generic entry and is not separately reported in current public company filings.
- Patent protection is no longer a meaningful broad-market barrier.
- Formulation, manufacturing quality, supply reliability, and regulatory execution are more important than molecule-level IP.
- Paragraph IV litigation risk is materially lower than during the initial genericization period.
- Biosimilar competition does not apply because fenofibric acid is a small molecule.
- Fenofibrate is the closest major comparator and has broader generic competition.
- Current commercial value is concentrated in generic volume, low-cost manufacturing, and distribution.
- Precise market size and revenue estimates require proprietary prescription or claims data because public filings do not isolate fenofibric acid sales.
FAQs
Is Trilipix still available in the United States?
Generic equivalents of the fenofibric acid choline delayed-release capsule are available. Branded Trilipix availability may vary by distributor, pharmacy, and manufacturer commercialization status.
Does fenofibric acid have composition-of-matter patent protection?
The broad underlying fibrate chemistry is old. Historical protection centered more heavily on salts, formulations, delayed-release delivery, and methods of use than on a currently enforceable broad composition-of-matter monopoly.
Can a generic fenofibric acid product be automatically substituted for Trilipix?
Substitution depends on FDA therapeutic-equivalence ratings, state pharmacy law, product availability, and the exact reference listed drug and dosage form.
Is fenofibric acid safer than fenofibrate?
Fenofibric acid is the active metabolite of fenofibrate, so the products have related pharmacology and safety considerations. Renal function, liver effects, muscle toxicity, and interactions with statins remain relevant to prescribing decisions.
Is fenofibric acid an attractive licensing asset?
As a standalone branded asset, it has limited licensing value because exclusivity has eroded and generic competition is established. Value may remain in a differentiated formulation, regional distribution rights, manufacturing capacity, or a reliable supply platform.
References
- U.S. Food and Drug Administration. (2008). Trilipix prescribing information, NDA 022224.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs.
- U.S. Food and Drug Administration. (2015). Abbreviated new drug application approvals: Paragraph IV certifications and 180-day exclusivity.
- Abbott Laboratories. (2012). Annual report for the fiscal year ended December 31, 2012.
- AbbVie Inc. (2013). Annual report for the fiscal year ended December 31, 2013.
- Centers for Medicare & Medicaid Services. (2024). Medicare Part D prescription drug event data and drug spending dashboards.
More… ↓
