Last updated: October 19, 2026
Cleocin is the legacy brand for clindamycin, an antibiotic marketed in oral, injectable, topical, and vaginal formulations. Its patent and regulatory exclusivity have expired, generic competition is extensive, and Pfizer does not report Cleocin revenue as a separate product line. The commercial trajectory is therefore one of mature, low-growth brand erosion rather than branded pharmaceutical expansion. Current value is concentrated in generic clindamycin volume, institutional supply, topical prescriptions, and certain hospital indications.
What is Cleocin and which formulations are marketed?
Cleocin contains clindamycin, a lincosamide antibiotic derived from lincomycin. It inhibits bacterial protein synthesis by binding to the 50S ribosomal subunit. The product has been used against susceptible gram-positive and anaerobic infections, acne, bacterial vaginosis, and selected dental infections.
| Cleocin formulation |
Active ingredient |
Primary use |
Current commercial position |
| Cleocin HCl capsules |
Clindamycin hydrochloride |
Oral treatment of susceptible bacterial infections |
Generic competition is extensive |
| Cleocin Phosphate injection |
Clindamycin phosphate |
Hospital and injectable treatment |
Generic injectable competition |
| Cleocin T |
Clindamycin phosphate |
Acne and topical bacterial conditions |
Generic topical competition |
| Cleocin vaginal cream |
Clindamycin phosphate |
Bacterial vaginosis |
Generic competition |
| Cleocin ovules |
Clindamycin phosphate |
Bacterial vaginosis |
Limited and formulation-specific competition |
Cleocin is not a single commercial asset. Each dosage form has a separate regulatory and commercial history, although all are exposed to the same core active ingredient and broad generic substitution.
What is the FDA regulatory status of Cleocin?
Cleocin products were approved under legacy new drug applications and are now supported by abbreviated new drug applications for generic versions. FDA labeling identifies serious risks, including Clostridioides difficile-associated diarrhea and colitis. The risk applies to systemic exposure and is a central factor in prescribing decisions.[1]
The FDA-approved uses vary by formulation:
- Oral and injectable clindamycin are indicated for susceptible bacterial infections.
- Topical clindamycin is indicated for acne vulgaris.
- Vaginal clindamycin is indicated for bacterial vaginosis.
- Clindamycin is not appropriate for viral infections.
- Resistance and adverse gastrointestinal effects limit use when safer alternatives are available.
The clinical market has shifted toward targeted prescribing. In dermatology, topical clindamycin is commonly combined with benzoyl peroxide to reduce resistance risk. In bacterial vaginosis, clindamycin competes with metronidazole and newer or alternative local therapies. In systemic infection, it competes with beta-lactams, vancomycin, linezolid, doxycycline, trimethoprim-sulfamethoxazole, and other agents selected according to pathogen, resistance profile, infection site, and patient factors.
What is the Orange Book status of Cleocin?
Cleocin has no meaningful remaining period of branded market exclusivity based on the original clindamycin patents. FDA Orange Book listings for legacy Cleocin products do not create a current commercial barrier comparable to a protected small-molecule product with unexpired composition-of-matter or formulation patents.[2]
The practical status is:
| Exclusivity category |
Cleocin status |
| New chemical entity exclusivity |
Expired |
| Orphan-drug exclusivity |
Not applicable to the core Cleocin portfolio |
| Pediatric exclusivity |
No current material protection |
| Composition-of-matter patent protection |
Expired |
| Formulation patent protection |
No significant current barrier identified |
| Method-of-use protection |
No current barrier that prevents routine generic substitution |
| Authorized generic risk |
High because generic clindamycin is widely available |
| Biosimilar risk |
Not applicable; clindamycin is a small molecule |
Cleocin’s remaining commercial protection is based on brand recognition, prescribing familiarity, supply reliability, and channel preference rather than enforceable exclusivity.
When did Cleocin lose patent exclusivity?
The original clindamycin patent estate is several decades old. Cleocin’s principal commercial products entered the market long before the modern patent-and-exclusivity framework became central to pharmaceutical launch planning. The core exclusivity period ended sufficiently long ago for multiple manufacturers to obtain FDA approval for clindamycin products.
An exact current patent-expiration date is not commercially determinative because the relevant patents have expired and generic products have been approved for many years. FDA-approved generic clindamycin is available across oral, injectable, topical, and vaginal categories, subject to product-specific availability.
No active patent term extension or pediatric extension materially changes the market position of the original Cleocin portfolio.
How many patents protect Cleocin today?
No material active patent estate protects Cleocin as a product franchise. The historic estate likely included patents covering clindamycin chemistry, pharmaceutical compositions, and formulations, but those rights have expired or no longer prevent generic entry.
The absence of a meaningful active estate has several consequences:
- Generic manufacturers can compete on price.
- FDA approval pathways are based on abbreviated new drug applications rather than full clinical development.
- Brand pricing power is limited.
- Formulation-specific switching can occur when generic supply is available.
- Litigation risk is low compared with products that have active Orange Book patents.
The key remaining barriers are regulatory compliance, manufacturing quality, sterile production capability for injectable products, supply-chain reliability, and contracting access. These are operational barriers, not patent barriers.
Are there Paragraph IV challenges to Cleocin?
Paragraph IV litigation is not a major current risk category for Cleocin because the core patents protecting the brand have expired and generic clindamycin products have been marketed for an extended period.
A Paragraph IV certification applies when a generic applicant challenges an Orange Book-listed patent as invalid, unenforceable, or not infringed. Cleocin does not have the current patent profile that typically produces a concentrated wave of Paragraph IV filings, 30-month stays, or first-filer launch economics.[3]
Any future litigation would more likely concern:
- A newly developed clindamycin formulation;
- A device or delivery system;
- A combination product;
- Manufacturing or regulatory matters;
- Trade dress, trademark, or contractual disputes.
Those issues would not restore exclusivity to conventional oral, injectable, topical, or vaginal clindamycin.
What formulations are protected by Cleocin patents?
No conventional Cleocin formulation has a current patent position strong enough to prevent broad generic competition. Product-specific formulation differences can still influence prescribing and substitution:
- Injectable clindamycin requires sterile manufacturing and quality control.
- Vaginal products may differ in cream base, applicator, concentration, and packaging.
- Topical products may differ in vehicle, gel composition, lotion characteristics, and container design.
- Oral products may differ in capsule size, excipients, and packaging.
These differences can create limited commercial niches, but they do not provide durable franchise-level protection. A formulation may receive a separate FDA approval without creating meaningful pricing power if therapeutically equivalent or clinically substitutable generics are available.
How strong is the Cleocin patent estate?
The Cleocin patent estate is commercially weak and legally mature.
| Patent-estate factor |
Assessment |
| Core composition patent |
Expired |
| Generic entry resistance |
Low |
| Orange Book leverage |
Low |
| Formulation differentiation |
Limited |
| Manufacturing complexity |
Moderate for injectable products |
| Regulatory switching risk |
Low to moderate |
| Litigation exposure |
Low |
| Brand pricing power |
Low |
| Lifecycle-management potential |
Limited |
The strongest residual defense is not intellectual property. It is execution in regulated manufacturing and distribution. An injectable clindamycin supplier with a reliable FDA-compliant facility may retain share during shortages or contract renewals, but that advantage can be lost if competing capacity returns.
What is the Cleocin market size and revenue exposure?
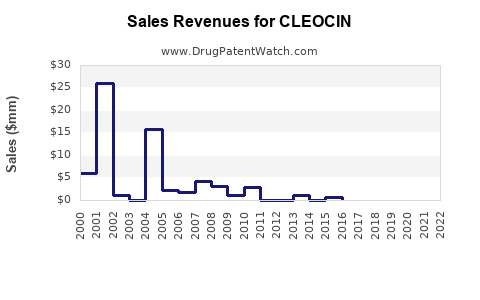
Pfizer does not publicly disclose Cleocin revenue as a standalone product. The product is not separately identified as a major growth driver in Pfizer’s reported product sales, and company reporting groups mature products into broader categories.[4]
This prevents a defensible calculation of current Cleocin brand revenue from public filings. The financial profile can still be characterized:
- Brand revenue is likely immaterial relative to Pfizer’s innovative medicines portfolio.
- Generic clindamycin captures most unit volume.
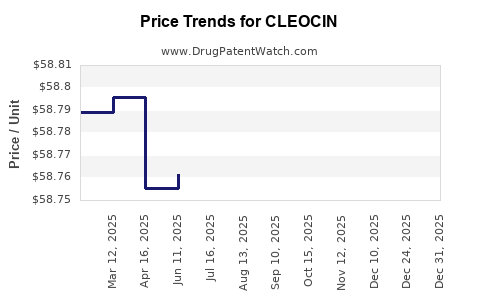
- Net pricing is constrained by pharmacy benefit managers, hospital purchasing groups, and generic competition.
- Injectable demand is more dependent on hospital formularies and supply conditions than on consumer brand preference.
- Topical and vaginal products are exposed to substitution, formulary controls, and lower-cost alternatives.
- Any remaining brand revenue is likely supported by legacy prescriptions, institutional contracts, and prescriber familiarity.
For investors, Cleocin should be modeled as a mature or declining tail product unless a specific product-level dataset demonstrates otherwise. It should not be treated as a material driver of Pfizer’s forward revenue growth.
What are the main market dynamics affecting Cleocin?
Generic erosion and price compression
Clindamycin has multiple generic suppliers. Competition is strongest in conventional oral and topical forms, where manufacturing is comparatively accessible and therapeutic substitution is routine. Pricing depends heavily on wholesaler contracts, retail-channel inventory, and the number of active suppliers.
Clinical safety pressure
Clindamycin has a well-established association with C. difficile infection. FDA labeling warns that antibiotic-associated colitis can range from mild diarrhea to fatal colitis.[1] This safety profile reduces use when alternatives are available, especially for routine infections.
Antimicrobial resistance
Resistance among relevant pathogens reduces the addressable market. Topical antibiotic stewardship has also limited long-term monotherapy use in acne. Dermatology guidelines commonly support combination approaches to reduce resistance development.[5]
Hospital procurement
Injectable clindamycin demand is influenced by hospital formularies, group purchasing organizations, shortages, and availability of alternative agents. A hospital may retain clindamycin for selected anaerobic or toxin-suppression uses while reducing routine use because of safety and resistance concerns.
Shortage-driven volatility
Generic sterile injectables can experience temporary supply disruptions. When competing products are unavailable, a legacy brand or alternate generic supplier can see short-term volume gains. These gains are usually episodic and do not represent durable market expansion.
How does Cleocin compare with competing antibiotics?
| Product or class |
Key competitive advantage |
Limitation relative to clindamycin |
| Metronidazole |
Strong anaerobic and bacterial-vaginosis use; low cost |
Different spectrum and tolerability profile |
| Vancomycin |
Broad institutional use for serious gram-positive infections |
IV administration and monitoring burden; oral use has different indications |
| Linezolid |
Activity against resistant gram-positive organisms |
Higher cost and safety concerns with prolonged treatment |
| Doxycycline |
Broad outpatient use and low cost |
Not interchangeable for all anaerobic or streptococcal indications |
| Trimethoprim-sulfamethoxazole |
Common outpatient generic option |
Limited streptococcal and anaerobic coverage |
| Beta-lactams |
Broad prescribing base and established guidelines |
Allergy, resistance, and spectrum limitations |
| Dalbavancin and other long-acting agents |
Convenient dosing in selected infections |
High cost and narrower commercial use |
Cleocin retains clinical relevance where tissue penetration, anaerobic coverage, oral availability, or toxin-suppression considerations support its use. It lacks a broad commercial advantage over lower-cost generic alternatives.
What patent litigation, licensing, or settlement agreements affect Cleocin?
No major current patent litigation or settlement structure is central to the conventional Cleocin franchise. The product’s patent life predates the current wave of high-value generic litigation involving protected blockbuster drugs.
No material recent licensing transaction is required to commercialize standard clindamycin products. Generic manufacturers generally rely on their own FDA approvals and manufacturing networks. Commercial agreements are more likely to involve distribution, hospital contracting, private-label supply, or authorized-generic arrangements than patent settlements.
Trademark rights in the Cleocin name may remain distinct from patent rights. Trademark protection can restrict confusingly similar branding, but it does not prevent generic manufacturers from selling clindamycin under their own names.
What generic launch scenarios exist for Cleocin?
Base case: continued mature-market decline
Generic suppliers retain most volume, brand demand declines gradually, and pricing remains under pressure. This is the most likely long-term scenario.
Upside case: temporary injectable shortage
Manufacturing disruption among generic suppliers increases demand for available Cleocin or alternate clindamycin inventory. Revenue improves temporarily but normalizes when supply is restored.
Downside case: accelerated clinical substitution
Greater concern over C. difficile infection, resistance, or stewardship restrictions shifts prescribing toward other antibiotics. Topical and systemic volume declines faster than the broader antibiotic market.
Limited lifecycle-management case
A differentiated vehicle, delivery system, combination product, or hospital-specific presentation could create a niche. Such a product would require new regulatory and commercial investment and would not revive the legacy Cleocin franchise by itself.
What is the geographic coverage of Cleocin?
Clindamycin generics are available across major pharmaceutical markets, subject to local approvals, supply conditions, and national reimbursement policies. The commercial importance of the Cleocin brand varies by country because:
- Some markets emphasize international nonproprietary-name prescribing.
- Some countries permit broad substitution.
- Hospital procurement can favor local suppliers or tender winners.
- Brand recognition is more valuable in markets with limited generic substitution.
- Regulatory approvals differ by dosage form and manufacturer.
The United States remains the most relevant market for Orange Book, generic substitution, and hospital purchasing analysis. Europe and other regulated markets generally provide limited opportunity for legacy-brand price expansion.
Key Takeaways
- Cleocin is the legacy clindamycin brand, with oral, injectable, topical, and vaginal products.
- Core patent and exclusivity rights have expired.
- Generic clindamycin is widely available, making patent-based market protection negligible.
- No current Paragraph IV campaign materially threatens the conventional Cleocin portfolio.
- Pfizer does not report Cleocin revenue separately, preventing a reliable standalone revenue estimate from public filings.
- The financial trajectory is mature to declining, with limited brand pricing power.
- Injectable supply disruptions can create short-term revenue volatility.
- C. difficile risk, antimicrobial resistance, and stewardship policies constrain demand.
- Biosimilar risk is irrelevant because clindamycin is a small-molecule antibiotic.
- The principal remaining competitive barriers are manufacturing quality, sterile capacity, supply reliability, and contracting access.
FAQs About Cleocin Patents, Revenue, and Market Competition
Is Cleocin still under patent protection?
No material patent protection remains for the conventional Cleocin clindamycin products. Generic manufacturers have marketed competing products for many years.
Does Pfizer still make Cleocin?
Pfizer has historically held and marketed Cleocin products, but current availability and manufacturer status vary by formulation and market. Many clindamycin products are supplied by generic manufacturers.
Is Cleocin the same as clindamycin?
Yes. Cleocin is a brand name, while clindamycin is the active pharmaceutical ingredient. Generic clindamycin products may differ in manufacturer, excipients, packaging, and price.
Can a generic launch reduce Cleocin sales immediately?
Yes. Because patent protection has expired and generic alternatives are established, pharmacy substitution, formulary exclusion, and hospital contracting can shift volume away from the brand quickly.
Does Cleocin have biosimilar competition?
No. Biosimilars apply to biologic medicines. Clindamycin is a chemically synthesized small molecule and competes with conventional generic drugs.
References
- U.S. Food and Drug Administration. (2023). Cleocin phosphate injection: Prescribing information. DailyMed.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. Center for Drug Evaluation and Research.
- U.S. Food and Drug Administration. (2024). Hatch-Waxman Amendments and abbreviated new drug applications. Center for Drug Evaluation and Research.
- Pfizer Inc. (2024). 2023 annual report.
- American Academy of Dermatology. (2016). Guidelines of care for the management of acne vulgaris. Journal of the American Academy of Dermatology, 74(5), 945-973.