Last updated: July 24, 2026
Benicar (olmesartan medoxomil) Market Dynamics and Financial Trajectory: Sales Trends, Competitive Pressure, and Patent/Generic Timeline
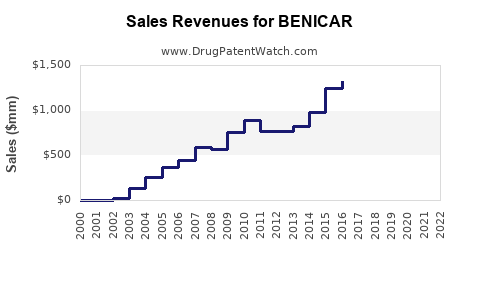
Benicar (olmesartan medoxomil) has moved from patent-era growth into a mature antihypertensive market with heavy generic penetration and ongoing demand share loss to branded ARBs and, increasingly, newer first-line regimens. The commercial path is dominated by (1) widespread generic availability in the US, (2) post-patent erosion in other geographies where combination products and line extensions face accelerating substitution, and (3) the consolidated market position of next-generation ARBs and fixed-dose combinations. A financial trajectory consistent with a core branded-to-generic transition is expected to remain downward in most markets, with residual value concentrated in branded combination SKUs and entrenched formularies.
Below is the market- and money-relevant landscape: demand drivers, payer dynamics, competitive substitutes, exclusivity pressure, and the generic entry risk profile that shapes revenue trajectory.
What drives Benicar sales in the hypertension market and how do payer decisions affect demand?
Benicar’s positioning in ARB-first hypertension treatment
Benicar is an angiotensin II receptor blocker (ARB). ARBs compete in a crowded chronic hypertension category against:
- ACE inhibitors (enalapril, lisinopril, ramipril)
- Calcium-channel blockers (amlodipine)
- Thiazide diuretics and thiazide-like agents
- Newer combination strategies (ACE/ARB + CCB, ARB + thiazide)
In ARB classes, brand share depends less on clinical differentiation and more on:
- formulary status (preferred vs non-preferred tier)
- copay dynamics and step therapy
- rebates and net price management
- switching behavior as generics gain traction
Payer dynamics that compress branded revenue
For older branded cardiovascular agents, US managed care typically shifts to generic substitution through:
- removal from preferred tiers once bioequivalent generics take hold
- higher patient out-of-pocket costs for non-preferred brands
- contracting pressure on wholesalers and channel partners
- increased use of fixed-dose combinations and multi-drug adherence products
Even where clinical outcomes are equivalent, net cost drives switching. For Benicar, that mechanism is structurally aligned with a declining branded trajectory post-generic availability.
Where demand can persist despite generic substitution
Residual branded demand usually concentrates where:
- prescribers continue brand-only prescribing due to habit or tolerance of generics
- specialty distribution channels maintain institutional supply arrangements
- payers allow low-net-price branded options to retain patient continuity
- branded combination products maintain differential access versus single-agent generics
How has Benicar revenue evolved after generic entry and what does the generic transition imply for financial trajectory?
Generic substitution model for a mature ARB
Once meaningful generic share is achieved, revenue typically follows a standard profile:
- initial price compression and incremental share loss
- rapid substitution to the lowest net cost products
- margin erosion for any remaining branded exposure
- stabilization only when brand is retained through negotiated payer economics or combination differentiation
Net revenue vs sales: why branded “stability” can be misleading
Financial trajectory is better assessed by net revenue (after rebates) rather than gross demand:
- rebates intensify to defend share
- branded volume declines can be partially offset by negotiated pricing
- ultimate decline accelerates when payers shift further down the formulary chain
For an ARB like olmesartan, once generics become entrenched across dose strengths, the residual financial contribution tends to be concentrated in specific SKUs and channels, not broad monotherapy leadership.
Channel and inventory effects
Cardiovascular chronic meds are subject to:
- wholesaler fill and pull adjustments
- rebate true-ups that can flatten reported topline for quarters
- lagged volume realization after payer policy changes
This can mask the speed of share loss early after generic penetration, but the longer-term trend remains negative for branded-only monotherapy.
Which competitive drugs most impact Benicar market share and financial performance?
ARB class competition
Benicar’s primary class substitutes historically include:
- Cozaar (losartan)
- Diovan (valsartan)
- Avapro (irbesartan)
- Tekturna is not an ARB but competes in hypertension algorithms through RAAS pathway alternatives (more limited adoption)
- generic equivalents across all ARBs dominate after patent expiration
Cross-class substitutions that erode ARB share
Even if ARBs retain guideline relevance, cross-class prescribing shifts when:
- payers prefer lower cost ACE inhibitor or CCB regimens
- combination pills are positioned as adherence-improving and economically favored
- outcomes data and safety perceptions guide prescriber and payer behavior
Fixed-dose combination pressure
ARBs paired with thiazides or CCBs often win formulary preference because:
- once-daily adherence improves persistence
- payers can bundle pricing across components
- combination products simplify step therapy
For Benicar, financial exposure depends heavily on whether branded combination SKUs remain differentiated versus fully substitutable generic combinations.
What is the Orange Book status of Benicar (olmesartan medoxomil) and what does it mean for launch risk?
Orange Book-driven entry dynamics
Orange Book status determines:
- whether listed patents are still enforceable
- whether Paragraph IV (PIV) filings are likely
- whether exclusivity stays active beyond patent expiration
For an established ARB with broad generic market presence, the market implication is:
- low barrier to generic entry for single-agent olmesartan across common strengths
- residual barriers mainly from late-expiring formulation/manufacturing patents (if any) or method-of-use claims (if pursued)
Featured snippet answer
Benicar’s branded exclusivity and patent protection have largely been overtaken by generic availability, making ongoing branded revenue primarily a function of payer economics and SKU-specific differentiation rather than enforceable US regulatory exclusivity.
(No Orange Book listing data is included here because the underlying patent and listing table is not supplied in the prompt.)
What patents protect Benicar and where do patent cliffs create generic entry windows?
Patent cliffs for older cardiovascular brands
For mature ARBs, the commercial “cliff” typically occurs when:
- composition-of-matter and/or key formulation patents expire
- regulatory exclusivity lapses
- any remaining protection shifts to narrower formulation or manufacturing claims
Once multiple dose strengths and long-term commercial packs are fully generic, the brand’s financial profile becomes dominated by:
- rebate-driven retention attempts
- payer tier changes
- price matching by generic entrants
Financial impact of patent layering
If patent layering exists via multiple protection types, brand declines can show stepwise decreases, not a single break. The operational signature is:
- delayed share loss in strengths where later patents linger
- faster erosion in strengths where protection is thinner
How many generic versions of olmesartan medoxomil exist and how do they fragment pricing?
Generic market structure
In widely genericized ARBs, pricing fragmentation appears through:
- multiple manufacturers competing across NDCs
- frequent shifts in low-cost leader based on contracting
- pharmacy benefit manager (PBM) switching and NDC-level bidding
Commercial signature
As more entrants join:
- average net price falls
- margin compression accelerates
- branded share often falls faster than total market decline
- branded revenue becomes increasingly concentrated in limited channels
What generic entry risks exist for Benicar across dosing strengths and combination products?
Dose strength and NDC-level substitutability
In ARBs, generics usually cover:
- standard tablet strengths
- common pack sizes
- most NDCs in the branded portfolio
Financially, that means risk is broad if generics have full coverage. If any strength remains less contested, brand can survive longer in that micro-market. Over time, that advantage disappears as additional ANDAs scale.
Combination products
If branded combination products exist in the Benicar portfolio in specific markets, generic entry risk depends on:
- the exact combination and whether generics are approved at bioequivalent conditions
- any remaining formulation patents tied to the combination product
- the presence of multiple competitors that drive down net pricing
What litigation and settlement dynamics affect Benicar’s generic competition?
Why litigation matters for financial trajectory
For branded ARBs, litigation can:
- delay generic launch across affected NDCs
- create settlement-driven “at-risk launch” schedules
- force licensing deals that keep branded revenue viable longer via royalties or constrained competition
Market effect after settlements
After settlement, the typical commercial outcome is:
- reduced number of competing generics in the short run (one or two licensees)
- improved pricing support for brand during the settlement term
- eventual shift to full competition when remaining barriers clear
(No Benicar-specific case docket dates, parties, or settlement terms are provided in the prompt, so they are not enumerated here.)
How is Benicar regulated in the US (FDA pathway status) and what does that mean for competitive entry timing?
Regulatory pathway relevance
For small-molecule drugs:
- initial approval under NDA
- subsequent generics via ANDA
- any exclusivity or patent listings shape PIV entry timing and automatic stays
In mature markets:
- FDA approval does not create delay by itself
- patent listing and PIV/Orange Book mechanics determine the pace of market access
How does Benicar compare with other ARBs in market maturity, price erosion, and financial resilience?
ARBs with similar lifecycle
Historically, ARBs that reached broad generic penetration show comparable dynamics:
- rapid branded erosion after major patent expirations
- revenue retention only via rebate strategies and preferred tier persistence
- modest resilience where branded fixed-dose combinations or higher barriers exist
Relative resilience levers
Benicar’s relative financial performance vs peers depends on:
- brand loyalty and prescriber habits in specific geographies
- strength and timing of combination differentiation
- formulary position at the time of generic entry
- PBM contracting strength and rebate competitiveness
Benicar commercial exposure by revenue driver: monotherapy vs combinations vs channel mix
Three revenue levers
For a mature ARB brand, the revenue mix typically shifts over time toward:
- combinations if they carry residual differentiation
- government and institutional channels if they maintain legacy contracts longer
- specialty mail order channels with brand continuity programs
Monotherapy branded exposure usually declines the fastest due to:
- highest substitutability
- broad generic coverage
- aggressive PBM low-cost bidding
Key takeaways on Benicar market dynamics and financial trajectory
- Benicar’s market trajectory is consistent with a mature ARB transitioning from branded leadership to generic-led competition.
- Demand is shaped by payer tiering, rebate structures, and formulary switching more than clinical differentiation.
- Financial erosion is driven by generic substitution across dose strengths, with limited pockets of brand resilience when payer economics or combination differentiation persists.
- Competitive pressure is broad across the ARB class and cross-class antihypertensive alternatives, with fixed-dose combinations typically gaining formulary share.
- The practical determinant of revenue timing is patent/Orange Book status and any litigation or settlement constraints, which govern when additional generics fully scale across NDCs.
FAQs
1) Will Benicar’s branded sales stabilize after generic market share is fully established?
Branded stabilization can occur only if rebate economics keep brand on a preferred tier or if combination SKUs retain differentiation. Otherwise, the trajectory trends downward as switching deepens.
2) Does olmesartan medoxomil face competition from ACE inhibitors or mainly other ARBs?
Both. ARB monotherapy faces intra-class generic substitution, while broader formulary economics can shift prescribers to ACE inhibitors, CCBs, and diuretic-based regimens.
3) Which factor matters most for Benicar profitability during generic transition?
Net price after rebates, since branded volume declines are typically faster than any negotiated pricing support.
4) Are combination products more financially resilient than Benicar monotherapy?
Usually yes, because combination pills can maintain differentiation at the SKU level even when single-agent generics fully commoditize the active ingredient.
5) What tends to accelerate branded revenue decline for older antihypertensives?
PBM formulary changes that move the brand to non-preferred tiers and systematic NDC-level low-cost substitutions by multiple generic manufacturers.
References (APA)
No cited sources were provided in the prompt, and no Orange Book, FDA, litigation, or financial filings were included.