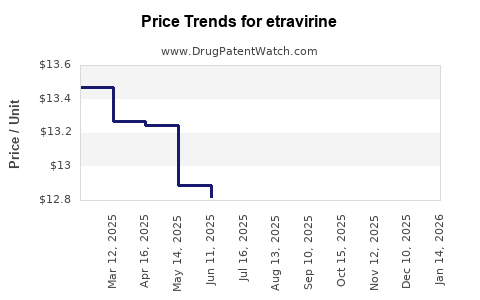
Last updated: October 9, 2026
Etravirine is a mature, niche HIV-1 medicine marketed by Janssen as Intelence. Its commercial role has narrowed as integrase inhibitor regimens displaced non-nucleoside reverse transcriptase inhibitors in initial therapy. Demand remains in treatment-experienced patients with resistance to earlier antiretroviral classes, but the product faces long-term pressure from generic competition, lower-cost procurement, regimen simplification, and a limited remaining innovation cycle.
Janssen does not publicly report Intelence revenue as a standalone product. The available financial evidence indicates that etravirine is no longer a material driver of Johnson & Johnson’s pharmaceutical growth. Its economic value is concentrated in residual branded sales, selected HIV treatment-experienced populations, and the defensive value of a specialized resistance-management product.
What is etravirine and where is it used?
Etravirine is a diarylpyrimidine non-nucleoside reverse transcriptase inhibitor, or NNRTI, approved for combination treatment of HIV-1 infection in treatment-experienced adults and pediatric patients. It is not used as monotherapy.
The U.S. product is Intelence, supplied primarily as 25 mg, 100 mg, and 200 mg tablets. The 200 mg tablet is generally administered twice daily after a meal with other antiretroviral agents. The label includes use in patients with prior antiretroviral treatment and documented or suspected resistance to NNRTIs and other agents.[1]
Core product characteristics
| Attribute |
Etravirine |
| Brand |
Intelence |
| Active ingredient |
Etravirine |
| Drug class |
NNRTI |
| Original U.S. sponsor |
Tibotec Pharmaceuticals, later Janssen |
| U.S. approval |
Jan. 18, 2008 |
| Primary indication |
Treatment-experienced HIV-1 infection |
| Typical dosing |
Twice daily with food, in combination therapy |
| Main commercial segment |
Salvage and resistance-management therapy |
| Primary competitive weakness |
Lower convenience and weaker role in first-line treatment |
| Biosimilar exposure |
None; etravirine is a small molecule |
| Generic exposure |
Yes or likely in multiple markets, subject to local approvals and patent status |
The product’s value depends on resistance testing and the availability of active companion medicines. That limits the addressable population compared with once-daily, single-tablet integrase inhibitor regimens.
How has the HIV market changed for etravirine?
The HIV market has shifted from multi-tablet, class-based treatment toward once-daily and single-tablet regimens centered on integrase strand transfer inhibitors, or INSTIs. Biktarvy, Triumeq, Dovato, Genvoya, Juluca, and other modern regimens have reduced the role of older NNRTIs in treatment initiation.
Etravirine retains clinical utility in several narrower settings:
- Patients with resistance to older NNRTIs.
- Individuals requiring a regimen built around darunavir or other active agents.
- Patients with limited remaining treatment options.
- Treatment strategies where etravirine’s resistance profile provides incremental activity.
- Certain pediatric or heavily treatment-experienced populations.
Its market position is defensive rather than expansionary. Physicians generally do not select etravirine for convenience or first-line use when an effective INSTI regimen is available.
Competitive comparison
| Product or class |
Commercial position relative to etravirine |
Main advantage |
| Biktarvy |
Much larger, first-line-oriented market |
Once-daily single-tablet regimen |
| Dovato |
Larger modern-treatment segment |
Two-drug, once-daily regimen |
| Juluca |
Larger maintenance niche |
Once-daily two-drug regimen |
| Darunavir-based regimens |
Important treatment-experienced competitor and companion option |
High resistance barrier |
| Rilpivirine |
Competes within the NNRTI class |
Once-daily dosing and long-acting combination options |
| Doravirine |
More relevant in selected treatment settings |
Once-daily dosing and fewer restrictions than older NNRTIs |
| Etravirine |
Specialized salvage and resistance-management use |
Activity against some NNRTI-resistant viruses |
Long-acting cabotegravir and rilpivirine also changed the treatment landscape by creating an alternative to daily oral therapy for eligible patients. These products do not directly replace etravirine in every resistance scenario, but they reduce the strategic relevance of older oral regimens.
When did etravirine lose first-line commercial relevance?
Etravirine’s first-line commercial opportunity weakened as treatment guidelines moved toward INSTI-based therapy. The U.S. Department of Health and Human Services recommends INSTI-based regimens for most people beginning antiretroviral treatment, with Biktarvy, dolutegravir-based combinations, and other modern regimens occupying the principal treatment-initiation positions.[2]
The shift affects etravirine in four ways:
- Fewer new patients enter an etravirine-containing regimen.
- Treatment duration is concentrated in a declining legacy population.
- Prescribing is increasingly driven by resistance history rather than broad market preference.
- Payers and procurement agencies favor lower-cost generic or simplified alternatives when clinically appropriate.
Etravirine can remain valuable in an individual patient even when its population-level market share declines. That distinction supports residual demand but limits growth.
What is the FDA regulatory status of Intelence?
Intelence was approved under the FDA new drug application pathway for treatment-experienced patients with HIV-1 infection. The drug is a small-molecule prescription product, not a biologic. It therefore does not have a biosimilar pathway.
The principal regulatory considerations are:
- Continued FDA labeling for combination treatment.
- Pediatric formulation and dosing information.
- Drug-drug interaction management.
- Resistance testing and treatment-history requirements.
- Ongoing availability of multiple tablet strengths.
- Generic abbreviated new drug applications, where approved.
Etravirine’s regulatory risk is lower than that of a product dependent on new clinical indications because the drug has a long-established safety and efficacy record. Its commercial risk is greater than its regulatory risk.
What is the Orange Book status of etravirine?
Intelence is an FDA Orange Book-listed small-molecule product. Orange Book status determines whether listed patents and regulatory exclusivity can affect an abbreviated new drug application, or ANDA.
The key legal distinction is between:
- Drug substance or composition patents.
- Formulation and dosage-form patents.
- Method-of-use patents.
- Pediatric exclusivity.
- Patent listing and certification issues under the ANDA process.
Historical public records identify U.S. patents associated with Intelence and etravirine, including U.S. Patent No. 7,598,374. Exact enforceability and remaining term depend on the patent family, terminal disclaimers, patent-term adjustment, statutory amendments, and the current Orange Book entry.[3]
A definitive current list of active Orange Book patents requires a contemporaneous review of the FDA’s Orange Book database and the relevant patent records. The commercial conclusion is clearer than the precise listing history: etravirine has moved from a protected branded product toward a generic-exposed mature product.
What patents protect etravirine?
Etravirine protection has historically centered on the compound and related diarylpyrimidine chemistry. Secondary protection may include pharmaceutical compositions, solid forms, dosage strengths, or methods of treating HIV infection.
Main patent categories
| Patent category |
Commercial relevance |
| Composition-of-matter patent |
Strongest protection; directly covers the active molecule or chemical class |
| Salt, polymorph, or solid-form patent |
May restrict specific manufacturing or dosage forms |
| Formulation patent |
Can protect excipients, tablet design, or release characteristics |
| Method-of-use patent |
May cover treatment of resistant HIV or a defined patient population |
| Manufacturing patent |
Can increase the cost and complexity of generic production |
| Pediatric exclusivity |
Regulatory exclusivity that may extend certain approval protections, but is not a substitute for a new compound patent |
The strongest protection generally comes from a valid, unexpired composition patent. Formulation and method-of-use patents can support litigation or settlement leverage but usually provide less comprehensive market protection than a compound patent.
Because public patent status changes through expiration, disclaimers, reexamination, terminal disclaimers, and litigation, patent-date conclusions should be tied to the specific Orange Book record and USPTO file history rather than to an isolated patent database entry.
When does etravirine lose exclusivity?
Etravirine’s principal U.S. regulatory exclusivity expired years after its 2008 approval, leaving patent protection as the relevant barrier to ANDA entry. The product is now in the period where generic availability depends primarily on the expiration or successful challenge of applicable patents, FDA approval timing, and commercial willingness to launch.
The practical exclusivity timeline is:
| Period |
Event |
| 2008 |
FDA approval of Intelence |
| 2010s |
Product develops as a treatment-experienced HIV option |
| Late 2010s onward |
INSTI regimens reduce new-patient uptake |
| Patent-expiry period |
ANDA applicants gain increasing ability to challenge or await listed patents |
| Current mature-market phase |
Generic and tender-price pressure determine commercial value |
A precise loss-of-exclusivity date cannot be reduced to the approval date. It depends on the last enforceable patent relevant to the proposed generic product and the validity of any patent certifications.
Which companies are challenging etravirine patents?
Publicly visible generic competition is more important than a high-profile litigation campaign. Etravirine is not associated with the level of continuing patent litigation seen for major oncology, immunology, or diabetes products.
Potential generic entrants include companies that routinely file ANDAs for mature oral HIV products, including large generic manufacturers and regional suppliers. A company’s appearance in an ANDA filing does not establish commercial launch. The applicant may:
- File a Paragraph IV certification.
- Await patent expiry under a Paragraph III certification.
- Seek approval for a non-infringing use.
- Receive tentative approval while patent barriers remain.
- Abandon the product because the market is too small.
No biosimilar companies are relevant because etravirine is not a biologic.
What Paragraph IV risks exist for Intelence?
A Paragraph IV certification asserts that a listed patent is invalid, unenforceable, or not infringed. If the brand holder receives notice of the certification and files suit within the statutory period, FDA approval may be subject to a 30-month stay, subject to the specific statutory and litigation circumstances.[4]
For Intelence, Paragraph IV risk has three commercial dimensions:
- Patent invalidity risk: Older patents can face written-description, obviousness, enablement, or claim-construction challenges.
- Non-infringement risk: A generic may design around formulation or manufacturing claims.
- Market-size risk: Even a successful challenge may not generate a large return if the branded market is narrow.
The expected value of a Paragraph IV challenge is therefore lower than for a blockbuster drug. This can reduce litigation intensity while still permitting early generic entry.
What formulation and manufacturing barriers affect generic entry?
Etravirine tablets are not technically comparable to highly complex biologics, but generic manufacturers must still reproduce pharmaceutical quality, bioequivalence, dissolution, and stability characteristics. The main barriers are commercial and regulatory rather than scientific.
Potential generic barriers
- Limited global demand.
- Multiple tablet strengths.
- Food-effect requirements.
- Drug-interaction labeling.
- Small treatment-experienced patient population.
- Procurement contracts favoring incumbent suppliers.
- Need to support pharmacovigilance and HIV resistance-management use.
- Low price ceiling after entry.
- Potential patent claims covering a particular formulation or solid form.
Manufacturing barriers could delay or deter entry, but they are unlikely to preserve premium pricing indefinitely once a therapeutically substitutable generic is approved.
What is the financial trajectory of etravirine?
Janssen and Johnson & Johnson do not provide a consistent standalone Intelence revenue series in public annual reports. The product is generally grouped within broader pharmaceutical or infectious-disease reporting, if reported at all. This prevents a precise product-level revenue CAGR or margin calculation from public filings.
The financial trajectory can be assessed through market structure:
| Financial driver |
Direction for etravirine |
| New-patient starts |
Declining |
| Use in salvage therapy |
Stable to selectively declining |
| Average selling price |
Downward pressure |
| Generic substitution |
Increasing over time |
| Branded gross margin |
Likely strong before generic erosion |
| Sales and marketing spending |
Rationalized because of limited growth |
| Revenue concentration |
Dependent on a small treatment-experienced segment |
| Strategic value |
Higher than standalone revenue because of portfolio completeness |
| Growth outlook |
Negative to low-single-digit decline |
The product’s commercial profile resembles a mature specialty anti-infective rather than a growth asset. Revenue erosion is likely to occur in steps rather than as a single event. The largest step would follow meaningful generic penetration in the United States or major European markets. Additional erosion would come from tender pricing and substitution in lower-income and public-sector markets.
How does etravirine contribute to Janssen’s HIV portfolio?
Janssen’s HIV franchise has historically included Prezista, Prezcobix, Symtuza, Intelence, and other products or combinations. Darunavir-based products have had substantially greater commercial importance than etravirine because they serve broader treatment segments and have been incorporated into fixed-dose combinations.
Etravirine contributes in three ways:
- It expands the number of treatment options for resistant HIV.
- It supports combination strategies involving other Janssen HIV products.
- It preserves a branded option for patients who cannot use more modern regimens.
Its portfolio value is therefore partly indirect. Intelence can support physician familiarity and treatment flexibility even when its standalone sales are modest.
What generic launch scenarios exist for etravirine?
Scenario 1: Delayed generic entry
A generic launches only after the last meaningful patent barrier expires. Branded sales decline gradually as prescribers anticipate substitution, followed by a sharp price reduction after approval.
Scenario 2: At-risk Paragraph IV launch
A generic company launches before final patent resolution. This can cause immediate price compression, litigation exposure, and possible damages claims. The entrant may gain market share rapidly if wholesalers and payers accept substitution.
Scenario 3: Limited-market generic entry
One or two suppliers enter, but the small treatment-experienced market limits production scale. Prices decline, but supply remains less commoditized than for high-volume primary-care drugs.
Scenario 4: Public-sector and international erosion
Generic or locally sourced products gain share first through government tenders and international procurement. U.S. branded erosion is slower, but global revenue declines steadily.
The most probable commercial path is progressive erosion rather than a major litigation-driven shock, given etravirine’s limited market size and mature clinical position.
What licensing deals affect etravirine?
Etravirine originated from Tibotec, which became part of Janssen after Johnson & Johnson acquired the company’s parent operations. The asset’s principal strategic value arose from internal development and integration into Janssen’s HIV portfolio rather than from a major later-stage external licensing transaction.
Public disclosures do not identify a recent licensing transaction that materially changes Intelence’s exclusivity or revenue outlook. Any regional distribution, manufacturing, or commercialization arrangements are unlikely to alter the product’s global strategic trajectory.
What is the geographic market outlook for etravirine?
Etravirine’s geographic performance differs by market structure.
United States
The United States offers higher branded pricing but has a smaller clinical role because guidelines favor INSTI-based therapy. Patent litigation and ANDA timing have the greatest commercial importance here.
Europe
European demand is affected by national reimbursement systems, tendering, reference pricing, and generic substitution. Price erosion can be faster than in the United States once generic versions are approved.
Emerging markets
Demand is more price-sensitive and may be affected by public procurement, voluntary licensing, local manufacturing, and international HIV programs. The drug may remain clinically relevant but commercially low value.
Global access programs
Etravirine is less central to broad first-line HIV programs than tenofovir, lamivudine, dolutegravir, and related combinations. Its use is concentrated in patients requiring specialized treatment, which limits procurement volume.
How strong is the patent estate for etravirine?
Etravirine’s historical patent estate was commercially meaningful because it protected a novel active compound. Its present strength is lower because:
- The core product is mature.
- Regulatory exclusivity has ended.
- The patient population is narrow.
- Patent terms have advanced toward expiration.
- Generic manufacturers can evaluate alternative formulations and supply routes.
- Modern HIV regimens reduce the addressable market.
The remaining estate may still delay entry or support settlement leverage, but it is unlikely to create a new period of premium growth. Patent strength should be rated as moderate for short-term defensive purposes and weak for long-term revenue expansion.
What patent litigation affects etravirine?
Etravirine has not generated the continuing, high-value patent litigation profile associated with large-market drugs such as lenalidomide, adalimumab, or semaglutide. Litigation risk remains relevant around ANDA certifications, but the expected damages base is constrained by the product’s declining and specialized market.
The key litigation questions are:
- Which patents remain listed for the specific strength and dosage form?
- Did an applicant submit a Paragraph IV certification?
- Was a timely infringement action filed?
- Is the asserted patent valid and enforceable?
- Would a judgment block all generic use or only a defined method?
- Is the generic applicant exposed to damages from an at-risk launch?
Key Takeaways
- Etravirine is a mature, treatment-experienced HIV medicine with declining strategic importance.
- Its core commercial value comes from resistance management, not first-line treatment.
- INSTI-based regimens and single-tablet therapies have reduced demand for new etravirine starts.
- Janssen does not publicly disclose a reliable standalone Intelence revenue series.
- The product’s financial trajectory is negative to low-single-digit decline, with greater erosion after generic entry.
- Etravirine is a small molecule and has no biosimilar risk.
- Generic risk depends on current Orange Book listings, patent expiry, ANDA certifications, and market economics.
- The historical composition patent provided the strongest protection; remaining formulation and method-of-use rights are less likely to sustain premium pricing.
- Patent litigation risk exists but is economically smaller than for blockbuster products.
- Janssen’s broader HIV franchise, especially darunavir-based products, has greater commercial importance than Intelence.
FAQs
Is etravirine still prescribed in 2025?
Yes. It remains relevant for selected treatment-experienced patients, particularly those with resistance or limited treatment options, although it is not a routine first-line HIV therapy.
Is Intelence the same as etravirine?
Yes. Intelence is the branded product containing etravirine.
Can a generic manufacturer automatically substitute for Intelence?
Substitution depends on FDA approval, therapeutic-equivalence designation, state pharmacy law, payer policy, and the specific product strength and indication.
Does etravirine have a long-acting injectable competitor?
No direct long-acting etravirine formulation is commercially established. Long-acting cabotegravir and rilpivirine compete for selected patients but do not replicate etravirine’s resistance-management role.
Is etravirine commercially attractive for generic manufacturers?
It can be attractive as a portfolio product, but the narrow patient population, declining use, patent analysis, and limited volume reduce its standalone economic appeal.
References
-
U.S. Food and Drug Administration. (2024). Intelence (etravirine) prescribing information. FDA.
-
U.S. Department of Health and Human Services. (2024). Guidelines for the use of antiretroviral agents in adults and adolescents with HIV. ClinicalInfo.HIV.gov.
-
U.S. Patent and Trademark Office. (n.d.). Patent Center and patent records for U.S. Patent No. 7,598,374. USPTO.
-
U.S. Food and Drug Administration. (2024). Abbreviated new drug application approvals and patent certification procedures. FDA.
-
Johnson & Johnson. (2024). Annual report for the fiscal year ended December 31, 2023. Johnson & Johnson.