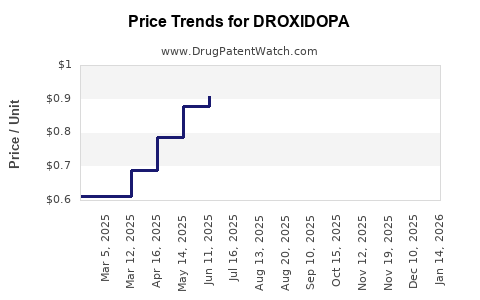
Last updated: August 25, 2026
Droxidopa is a mature, U.S.-centered specialty drug with a declining but durable revenue base. Lundbeck’s Northera franchise benefited from limited competition, a high-value autonomic-disorders market, and repeat chronic use. Its trajectory is now constrained by generic midodrine competition, potential droxidopa generics, narrow prescribing volume, payer controls, and the absence of meaningful label expansion. The principal commercial risk is generic substitution rather than biosimilar competition.
Droxidopa Market Dynamics, Patent Exposure, and Financial Trajectory
What is droxidopa and which company markets it?
Droxidopa is an orally administered synthetic precursor of norepinephrine. It is marketed in the United States as Northera by Lundbeck. The drug is approved to treat neurogenic orthostatic hypotension associated with Parkinson disease, multiple system atrophy, pure autonomic failure, and related autonomic dysfunction [1].
Chelsea Therapeutics developed droxidopa in the United States. Lundbeck acquired Chelsea in 2014 for approximately $658 million, gaining Northera and the company’s late-stage development portfolio [2]. Lundbeck later completed the acquisition and commercialized Northera as a specialty product focused primarily on neurology and autonomic-disorder specialists.
Key product facts
| Attribute |
Droxidopa/Northera |
| Active ingredient |
Droxidopa |
| Brand |
Northera |
| U.S. sponsor |
Lundbeck |
| FDA approval |
2014 |
| Dosage forms |
100 mg, 200 mg, and 300 mg capsules |
| Main indication |
Neurogenic orthostatic hypotension |
| Primary prescribers |
Neurologists, movement-disorder specialists, autonomic specialists |
| Market type |
Specialty chronic therapy |
| Generic status |
Generic substitution risk exists; midodrine is already generic |
| Biosimilar risk |
None, because droxidopa is a small molecule |
The drug’s commercial value comes from treating symptomatic neurogenic orthostatic hypotension in patients who may have limited alternatives. Its market is clinically important but comparatively small because the underlying disorders are uncommon and diagnosis is specialized.
How large is the droxidopa market?
The commercial market is concentrated in the United States. Northera has limited international revenue relevance compared with Lundbeck’s larger psychiatric and migraine products. U.S. demand is driven by chronic treatment, specialist prescribing, and patients who do not respond adequately to midodrine or cannot tolerate its adverse-effect profile.
The addressable population includes patients with Parkinson disease, multiple system atrophy, pure autonomic failure, and other causes of autonomic failure. Only a subset develops clinically significant neurogenic orthostatic hypotension, and an even smaller subset receives droxidopa after diagnostic confirmation and payer review.
Main competing therapies
| Therapy |
Status |
Commercial effect on droxidopa |
| Midodrine |
Generic, widely used |
Principal price and utilization competitor |
| Fludrocortisone |
Generic, frequently used off label |
Low-cost alternative |
| Pyridostigmine |
Generic, often used off label |
Alternative for selected patients |
| Compression and volume-expansion measures |
Non-drug treatment |
Reduces drug use in mild disease |
| Droxidopa |
Branded and specialty priced |
Used when symptoms persist or alternatives are unsuitable |
Midodrine has a major structural advantage: it is inexpensive, familiar to prescribers, and available from multiple generic manufacturers. Droxidopa competes by offering a different pharmacologic mechanism and, for some patients, better treatment fit rather than by competing on price.
What was the financial trajectory for Northera?
Northera generated meaningful revenue for Lundbeck but never became a company-defining product. Public financial disclosures indicate that sales peaked after the U.S. launch and then declined as the product matured and payer, access, and competitive pressures increased.
| Fiscal year |
Approximate Northera revenue |
Revenue trend |
| 2018 |
Approximately DKK 1.7 billion |
Near peak commercial contribution |
| 2019 |
Approximately DKK 1.5 billion |
Declining |
| 2020 |
Approximately DKK 1.3 billion |
Continued erosion |
| 2021 |
Approximately DKK 1.2 billion |
Mature-product decline |
| 2022 |
Approximately DKK 1.1 billion |
Further reduction |
| 2023 |
Approximately DKK 1.0 billion |
Stable but lower base |
Figures are based on Lundbeck annual-report product disclosures and are presented as approximate values because reporting classifications and currency translation affect year-to-year comparisons [3-8].
The broad pattern is more important than any single annual figure: Northera moved from a growth asset to a mature specialty franchise. The decline reflects several factors:
- The diagnosed population is limited.
- Midodrine remains a low-cost first-line or comparator therapy.
- Payers often require documentation of neurogenic orthostatic hypotension and prior therapy.
- Northera requires dose titration and monitoring.
- Generic entry risk has increased as key exclusivity periods mature.
- Lundbeck has concentrated capital and commercial resources on newer growth products.
Revenue exposure
Northera is material to Lundbeck’s neurology portfolio but not to the company’s overall valuation in the same way as Rexulti, Vyepti, or other larger products. A steep Northera decline would reduce specialty-care revenue, but it would not create the same group-level exposure as the loss of a top-selling psychiatric product.
The franchise remains attractive because operating costs are relatively contained after launch infrastructure has been established. The principal value question is therefore how long branded net pricing and patient retention can offset lower volume.
When did droxidopa receive FDA approval?
The FDA approved Northera in February 2014 under an accelerated approval framework for symptomatic neurogenic orthostatic hypotension. The approval was based on short-term changes in a symptom measure, particularly dizziness or lightheadedness, and the FDA required postmarketing work to verify clinical benefit [1, 9].
The label states that Northera’s effectiveness beyond a short-term treatment period was not established in the registration trials. That limitation affects commercial positioning because prescribers and payers must evaluate continued treatment based on patient-level functional benefit.
FDA regulatory status
| Regulatory issue |
Status |
| U.S. approval |
Approved |
| Approval pathway |
Accelerated approval |
| Indication |
Symptomatic neurogenic orthostatic hypotension |
| Postmarketing obligations |
Required to verify clinical benefit |
| Biologic pathway |
Not applicable |
| New chemical entity exclusivity |
Expired |
| Pediatric exclusivity |
No major current commercial effect |
| Orphan-drug exclusivity |
Not the principal current barrier to generic entry |
Droxidopa is a small molecule, so competitors can file abbreviated new drug applications rather than biosimilar applications. The relevant regulatory contest is an ANDA and potential Paragraph IV litigation, not a biosimilar interchangeability proceeding.
What patents protect droxidopa and Northera?
Droxidopa’s U.S. protection has relied on composition, formulation, dosing, and method-of-use patents rather than a single broad platform patent with indefinite commercial life. The relevant estate includes patents associated with droxidopa treatment, titration, and use in neurogenic orthostatic hypotension.
Public patent databases and FDA Orange Book records identify patent families associated with droxidopa, including U.S. Patent Nos. 8,007,826 and 8,735,438, along with related continuation or method-of-use filings. Exact enforceability depends on claim scope, terminal disclaimers, patent-term adjustment, listed use codes, and any later court or Patent Trial and Appeal Board action [10, 11].
Patent-estate characteristics
| Protection category |
Commercial role |
| Active-ingredient protection |
Protects the molecule or specific chemical form where claims remain enforceable |
| Formulation protection |
Can cover capsule composition, stability, or release characteristics |
| Method-of-use protection |
Targets treatment of neurogenic orthostatic hypotension and associated symptoms |
| Dosing and titration protection |
May restrict specific dose-escalation or administration methods |
| Manufacturing protection |
Can raise development costs but is less effective if non-infringing processes are available |
| Regulatory exclusivity |
Provides historical protection but is largely expired for this product |
The estate is weaker than it was during the first several years after launch because the earliest exclusivity periods have expired or are approaching the end of their commercial relevance. The remaining value depends on whether later patents cover commercially necessary use codes or merely optional treatment methods.
What is the Orange Book status of Northera?
Northera’s Orange Book position is relevant because listed patents can support a Paragraph IV certification and trigger litigation under the Hatch-Waxman framework. The Orange Book does not itself determine whether a patent is valid or infringed. It identifies patents and approved uses that an ANDA applicant must address.
A generic applicant can certify that a listed patent has expired, will expire before launch, is not infringed, or is invalid. A Paragraph IV notice can prompt a patent-infringement lawsuit and, if filed within the statutory period, delay FDA approval for up to 30 months, subject to litigation developments [12].
Paragraph IV risk
The commercial risk is highest where:
- the generic seeks approval for the full labeled indication;
- listed method-of-use patents remain unexpired;
- the brand has enforceable claims covering the principal prescribing population;
- the generic can launch profitably despite relatively low total market volume;
- the product has high branded net pricing and a simple oral dosage form.
Droxidopa’s capsule formulation is comparatively straightforward. That lowers manufacturing barriers relative to complex injectables, depot products, inhaled systems, or biologics. Any remaining patent protection must therefore be evaluated against the likelihood that a generic can design around formulation or process claims.
What formulation patents protect droxidopa?
Formulation patents can protect capsule composition, excipients, stability, dissolution, and dosage strength. Their practical value depends on whether a generic must use the same formulation to meet bioequivalence and product-quality requirements.
For droxidopa, formulation protection is less likely to create a durable barrier than it would for a controlled-release product or a complex delivery system. The approved product is an oral capsule with conventional dose strengths. A generic manufacturer may have several routes to a bioequivalent formulation.
The strongest formulation claims would be those that:
- cover all commercially viable excipient combinations;
- are difficult to design around without affecting bioequivalence;
- align with the FDA-listed product characteristics;
- remain enforceable after patent expiration analysis.
What method-of-use patents affect droxidopa?
Method-of-use patents may cover the treatment of neurogenic orthostatic hypotension in defined patient groups, specific dosing schedules, or titration protocols. Their value is limited by the scope of the approved indication and the legal distinction between labeled and unapproved uses.
If a generic applicant files a skinny-label ANDA that omits patented uses, the brand may have less ability to block approval. If the patented use is inseparable from the core indication or is routinely practiced despite label language, enforcement becomes more complex.
For Northera, method-of-use protection has commercial relevance because the approved indication is narrow. A patent covering the principal neurogenic orthostatic hypotension population can be more valuable than a patent covering a marginal subpopulation. The opposite is also true: a narrow claim may have limited blocking power if physicians can prescribe the generic for an unpatented use.
How strong is the droxidopa patent estate?
The estate is moderate during the remaining patent term but weak as a long-term franchise barrier.
Strengths
- Specialty indication with relatively concentrated prescribing.
- Established regulatory record and commercial product.
- Potential method-of-use claims directed at a defined disease population.
- High switching friction for patients who are stable on treatment.
- Specialist knowledge and payer documentation requirements.
Weaknesses
- Small-molecule product eligible for ANDA competition.
- Conventional oral capsule dosage form.
- Generic midodrine creates a strong low-cost alternative.
- Limited market size may reduce the cost of patent litigation for an entrant.
- Method-of-use patents can face skinny-label and non-infringement strategies.
- Historical accelerated-approval limitations can affect payer confidence.
The patent estate can delay generic entry, but it is unlikely to support long-duration exclusivity after the principal listed patents expire. The commercial moat rests as much on diagnosis, specialist adoption, patient response, and payer access as on patent scope.
What generic entry risks exist for droxidopa?
Generic entry would likely produce a rapid decline in branded volume if the FDA approves a therapeutically equivalent capsule and major payers place it on preferred tiers. The decline would not necessarily be immediate or complete because:
- some neurologists may retain patients on Northera;
- specialty pharmacies may support brand continuity;
- certain patients may respond differently to product changes;
- payer contracts may create temporary brand access protections;
- the market is small enough that generic supply may initially be limited.
A first generic could receive substantial market-share economics through an abbreviated competition period, depending on the timing and exclusivity status of the first applicant. Subsequent entrants would increase price erosion.
Generic launch scenarios
| Scenario |
Likely commercial result |
| No near-term generic approval |
Northera declines gradually through lower volume and payer pressure |
| One generic entrant |
Rapid price concessions and meaningful brand share loss |
| Multiple generic entrants |
Steep net-price erosion and possible loss of preferred access |
| Patent settlement with delayed entry |
Brand retains value until the agreed launch date |
| Paragraph IV victory for generic |
Earlier and more severe revenue erosion |
| Brand patent victory |
Temporary extension of specialty revenue, not permanent protection |
The highest-risk outcome for Lundbeck is an at-risk generic launch that follows a successful Paragraph IV challenge or settlement permitting entry before all listed patents expire.
Are biosimilars a risk for droxidopa?
No. Droxidopa is a small molecule, not a biologic. The relevant competitors are generic manufacturers, not biosimilar developers. This distinction matters because an ANDA applicant generally faces a shorter and less technically complex development pathway than a biosimilar applicant.
The absence of biosimilar risk does not make the product safer commercially. Small-molecule generic substitution is usually more direct once regulatory and patent barriers fall.
Which companies compete with droxidopa?
The competitive landscape includes generic pharmaceutical companies selling midodrine and fludrocortisone, as well as manufacturers of pyridostigmine. Competition is fragmented at the product level but concentrated at the treatment-decision level.
Competitive positioning
| Product |
Main advantage |
Main limitation |
| Northera |
Mechanistically differentiated; useful in neurogenic disease |
High cost and access controls |
| Generic midodrine |
Low price and broad familiarity |
Supine hypertension and dosing limitations |
| Fludrocortisone |
Low cost and long clinical use |
Off-label use and electrolyte or fluid-related risks |
| Pyridostigmine |
Option for selected patients |
Variable efficacy and off-label positioning |
Northera’s strongest defense is clinical differentiation in patients whose symptoms remain inadequately controlled with low-cost alternatives. Its weakest defense is routine use in patients for whom midodrine or another generic treatment is clinically acceptable.
What licensing deals affect droxidopa?
The main transaction shaping droxidopa’s economics was Lundbeck’s acquisition of Chelsea Therapeutics. The transaction transferred the commercial and development rights for Northera to Lundbeck and provided Chelsea shareholders with upfront and contingent consideration [2].
There is no major publicly disclosed licensing arrangement that currently changes the core Northera market structure. Lundbeck remains the principal commercial stakeholder in the U.S. franchise. The relevant strategic question is whether Lundbeck continues to operate the product as a cash-generating mature asset or reduces investment as generic risk increases.
What litigation and settlement issues affect Northera?
Droxidopa’s litigation exposure is principally Hatch-Waxman patent litigation involving ANDA filers. Key issues include:
- Paragraph IV certifications against Orange Book-listed patents;
- validity challenges under obviousness, written description, and enablement standards;
- infringement claims involving treatment methods or formulation features;
- skinny-label strategies;
- settlement agreements that specify delayed generic entry;
- potential antitrust scrutiny if a settlement involves compensation or unusual restrictions.
A settlement can preserve brand revenue until an agreed entry date while allowing the generic applicant to avoid the cost and uncertainty of trial. The economic value of such a settlement depends on the remaining patent term, market size, expected generic price erosion, and the probability of a brand win.
How does droxidopa compare with other specialty neurology drugs?
Droxidopa has a smaller market and a narrower indication than Lundbeck’s leading specialty products. It also has less platform value because it is a single oral small molecule with no biologic manufacturing complexity, device ecosystem, or broad disease franchise.
| Factor |
Droxidopa |
Large specialty neurology product |
| Patient population |
Narrow |
Often broader |
| Price sensitivity |
High |
Variable |
| Generic risk |
Direct ANDA risk |
Depends on molecule and formulation |
| Manufacturing barrier |
Moderate to low |
Can be high for biologics or devices |
| Label expansion potential |
Limited |
Often greater |
| Revenue durability |
Dependent on patent and access |
May benefit from multiple indications |
| Strategic value |
Mature cash generator |
Growth or platform asset |
Droxidopa’s value is therefore defensive and cash-flow oriented. It can remain profitable after peak sales, but it is unlikely to regain rapid growth without a new indication, superior evidence, or a meaningful change in treatment guidelines.
What is the outlook for droxidopa revenue?
The base case is continued decline followed by a lower, stable specialty-product revenue stream before or after generic entry. The timing depends on patent enforcement, ANDA activity, payer behavior, and the number of approved generic manufacturers.
Revenue drivers
- Chronic treatment duration.
- Growth in diagnosis of autonomic disorders.
- Specialist awareness.
- Patient response after titration.
- Reimbursement and specialty-pharmacy support.
- Lack of a clearly superior branded replacement.
Revenue risks
- Generic droxidopa approval.
- Expanded use of low-cost midodrine.
- Payer step edits and prior authorization.
- Failure to verify durable clinical benefit.
- Limited clinical evidence outside the approved indication.
- Declining promotional investment.
- Patent invalidation or early settlement.
A successful patent defense could preserve a high-margin revenue stream for several years. It would not eliminate the longer-term problem that a conventional oral small molecule eventually faces generic substitution.
Key Takeaways
- Droxidopa is marketed in the United States as Northera by Lundbeck.
- FDA approval dates to 2014 for symptomatic neurogenic orthostatic hypotension.
- The franchise is a mature specialty asset with revenue that has declined from approximately DKK 1.7 billion in 2018 to roughly DKK 1.0 billion in 2023.
- Generic midodrine is the primary current competitor.
- Direct generic droxidopa competition is the main future commercial risk.
- Biosimilars are irrelevant because droxidopa is a small molecule.
- Formulation and method-of-use patents may delay competition but are unlikely to create indefinite protection.
- The commercial moat depends on specialist prescribing, patient response, payer access, and treatment persistence.
- Northera remains a cash-generating product, but its strategic value is lower than that of Lundbeck’s growth franchises.
- Generic entry would likely produce rapid price erosion, reduced brand volume, or both.
FAQs
Is droxidopa still under patent protection?
Some patent claims associated with droxidopa treatment, formulation, and use may remain relevant depending on patent-term calculations and the specific Orange Book listing. The commercial protection is materially weaker than during the initial post-launch period.
Can a generic manufacturer launch droxidopa before every Northera patent expires?
Potentially. An ANDA applicant may use Paragraph IV, expiration, invalidity, non-infringement, or skinny-label strategies. A launch before patent expiration could trigger litigation and a statutory approval stay.
Why is Northera more expensive than midodrine?
Northera is a branded specialty drug with a narrower indication, specialist distribution model, and limited direct competition. Midodrine is an established generic with multiple suppliers and substantially lower acquisition cost.
Does droxidopa have orphan-drug exclusivity?
The product’s commercial protection is primarily associated with patents, regulatory exclusivity history, and market specialization. Any historical orphan designation or exclusivity does not eliminate current ANDA-based generic risk.
Could Lundbeck expand droxidopa into additional neurologic indications?
Expansion is possible only if supported by clinical evidence, FDA review, and a commercially meaningful patient population. The narrow mechanism and mature product profile make major label expansion less likely than lifecycle management through access, evidence, or formulation strategies.
References
- U.S. Food and Drug Administration. (2014). Northera (droxidopa) prescribing information. https://www.accessdata.fda.gov
- Lundbeck. (2014). Lundbeck completes acquisition of Chelsea Therapeutics. https://www.lundbeck.com
- H. Lundbeck A/S. (2018). Annual report 2018. https://www.lundbeck.com
- H. Lundbeck A/S. (2019). Annual report 2019. https://www.lundbeck.com
- H. Lundbeck A/S. (2020). Annual report 2020. https://www.lundbeck.com
- H. Lundbeck A/S. (2021). Annual report 2021. https://www.lundbeck.com
- H. Lundbeck A/S. (2022). Annual report 2022. https://www.lundbeck.com
- H. Lundbeck A/S. (2023). Annual report 2023. https://www.lundbeck.com
- U.S. Food and Drug Administration. (2014). FDA approves Northera to treat neurogenic orthostatic hypotension. https://www.fda.gov
- U.S. Patent and Trademark Office. (2006). U.S. Patent No. 8,007,826. https://patents.google.com
- U.S. Patent and Trademark Office. (2014). U.S. Patent No. 8,735,438. https://patents.google.com
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book. https://www.accessdata.fda.gov/scripts/cder/ob/