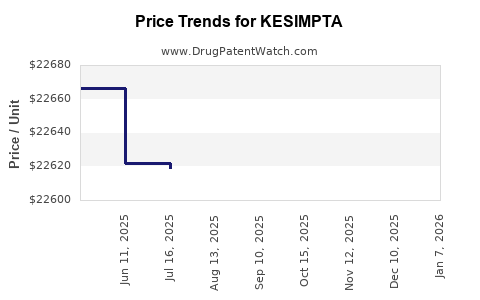
Last updated: September 27, 2026
Kesimpta generated approximately $3.4 billion in global sales in 2024, up from roughly $2.3 billion in 2023, according to Novartis reporting. Its growth is being driven by rapid uptake in relapsing multiple sclerosis, increasing use earlier in treatment, and patient preference for a self-administered monthly injection. Kesimpta competes primarily with Roche’s Ocrevus and Biogen’s Tysabri, while UCB’s Briumvi adds pressure in high-efficacy multiple sclerosis treatment.
Kesimpta’s commercial position is strong, but its long-term trajectory depends on market conversion from established anti-CD20 therapies, payer management, competition from subcutaneous Ocrevus, and the timing of potential ofatumumab biosimilars after US regulatory exclusivity expires.
How large is the Kesimpta market and how fast are sales growing?
Kesimpta is one of Novartis’s fastest-growing products and has become a multibillion-dollar franchise within four years of launch.
| Fiscal year |
Approximate Kesimpta sales |
Year-over-year trend |
| 2020 |
Less than $0.1 billion |
US launch year |
| 2021 |
Approximately $0.5 billion |
Rapid initial adoption |
| 2022 |
Approximately $1.4 billion |
Expansion across major markets |
| 2023 |
Approximately $2.3 billion |
Strong patient and prescriber growth |
| 2024 |
Approximately $3.4 billion |
Continued share gains |
Source: Novartis annual and quarterly financial disclosures [1, 2].
Kesimpta represented approximately 6% to 7% of Novartis’s 2024 Innovative Medicines sales. The product is now large enough to affect group earnings expectations, although it remains smaller than Entresto and Cosentyx.
The sales trajectory reflects three commercial factors:
- Kesimpta is positioned as a high-efficacy therapy for relapsing forms of multiple sclerosis.
- Monthly self-injection avoids infusion-center administration.
- Patients can move from initial loading doses to a once-monthly maintenance schedule.
The launch has also benefited from broader adoption of high-efficacy treatment earlier in the multiple sclerosis disease course. Earlier use increases the addressable patient pool and extends treatment duration before treatment switching or disability progression.
What is driving Kesimpta revenue growth?
Kesimpta’s growth is based on prescription volume rather than major price expansion. Novartis has reported continued growth in new patient starts, total patients on therapy, and market share in the US and key European markets.
Patient preference and administration economics
Kesimpta is administered subcutaneously at home after the initial loading schedule. This differentiates it from intravenous Ocrevus, which traditionally requires infusion-center visits. The home-use model can reduce:
- Infusion-center costs
- Patient travel and time burden
- Administration-related healthcare utilization
- Dependence on infusion capacity
The commercial advantage is strongest for patients and payers that value convenience and lower site-of-care costs. The advantage is weaker where payers impose step therapy, where infusion reimbursement favors providers, or where patients prefer supervised administration.
High-efficacy treatment positioning
Kesimpta targets relapsing forms of multiple sclerosis, including clinically isolated syndrome, relapsing-remitting disease, and active secondary progressive disease under its US label. The product reduces B-cell activity through CD20-directed depletion.
Novartis has used the ASCLEPIOS I and II studies to support efficacy against teriflunomide, showing lower annualized relapse rates and favorable MRI outcomes in adults with relapsing multiple sclerosis [3]. The evidence supports positioning Kesimpta against oral disease-modifying therapies rather than only against injectable legacy products.
Geographic expansion
The US remains the principal revenue market, but Kesimpta has regulatory approvals across Europe and other international markets. European uptake is moderated by centralized pricing negotiations, country-level reimbursement decisions, and hospital prescribing controls.
Market access is therefore uneven. Germany and the United Kingdom can support rapid launch uptake when reimbursement is secured, while Southern European and certain emerging markets may produce lower net pricing and slower penetration.
How does Kesimpta compare with Ocrevus, Briumvi, and Tysabri?
Kesimpta competes in a high-value segment where efficacy, administration, safety monitoring, payer restrictions, and treatment persistence all influence product selection.
| Product |
Company |
Mechanism |
Administration |
Key commercial advantage |
| Kesimpta |
Novartis |
Anti-CD20 B-cell depletion |
Monthly subcutaneous injection |
Home administration and high-efficacy positioning |
| Ocrevus |
Roche |
Anti-CD20 B-cell depletion |
Intravenous infusion; subcutaneous formulation emerging |
Largest established anti-CD20 franchise |
| Briumvi |
UCB |
Anti-CD20 B-cell depletion |
Intravenous infusion |
Newer high-efficacy competitor |
| Tysabri |
Biogen |
Anti-integrin |
Intravenous or subcutaneous administration |
Long clinical history and high efficacy |
| Aubagio |
Sanofi |
Pyrimidine synthesis inhibitor |
Oral |
Established oral generic pressure |
| Gilenya and other S1P therapies |
Novartis and others |
S1P receptor modulation |
Oral |
Oral convenience and broad physician familiarity |
Ocrevus remains the main competitive benchmark. Its large installed base, physician familiarity, and strong efficacy profile create switching resistance. Kesimpta has an administration advantage for patients who prefer self-injection, but Ocrevus retains value for patients who prefer twice-yearly or less frequent supervised treatment.
Roche’s development of a subcutaneous Ocrevus formulation narrows Kesimpta’s convenience advantage. If subcutaneous Ocrevus gains broad adoption, competition will shift from home injection versus infusion to dosing interval, device experience, payer placement, and patient persistence.
Briumvi is a more direct anti-CD20 competitor but has a smaller commercial base. Its impact is likely to be greater in accounts seeking price competition or an alternative infusion option than in the total market.
What is the FDA regulatory status of Kesimpta?
The FDA approved Kesimpta in August 2020 for adults with relapsing forms of multiple sclerosis [4]. The product is a fully human anti-CD20 monoclonal antibody supplied as a prefilled syringe and autoinjector for subcutaneous administration.
The US dosing schedule consists of:
- Initial dose at week 0
- Second dose at week 1
- Third dose at week 2
- Maintenance dose beginning at week 4 and continuing monthly
The label includes warnings relating to infections, immunoglobulin reduction, hepatitis B reactivation, injection-related reactions, and fetal risk. These safety considerations affect monitoring and physician selection but have not prevented broad uptake.
Kesimpta is a biologic, not a small-molecule drug. It is therefore governed by the Biologics Price Competition and Innovation Act pathway rather than the abbreviated new drug application pathway used for conventional generics.
When does Kesimpta lose exclusivity?
Kesimpta’s US regulatory exclusivity is expected to run for 12 years from the date of first licensure, placing the principal US biologic exclusivity milestone in 2032.
| Exclusivity or protection type |
Expected timing |
Commercial significance |
| US biologic regulatory exclusivity |
2032 |
FDA cannot approve a biosimilar relying on the reference product during the statutory period |
| US patent protection |
Varies by patent family |
Certain patents may extend beyond regulatory exclusivity |
| European data exclusivity |
Approximately 2029, based on 2021 authorization |
Limits reliance on the reference dossier |
| European market protection |
Approximately 2031 |
Delays commercial launch after data exclusivity |
| Pediatric extension |
Potentially one additional year if applicable |
Depends on completion of an approved pediatric plan |
The patent position is separate from the 12-year US biologic exclusivity period. A biosimilar sponsor could prepare and file before 2032, but commercial launch would remain subject to regulatory exclusivity and enforceable patent rights.
What patents protect Kesimpta and ofatumumab?
Kesimpta’s protection is likely distributed across several patent categories rather than a single composition-of-matter patent. Relevant categories include:
- Ofatumumab antibodies and antibody variants
- Anti-CD20 binding properties
- Use of ofatumumab in multiple sclerosis
- Dosing schedules and treatment regimens
- Formulation and concentration
- Prefilled syringe and autoinjector presentations
- Manufacturing and purification processes
Kesimpta does not have a conventional Orange Book listing because the Orange Book primarily covers approved small-molecule drugs and certain related products. Biologic reference products are tracked through FDA’s Purple Book framework [5].
This distinction matters for litigation strategy. A potential biosimilar sponsor would generally use the BPCIA patent-exchange process rather than rely on a traditional Hatch-Waxman Paragraph IV certification. A Paragraph IV challenge is therefore not the standard route for challenging Kesimpta.
Novartis and its predecessors have maintained a broader ofatumumab patent estate because ofatumumab was developed for more than one indication. Earlier ofatumumab rights originated with Genmab. Novartis obtained rights to develop ofatumumab in autoimmune disease, including multiple sclerosis, under a 2015 agreement with Genmab [6].
Patent term adjustments, terminal disclaimers, continuation applications, and jurisdiction-specific prosecution can produce different expiration dates. The commercially important issue is whether secondary patents covering formulation, dosing, device presentation, or manufacturing survive through the first potential biosimilar launch window.
Are there Paragraph IV challenges or biosimilar competitors to Kesimpta?
No major publicly disclosed US biosimilar litigation against Kesimpta had materially affected the product through the end of 2024.
The likely competitive pathway is a BPCIA biosimilar program rather than a Paragraph IV generic challenge. A biosimilar sponsor would need to establish analytical similarity, demonstrate a sufficient clinical bridge, and address manufacturing comparability. Interchangeability would require a separate showing under FDA standards if the sponsor seeks pharmacy-level substitution.
Potential biosimilar barriers include:
- Complex glycosylated antibody structure
- Sensitive cell-line and fermentation processes
- Comparability of impurity profiles
- Demonstration of equivalent pharmacokinetics and pharmacodynamics
- Device compatibility for autoinjector or syringe delivery
- Immunogenicity assessment
- Patent disputes involving dosing, formulation, and manufacturing
A biosimilar could enter after regulatory exclusivity and surviving patent protection expire. The first launch would probably target payer contracts and institutional accounts before generating broad pharmacy substitution.
How strong is the Kesimpta patent estate?
The Kesimpta estate is commercially strong through the early 2030s because regulatory exclusivity provides a substantial barrier independent of patent enforcement. Its post-2032 strength depends on the durability of secondary patents and the ability to defend them against biosimilar applicants.
Composition and antibody patents
Composition and antibody claims generally provide the strongest protection when they directly cover the commercial molecule or a necessary antibody sequence. Their value declines rapidly after expiration because a biosimilar applicant can design around narrower claims only if the reference molecule itself is not protected.
Method-of-use patents
Method-of-use patents covering treatment of relapsing multiple sclerosis, dosing intervals, patient populations, or sequencing with other therapies can create litigation leverage. Their practical value is narrower because biosimilar applicants may seek labeling that omits protected indications or dosing instructions.
Formulation and device patents
Formulation and delivery patents can delay substitution but rarely prevent all biological competition. A biosimilar sponsor may use a different concentration, container, syringe, or autoinjector if it can demonstrate equivalent performance.
Manufacturing patents
Manufacturing patents can be important where the commercial product depends on a specific cell line, purification sequence, or process condition. Manufacturing claims are often difficult for a reference-product sponsor to monitor because a competitor’s process is not publicly visible. They can still increase settlement pressure if supported by strong technical evidence.
What licensing deal supports Kesimpta economics?
Novartis licensed ofatumumab autoimmune rights from Genmab in 2015. The agreement included an upfront payment, development and regulatory milestones, and royalties on commercial sales [6].
The deal gave Novartis control of development and commercialization in autoimmune disease while allowing Genmab to retain economic participation. Kesimpta’s growth therefore generates value for both companies, although Novartis captures the principal commercial economics through global sales and marketing.
The transaction also reduced Novartis’s need to discover and develop a new anti-CD20 antibody internally. Its success demonstrates the financial value of acquiring rights to a clinically validated antibody platform and redirecting it toward a large chronic disease market.
What revenue exposure does Novartis have to Kesimpta?
Kesimpta is material but not dominant within Novartis’s portfolio.
| Metric |
Approximate 2024 position |
| Kesimpta sales |
$3.4 billion |
| Novartis group sales |
$50 billion |
| Estimated share of group sales |
About 7% |
| Primary exposure |
Relapsing multiple sclerosis |
| Main commercial risk |
Anti-CD20 competition and eventual biosimilar erosion |
The product’s revenue contribution should continue rising if patient additions remain strong. Its growth rate will likely moderate as the installed base becomes larger, payer restrictions stabilize, and Ocrevus introduces a competitive subcutaneous option.
The principal downside scenario is not an immediate patent cliff. It is a gradual reduction in new patient share caused by competitive switching, payer contracting, and comparable convenience from competing anti-CD20 products.
What generic or biosimilar launch scenarios exist for Kesimpta?
Base case
Kesimpta continues to grow through the late 2020s, with slowing annual growth as the product reaches a larger share of high-efficacy relapsing multiple sclerosis treatment. Novartis retains premium pricing because of clinical familiarity, device integration, and physician confidence.
Competitive pressure case
Subcutaneous Ocrevus gains meaningful adoption and reduces Kesimpta’s share of new anti-CD20 starts. Novartis responds through contracting, patient support, and evidence generation focused on persistence and home administration.
Biosimilar entry case
A biosimilar enters after 2032, subject to patent resolution. Initial discounts are moderate because multiple sclerosis treatment decisions are specialist-driven and patients may remain on the originator product. Price erosion accelerates if two or more biosimilars enter and payers establish automatic substitution policies.
Litigation delay case
Novartis asserts formulation, dosing, device, or manufacturing patents against a biosimilar applicant. The dispute produces a settlement with a delayed entry date rather than an immediate launch. The economic value of the settlement depends on whether the entry date is before or after key European and US exclusivity milestones.
What patent litigation affects Kesimpta?
No high-profile US BPCIA litigation had produced a known market-disrupting judgment against Kesimpta through the end of 2024. The primary litigation risk remains prospective and would arise when biosimilar developers begin formal patent negotiations.
The most likely disputes would concern:
- Scope of antibody claims
- Treatment regimens for multiple sclerosis
- Monthly maintenance dosing
- Liquid formulation and concentration
- Prefilled delivery systems
- Cell culture and purification methods
A settlement could permit an agreed launch before the expiration of every asserted patent. Such agreements would face antitrust scrutiny if they included consideration for delayed entry or restrictions on biosimilar commercialization.
What is the outlook for Kesimpta revenue?
Kesimpta has a credible path to remain a multibillion-dollar product through the late 2020s. The near-term growth case depends on continued conversion from oral therapies and infused anti-CD20 treatment, particularly among patients seeking high efficacy without recurring infusion-center visits.
Longer-term revenue is constrained by three factors:
- The multiple sclerosis market is mature in major economies.
- Ocrevus has a large and durable commercial base.
- Anti-CD20 competition will intensify before biologic exclusivity expires.
The product’s best defense is not price alone. It is a combination of treatment persistence, patient convenience, physician familiarity, real-world outcomes, and a patent estate that delays or complicates biosimilar substitution.
Key Takeaways
- Kesimpta sales reached approximately $3.4 billion in 2024, making it a major Novartis growth product.
- The principal market is relapsing multiple sclerosis, where high-efficacy treatment is moving earlier in the disease course.
- Monthly self-administration is Kesimpta’s main commercial differentiator against intravenous Ocrevus.
- US biologic regulatory exclusivity is expected to extend to 2032.
- Kesimpta is governed by the Purple Book and BPCIA framework, not the conventional Orange Book and Paragraph IV system.
- No major publicly disclosed biosimilar litigation had materially disrupted Kesimpta through the end of 2024.
- The main competitive threat is Ocrevus, especially if Roche’s subcutaneous formulation gains broad uptake.
- Post-2032 biosimilar erosion will depend on secondary patents covering formulation, dosing, device presentation, and manufacturing.
FAQs
Is Kesimpta more commercially successful than Ocrevus?
No. Ocrevus has a larger total commercial base, but Kesimpta has been growing rapidly and is gaining share among patients who prefer monthly home injection over infusion-center treatment.
Does Kesimpta have an Orange Book patent listing?
No. Kesimpta is a biologic reference product. Its regulatory and patent information is handled through the Purple Book and the BPCIA framework rather than a standard Orange Book listing.
Can a generic company launch Kesimpta after 2032?
A conventional generic cannot rely on the small-molecule abbreviated new drug application pathway. A biosimilar sponsor could seek approval under the BPCIA pathway, subject to remaining patents, regulatory requirements, and any settlement agreement.
What is the largest financial risk to Kesimpta?
The largest medium-term risk is competitive share loss to Ocrevus, Briumvi, and other high-efficacy multiple sclerosis therapies. The largest long-term risk is biosimilar price erosion after regulatory exclusivity and key patent barriers expire.
Who owns the commercial rights to Kesimpta?
Novartis owns the principal autoimmune development and commercial rights. Genmab originated ofatumumab and receives economic benefits under its agreement with Novartis.
References
- Novartis AG. (2025). Annual report 2024. Basel, Switzerland: Author.
- Novartis AG. (2024-2025). Quarterly results and financial reporting materials. Basel, Switzerland: Author.
- Hauser, S. L., Bar-Or, A., Comi, G., Giovannoni, G., Hartung, H.-P., Hemmer, B., Lublin, F., Montalban, X., Rammengan, A., Selmaj, K., Traboulsee, A., Wolinsky, J. S., Arnold, D. L., & ASCLEPIOS I and II Trial Investigators. (2020). Ofatumumab versus teriflunomide in multiple sclerosis. New England Journal of Medicine, 383(6), 546-557.
- U.S. Food and Drug Administration. (2020). FDA approves new treatment for multiple sclerosis. Silver Spring, MD: Author.
- U.S. Food and Drug Administration. (2024). Purple Book: Database of licensed biological products. Silver Spring, MD: Author.
- Genmab A/S. (2015). Genmab and Novartis enter agreement for ofatumumab in autoimmune indications. Copenhagen, Denmark: Author.