Last updated: October 18, 2026
Sesquient is Hikma Pharmaceuticals’ U.S. fosphenytoin sodium injection product, used mainly in hospitals for status epilepticus and as a parenteral substitute for oral phenytoin. Its commercial opportunity is a small, clinically important injectable market rather than a large chronic-care franchise. Hikma does not publicly disclose Sesquient revenue, unit volume, gross margin, or product-level forecasts. Financial analysis therefore depends on FDA records, hospital-use dynamics, competitor supply, and Hikma’s broader injectable segment results.
What is Sesquient and how is it used?
Sesquient contains fosphenytoin sodium, a prodrug of phenytoin. It is administered intravenously or intramuscularly when oral phenytoin cannot be used. FDA-approved indications include:
- Treatment of generalized convulsive status epilepticus
- Prevention and treatment of seizures occurring during neurosurgery
- Short-term substitution for oral phenytoin when oral administration is not possible
The product is dosed in phenytoin sodium equivalents, or PE. This reduces confusion between fosphenytoin quantity and the active phenytoin-equivalent dose.
| Product attribute |
Sesquient status |
| Active ingredient |
Fosphenytoin sodium |
| Dosage form |
Injectable solution |
| U.S. sponsor |
Hikma Pharmaceuticals USA Inc. |
| FDA application |
NDA 209360 |
| Primary setting |
Hospitals, emergency departments, intensive-care units, operating rooms |
| Main clinical use |
Status epilepticus and short-term parenteral seizure control |
| Reference product |
Cerebyx, fosphenytoin sodium injection |
| Therapeutic category |
Anticonvulsant |
| Biosimilar exposure |
None; Sesquient is a small-molecule drug |
FDA labeling identifies clinically important administration risks, including hypotension, cardiac arrhythmias, infusion-related reactions, and dosing errors involving phenytoin equivalents. These risks favor hospital procurement from established injectable suppliers with reliable quality systems. (U.S. Food and Drug Administration [FDA], 2019)
What is the FDA regulatory status of Sesquient?
Sesquient was approved by the FDA in 2019 under NDA 209360. The product is marketed as a prescription injectable for institutional use. Its regulatory position is materially different from a conventional retail generic because the application is an NDA rather than a standard ANDA.
The FDA approval created a commercial product with labeling closely aligned to the established fosphenytoin clinical profile. The relevant commercial barrier was regulatory approval and manufacturing execution, not a substantial patent estate.
Sesquient FDA timeline
| Date |
Event |
| 2019 |
FDA approval of Sesquient under NDA 209360 |
| 2019 onward |
Commercial supply by Hikma in the U.S. hospital injectable market |
| 2022 |
Any three-year approval-based exclusivity associated with the 2019 NDA would generally have ended, subject to the specific FDA listing |
| Current status |
Product remains an FDA-approved injectable marketed by Hikma, subject to supply, labeling and manufacturing compliance |
The FDA Orange Book should be treated as the controlling source for current patents and regulatory exclusivity. Publicly available Orange Book records do not indicate a material active patent barrier protecting Sesquient itself. (FDA, 2024a)
What patents protect Sesquient?
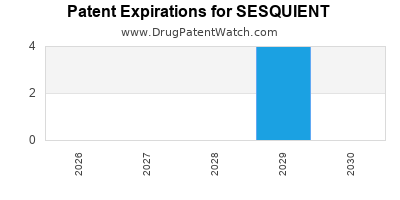
Sesquient does not appear to have a meaningful active Orange Book patent estate. The relevant intellectual-property position is therefore weaker than that of newer branded antiseizure drugs with formulation, polymorph, delivery-device or method-of-use patents.
| IP category |
Sesquient position |
| Active ingredient patent |
No meaningful current barrier identified |
| Product patent |
No material active Orange Book protection identified |
| Formulation patent |
No material active Orange Book protection identified |
| Method-of-use patent |
No material active Orange Book protection identified |
| Manufacturing know-how |
Potentially relevant, but generally not visible in the Orange Book |
| Regulatory exclusivity |
Any initial approval-based exclusivity would no longer be the primary commercial barrier |
| Trade secrets |
Possible process and quality-control value, with limited public visibility |
Fosphenytoin is an established molecule. Its commercial defensibility comes from manufacturing consistency, sterile injectable capacity, hospital contracting, and supply reliability rather than patent exclusivity.
When does Sesquient lose exclusivity?
Sesquient’s practical market exclusivity has already expired. The product was approved in 2019, and any conventional three-year exclusivity associated with an NDA relying on new clinical investigations would ordinarily have ended in 2022. There is no apparent long-dated patent expiry that would delay competition into the late 2020s.
The absence of a substantial patent barrier does not guarantee immediate generic substitution. Injectable hospital products can remain commercially concentrated because competitors must obtain FDA approval, qualify sterile manufacturing, establish validated container-closure systems, and secure institutional contracts.
Which companies compete with Sesquient?
Sesquient competes with both fosphenytoin products and therapeutic alternatives. The strongest competitive pressure comes from established suppliers of injectable anticonvulsants and from low-cost phenytoin sodium injection where clinicians and institutions consider the products interchangeable for the relevant use.
Direct and indirect competitors
| Competitor group |
Examples |
Competitive effect |
| Fosphenytoin injection |
Cerebyx and other approved fosphenytoin products |
Direct price and formulary competition |
| Phenytoin sodium injection |
Generic phenytoin sodium products |
Lower-cost substitute, but different administration and tolerability profile |
| Alternative seizure agents |
Levetiracetam, valproate, phenobarbital, benzodiazepines |
Clinical substitution in status epilepticus protocols |
| Hospital-owned purchasing channels |
Group purchasing organizations and integrated systems |
Contract-driven pricing pressure |
| Other injectable manufacturers |
Generic sterile-injectable suppliers |
Potential future supply competition |
Fosphenytoin has advantages over phenytoin in administration speed and local-tissue tolerability. Those advantages support continued use in emergency and perioperative settings. They do not eliminate substitution by levetiracetam or other antiseizure drugs, particularly where hospital protocols prioritize simplified dosing or broader clinical familiarity.
How large is the Sesquient market?
Hikma does not separately report Sesquient sales. The product is included within the company’s broader injectable portfolio, which contains many products with materially larger revenue bases. Product-level revenue cannot be calculated from Hikma’s public financial statements.
Financial visibility
| Metric |
Publicly disclosed for Sesquient? |
| Annual revenue |
No |
| U.S. net sales |
No |
| Prescription volume |
No |
| Average selling price |
No |
| Gross margin |
No |
| Hospital contract share |
No |
| Backlog or purchase commitments |
No |
| Product-specific forecast |
No |
Hikma reported injectable revenue of approximately $1.0 billion in 2022 and more than $1.0 billion in 2023, but those figures cover the entire global injectable portfolio and cannot be allocated reliably to Sesquient. (Hikma Pharmaceuticals PLC, 2024)
Sesquient is likely a small contributor to that segment. Its financial value is more consistent with a niche hospital product that generates recurring demand and portfolio breadth than with a major growth driver.
What drives Sesquient revenue?
Sesquient revenue depends on hospital utilization, competitor availability, emergency-department protocols, contract wins, and supply continuity.
Demand drivers
- Status epilepticus incidence creates recurring emergency demand.
- Neurosurgical procedures support prophylactic and perioperative use.
- Hospitals maintain parenteral seizure-control products for patients unable to take oral medicine.
- Fosphenytoin’s administration profile supports use where rapid intravenous treatment is required.
- Drug shortages can shift purchasing toward available suppliers.
Revenue constraints
- The product treats acute events rather than a chronic maintenance population.
- Hospitals negotiate aggressively on generic injectable pricing.
- Alternative anticonvulsants can replace fosphenytoin in institutional protocols.
- The absence of patent exclusivity limits long-term pricing power.
- Product demand is sensitive to formulary decisions and purchasing contracts.
The resulting revenue profile is likely stable but price-sensitive. Volume can increase during competitor shortages, but shortage-driven gains may reverse when supply normalizes.
How strong is the Sesquient patent estate?
Sesquient has low patent strength and moderate execution-based defensibility.
| Defensibility factor |
Assessment |
| Patent protection |
Low |
| Regulatory exclusivity |
Low at present |
| Clinical differentiation |
Moderate |
| Manufacturing complexity |
Moderate to high |
| Hospital switching friction |
Moderate |
| Brand value |
Limited but relevant for quality and supply |
| Supply-chain value |
High relative to patent value |
| Long-term pricing power |
Low to moderate |
Sterile injectable manufacturing is more difficult to replicate than tablet production. Competitors must manage aseptic processing, particulate control, container integrity, stability data, extractables and leachables, and validated filling operations. These barriers can delay entry even when patents are absent.
They are operational barriers, however, not durable exclusivity rights. A well-capitalized generic injectable manufacturer can overcome them through an FDA-approved manufacturing network and hospital distribution relationships.
Are there Paragraph IV challenges involving Sesquient?
No material public Paragraph IV litigation specific to Sesquient is identified from the product’s publicly visible regulatory and litigation profile. Paragraph IV disputes generally arise when an ANDA applicant certifies that listed patents covering a reference product are invalid, unenforceable or not infringed.
Because Sesquient does not appear to have a significant active Orange Book patent listing, a Paragraph IV challenge is unlikely to be the central competitive mechanism. A future competitor would more likely pursue an ANDA or other applicable FDA pathway without confronting a long-dated Sesquient patent barrier.
The more relevant litigation risks are ordinary product-liability claims, manufacturing disputes, contract litigation, and patent disputes involving competing fosphenytoin or anticonvulsant products.
What litigation affects Sesquient?
No major publicly identified patent litigation appears to threaten continued Sesquient commercialization. The principal legal exposure for the product class is operational:
- Product-liability claims associated with cardiovascular or infusion reactions
- Failure-to-warn allegations
- Dosing and medication-error claims
- Manufacturing or quality-control investigations
- Hospital contract disputes
- Supply interruption claims
These risks are managed through FDA-compliant labeling, controlled administration procedures, pharmacovigilance, and hospital medication protocols. The label’s warnings on infusion rate, cardiovascular monitoring and dosing in phenytoin equivalents are commercially important because they influence institutional risk management. (FDA, 2019)
What generic launch risks exist for Sesquient?
The probability of additional competition is structurally higher than for a patented branded drug. A generic launch could reduce Sesquient pricing and hospital contract share, particularly if the entrant offers:
- A lower acquisition cost
- Multiple vial sizes
- Reliable backorder-free supply
- Preferred group purchasing organization terms
- Compatible distribution through major hospital wholesalers
The timing of entry remains uncertain because FDA approval, manufacturing readiness and contracting can take longer than patent analysis suggests. Sterile injectable markets often experience delayed or limited competition when the number of qualified suppliers is small.
Likely launch scenarios
| Scenario |
Market effect |
| No new approved competitors |
Stable volume with gradual price pressure |
| One reliable entrant |
Moderate price erosion and contract rebidding |
| Multiple entrants |
Strong price compression and lower brand share |
| Competitor shortage |
Temporary Sesquient volume increase |
| Sesquient supply disruption |
Rapid hospital substitution and possible contract loss |
| Greater use of levetiracetam protocols |
Structural volume erosion |
Does Sesquient have biosimilar risk?
No. Biosimilars apply to biological products, while Sesquient is a chemically synthesized small-molecule drug. The relevant risks are generic competition, therapeutic substitution and hospital purchasing pressure.
The main competitive comparison is therefore between fosphenytoin and other anticonvulsants, not between a reference biologic and biosimilars.
Are there licensing deals involving Sesquient?
No major publicly disclosed licensing transaction specific to Sesquient is evident in Hikma’s principal public disclosures. Hikma has built its injectable business through internal development, acquisitions, licensing and portfolio transactions, but the company does not identify a material Sesquient-specific royalty stream or licensing liability in its headline financial reporting.
The lack of a visible licensing burden supports margin retention, but the absence of product-level disclosure prevents a precise estimate of royalties, transfer pricing or contribution profit.
What is the geographic coverage of Sesquient?
Sesquient is primarily a U.S. product. Its commercial opportunity is tied to the U.S. hospital market, FDA approval and U.S. institutional distribution. The product should not be treated as a globally protected asset unless separate approvals, trademarks, patents or commercial rights exist in other jurisdictions.
Geographic expansion would require local regulatory approval, sterile manufacturing compliance, reimbursement access and hospital procurement relationships. These requirements limit the speed at which a U.S.-focused product can become a global revenue contributor.
What is the financial outlook for Sesquient?
Sesquient’s likely financial trajectory is mature and portfolio-driven:
- Revenue should remain supported by recurring emergency and perioperative demand.
- Unit growth is likely limited because the product addresses acute episodes.
- Pricing will remain exposed to generic competition and hospital tenders.
- Temporary upside can arise from competitor shortages.
- Long-term value depends more on supply reliability than on patent extension.
- Sesquient is unlikely to become a major driver of Hikma’s consolidated growth absent a supply disruption affecting competitors or a material increase in clinical use.
For valuation purposes, Sesquient should be modeled as a low-visibility, mature injectable asset. A reasonable commercial framework is stable-to-declining net pricing, relatively low-to-moderate volume growth, and episodic upside from shortages. Product-level revenue should not be estimated from Hikma’s total injectable revenue without external prescription or hospital purchasing data.
Key Takeaways
- Sesquient is Hikma’s U.S. fosphenytoin sodium injection product, approved in 2019 under NDA 209360.
- It is used mainly for status epilepticus, neurosurgery and temporary substitution for oral phenytoin.
- No material active Orange Book patent estate appears to protect Sesquient.
- Any conventional three-year approval-based exclusivity associated with the 2019 approval would generally have ended in 2022.
- The product has no biosimilar risk because it is a small-molecule drug.
- Hikma does not disclose Sesquient-specific revenue, volume, margin or forecasts.
- Commercial defensibility rests on sterile manufacturing, supply reliability and hospital contracts.
- The principal risks are generic competition, therapeutic substitution, price erosion and supply interruption.
- Sesquient is more likely to be a stable niche contributor to Hikma’s injectable segment than a major revenue-growth asset.
FAQs
Is Sesquient the same drug as Cerebyx?
Both contain fosphenytoin sodium and have closely related clinical uses. Cerebyx is the established reference brand, while Sesquient is Hikma’s product marketed under a separate FDA-approved application.
Can hospitals substitute phenytoin sodium for Sesquient?
Hospitals may use phenytoin sodium as a therapeutic alternative, but the products differ in administration characteristics, dosing considerations and safety profiles. Substitution depends on clinical judgment and institutional protocols.
Does Sesquient have a patent expiration date?
No material active Orange Book patent expiration date appears to be the key commercial event for Sesquient. Competition is governed primarily by FDA approval, manufacturing capacity and hospital contracting.
Is Sesquient included in Hikma’s injectable revenue?
Yes, Sesquient is part of Hikma’s broader injectable portfolio, but Hikma does not publicly break out product-level sales.
Could Sesquient sales increase during a drug shortage?
Yes. If competing fosphenytoin or anticonvulsant injectables become unavailable, hospitals may increase purchases of Sesquient. Such gains are usually temporary and depend on Hikma maintaining adequate supply.
References
- Hikma Pharmaceuticals PLC. (2024). Annual report and accounts 2023. https://www.hikma.com
- U.S. Food and Drug Administration. (2019). Sesquient (fosphenytoin sodium) injection prescribing information. https://www.accessdata.fda.gov
- U.S. Food and Drug Administration. (2024a). Orange Book: Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/
- U.S. Food and Drug Administration. (2024b). Drugs@FDA: Sesquient, NDA 209360. https://www.accessdata.fda.gov/scripts/cder/daf/