SELZENTRY Drug Patent Profile
When do Selzentry patents expire, and what generic alternatives are available?
Selzentry is a drug marketed by Viiv Hlthcare and is included in two NDAs.
The generic ingredient in SELZENTRY is maraviroc. There is one drug master file entry for this compound. Nine suppliers are listed for this compound. Additional details are available on the maraviroc profile page.
DrugPatentWatch® Litigation and Generic Entry Outlook for Selzentry
A generic version of SELZENTRY was approved as maraviroc by HETERO LABS LTD III on February 7th, 2022.
AI Deep Research
Questions you can ask:
- What is the 5 year forecast for SELZENTRY?
- What are the global sales for SELZENTRY?
- What is Average Wholesale Price for SELZENTRY?
Summary for SELZENTRY
| US Patents: | 0 |
| Applicants: | 1 |
| NDAs: | 2 |
| Finished Product Suppliers / Packagers: | 2 |
| Raw Ingredient (Bulk) Api Vendors: | 67 |
| Clinical Trials: | 44 |
| Patent Applications: | 7,507 |
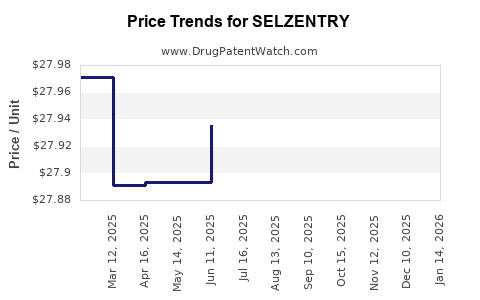
| Drug Prices: | Drug price information for SELZENTRY |
| What excipients (inactive ingredients) are in SELZENTRY? | SELZENTRY excipients list |
| DailyMed Link: | SELZENTRY at DailyMed |
Recent Clinical Trials for SELZENTRY
Identify potential brand extensions & 505(b)(2) entrants
| Sponsor | Phase |
|---|---|
| PolyBio Research Foundation | PHASE2 |
| Icahn School of Medicine at Mount Sinai | PHASE2 |
| Yale University | PHASE2 |
Pharmacology for SELZENTRY
| Drug Class | CCR5 Co-receptor Antagonist |
| Mechanism of Action | Chemokine Co-receptor 5 Antagonists |
US Patents and Regulatory Information for SELZENTRY
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | TE | Type | RLD | RS | Patent No. | Patent Expiration | Product | Substance | Delist Req. | Exclusivity Expiration |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Viiv Hlthcare | SELZENTRY | maraviroc | SOLUTION;ORAL | 208984-001 | Nov 4, 2016 | RX | Yes | Yes | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| Viiv Hlthcare | SELZENTRY | maraviroc | TABLET;ORAL | 022128-001 | Aug 6, 2007 | AB | RX | Yes | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Viiv Hlthcare | SELZENTRY | maraviroc | TABLET;ORAL | 022128-003 | Nov 4, 2016 | DISCN | Yes | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >TE | >Type | >RLD | >RS | >Patent No. | >Patent Expiration | >Product | >Substance | >Delist Req. | >Exclusivity Expiration |
Expired US Patents for SELZENTRY
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | Patent No. | Patent Expiration |
|---|---|---|---|---|---|---|---|
| Viiv Hlthcare | SELZENTRY | maraviroc | TABLET;ORAL | 022128-001 | Aug 6, 2007 | 6,586,430 | ⤷ Start Trial |
| Viiv Hlthcare | SELZENTRY | maraviroc | SOLUTION;ORAL | 208984-001 | Nov 4, 2016 | 6,586,430 | ⤷ Start Trial |
| Viiv Hlthcare | SELZENTRY | maraviroc | TABLET;ORAL | 022128-002 | Aug 6, 2007 | 6,586,430 | ⤷ Start Trial |
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >Patent No. | >Patent Expiration |
EU/EMA Drug Approvals for SELZENTRY
| Company | Drugname | Inn | Product Number / Indication | Status | Generic | Biosimilar | Orphan | Marketing Authorisation | Marketing Refusal |
|---|---|---|---|---|---|---|---|---|---|
| ViiV Healthcare B.V. | Celsentri | maraviroc | EMEA/H/C/000811Celsentri, in combination with other antiretroviral medicinal products, is indicated for treatment experienced adults, adolescents and children of 2 years of age and older and weighing at least 10 kg infected with only CCR5-tropic HIV-1 detectable, | Authorised | no | no | no | 2007-09-18 | |
| >Company | >Drugname | >Inn | >Product Number / Indication | >Status | >Generic | >Biosimilar | >Orphan | >Marketing Authorisation | >Marketing Refusal |
International Patents for SELZENTRY
When does loss-of-exclusivity occur for SELZENTRY?
Based on analysis by DrugPatentWatch, the following patents block generic entry in the countries listed below:
Argentina
Patent: 0159
Patent: COMBINACIONES DE COMPUESTOS DERIVADOS DE TROPANO UTILES EN TERAPIA
Estimated Expiration: ⤷ Start Trial
Generics may enter earlier, or later, based on new patent filings, patent extensions, patent invalidation, early generic licensing, generic entry preferences, and other factors.
See the table below for additional patents covering SELZENTRY around the world.
| Country | Patent Number | Title | Estimated Expiration |
|---|---|---|---|
| African Regional IP Organization (ARIPO) | 1697 | Azabicycloalkanes as CCR5 modulators. | ⤷ Start Trial |
| Argentina | 023345 | COMPUESTOS MODULADORES DE CCR5, COMPOSICIONES, USO, METODO DE EVALUACION DE UN SUPUESTO MUTANTE DEL RETROVIRUS VIH, VIRUS MUTANTE, AGENTE DE DIAGNOSTICO Y PROCEDIMIENTO PARA DESCUBRIR LA PRESENCIA Y/O CONFIRMAR LA ACTIVIDAD DE UN MODULADOR DE QUIMIOCINAS | ⤷ Start Trial |
| Argentina | 023363 | COMPUESTOS DERIVADOS DE 3,3-BIARILPIPERIDINA Y 2,2-BIARILMORFOLINA, COMPOSICION Y USO DE LOS MISMOS | ⤷ Start Trial |
| >Country | >Patent Number | >Title | >Estimated Expiration |
Supplementary Protection Certificates for SELZENTRY
| Patent Number | Supplementary Protection Certificate | SPC Country | SPC Expiration | SPC Description |
|---|---|---|---|---|
| 1284974 | CA 2008 00018 | Denmark | ⤷ Start Trial | PRODUCT NAME: MARAVIROC, EVENTUELT I FORM AF ET FARMACEUTISK ACCEPTABELT SALT |
| 1284974 | 91417 | Luxembourg | ⤷ Start Trial | 91417, EXPIRES: 20220918 |
| 1284974 | PA2008004 | Lithuania | ⤷ Start Trial | PRODUCT NAME: MARAVIROCUM; REGISTRATION NO/DATE: EU/1/07/418/001 - EU/1/07/418/010 20070918 |
| >Patent Number | >Supplementary Protection Certificate | >SPC Country | >SPC Expiration | >SPC Description |
More… ↓
Make Better Decisions: Try a trial or see plans & pricing
Drugs may be covered by multiple patents or regulatory protections. All trademarks and applicant names are the property of their respective owners or licensors. Although great care is taken in the proper and correct provision of this service, thinkBiotech LLC does not accept any responsibility for possible consequences of errors or omissions in the provided data. The data presented herein is for information purposes only. There is no warranty that the data contained herein is error free. We do not provide individual investment advice. This service is not registered with any financial regulatory agency. The information we publish is educational only and based on our opinions plus our models. By using DrugPatentWatch you acknowledge that we do not provide personalized recommendations or advice. thinkBiotech performs no independent verification of facts as provided by public sources nor are attempts made to provide legal or investing advice. Any reliance on data provided herein is done solely at the discretion of the user. Users of this service are advised to seek professional advice and independent confirmation before considering acting on any of the provided information. thinkBiotech LLC reserves the right to amend, extend or withdraw any part or all of the offered service without notice.
ISSN: 2162-2639

Privacy and Cookies
Terms & Conditions
Site Map
DrugPatentWatch Alternatives
LOE / Major Patent Expirations 2026 - 2027
NCE-1 Patent Challenge Dates 2026 - 2027
Friedman, Yali. "DrugPatentWatch" DrugPatentWatch, thinkBiotech, 2026, www.DrugPatentWatch.com.
See Primary Research Papers Citing DrugPatentWatch