Last updated: September 29, 2026
Glucotrol, the branded formulation of glipizide, is a mature sulfonylurea with minimal remaining exclusivity value. Its commercial trajectory is driven by low-cost generic competition, declining use of older diabetes medicines, and continued demand in price-sensitive treatment settings. Pfizer does not disclose standalone Glucotrol revenue, so the product's current financial contribution cannot be isolated from public company filings. The principal commercial value now lies in residual brand prescriptions, supply continuity, and generic manufacturing economics rather than patent-protected pricing.
What is Glucotrol and how is it used?
Glucotrol contains glipizide, an oral sulfonylurea for adults with type 2 diabetes. It stimulates pancreatic beta cells to release insulin and is used with diet and exercise when those measures do not adequately control blood glucose.
Glucotrol is marketed primarily in two dosage forms:
| Product |
Active ingredient |
Dosage form |
FDA approval status |
Current commercial position |
| Glucotrol |
Glipizide |
Immediate-release tablets |
Approved |
Mature branded product |
| Glucotrol XL |
Glipizide |
Extended-release tablets |
Approved |
Mature branded extended-release product |
| Generic glipizide |
Glipizide |
Immediate-release tablets |
Multiple ANDAs approved |
Dominant low-cost alternative |
| Generic glipizide extended-release |
Glipizide |
Extended-release tablets |
Multiple ANDAs approved |
Competes directly with Glucotrol XL |
The FDA approved Glucotrol for type 2 diabetes before the modern wave of incretin-based drugs, sodium-glucose cotransporter-2 inhibitors, and insulin analogs. The label warns about hypoglycemia and states that sulfonylureas are not appropriate for type 1 diabetes or diabetic ketoacidosis (U.S. Food and Drug Administration [FDA], 2023).
How large is the Glucotrol market?
The addressable diabetes population is large, but Glucotrol captures only a small portion of current treatment spending. The United States had approximately 38.4 million people with diabetes in 2021, including diagnosed and undiagnosed cases (Centers for Disease Control and Prevention [CDC], 2024). That population supports continuing demand for inexpensive oral therapies, but the value pool has shifted toward newer drugs with cardiovascular, renal, weight-loss, or hypoglycemia advantages.
Glipizide competes in a low-price segment with:
- Metformin, which remains a common first-line therapy.
- Other sulfonylureas, including glimepiride and glyburide.
- Thiazolidinediones, particularly pioglitazone.
- DPP-4 inhibitors such as sitagliptin and linagliptin.
- GLP-1 receptor agonists such as semaglutide and dulaglutide.
- SGLT2 inhibitors such as empagliflozin and dapagliflozin.
- Basal insulin and other insulin products.
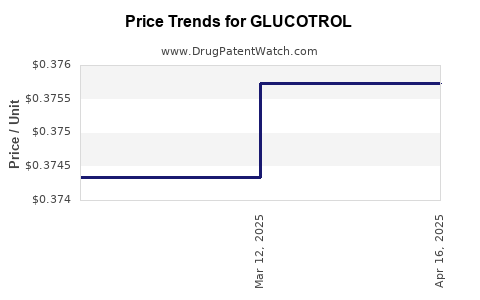
The commercial distinction is clear. Newer agents often command hundreds or thousands of dollars per month before rebates, while generic glipizide is commonly available for a small fraction of that amount. Glucotrol therefore retains demand among patients, health systems, and payers prioritizing acquisition cost, but it has limited pricing power.
What is the financial trajectory of Glucotrol?
Public filings do not provide a standalone Glucotrol or Glucotrol XL revenue line. Pfizer reports revenue by broader product and geographic categories, and legacy products are generally aggregated within established pharmaceutical portfolios. As a result, a precise current revenue figure or product-level growth rate cannot be established from audited public disclosures.
The product's financial trajectory can be summarized as follows:
| Period |
Commercial event |
Financial effect |
| 1970s-1990s |
Branded immediate-release glipizide sales |
Protected or semi-protected brand revenue |
| 2000 |
Glucotrol XL launch |
Temporary lifecycle extension through extended release |
| 2000s |
Generic immediate-release competition |
Rapid price and market-share erosion |
| Late 2000s-2010s |
Generic extended-release competition |
Loss of differentiated pricing for Glucotrol XL |
| 2020s |
Mature generic market and newer diabetes therapies |
Low, declining, or stable niche brand revenue |
The financial model has changed from brand monetization to maintenance economics. Revenue is likely supported by residual brand loyalty, formulary placement in selected channels, and continued prescribing by clinicians familiar with sulfonylureas. Margin pressure comes from generic substitution, pharmacy benefit manager contracting, and limited willingness to pay for branded glipizide.
Pfizer's broader Innovative Health and Established Health portfolios have historically contained many mature products, but the company does not separately report Glucotrol sales in its annual reports. Product-level estimates from commercial databases may differ because they depend on prescription audits, channel assumptions, and whether generic glipizide is included.
When does Glucotrol lose exclusivity?
Glucotrol's original immediate-release exclusivity expired decades ago. The extended-release product also lost meaningful market exclusivity after generic entry. The current commercial issue is therefore not an approaching patent cliff but the long-term effects of an already completed patent cliff.
| Exclusivity category |
Glucotrol status |
| New chemical entity exclusivity |
Expired |
| Immediate-release formulation exclusivity |
Expired |
| Extended-release formulation exclusivity |
Expired or commercially exhausted |
| Pediatric exclusivity |
No material current protection identified |
| Orphan-drug exclusivity |
Not applicable |
| Regulatory exclusivity |
Expired |
| Current branded pricing protection |
Minimal |
Glucotrol's active ingredient, glipizide, has been available generically for many years. Generic competition has eliminated the principal economic benefit that would otherwise arise from the branded product's historical approval.
What patents protect Glucotrol and Glucotrol XL?
The historical patent estate covered glipizide, pharmaceutical compositions, and controlled-release delivery technology. The relevant protection has expired or no longer provides a commercially meaningful barrier to ANDA entry.
The immediate-release product did not retain a viable patent barrier against generic glipizide. Glucotrol XL relied on extended-release formulation technology, but generic manufacturers subsequently obtained approval for extended-release glipizide products.
| Patent category |
Protected subject matter |
Current impact |
| Active ingredient patents |
Glipizide chemical compound |
Expired |
| Immediate-release composition patents |
Tablets containing glipizide |
Expired |
| Extended-release formulation patents |
Controlled delivery of glipizide |
Expired or no longer blocking |
| Manufacturing patents |
Tablet production and release characteristics |
No known current barrier to ordinary generic competition |
| Method-of-use patents |
Treatment of type 2 diabetes |
Limited practical exclusivity after basic use became established |
Current Orange Book protection should be assessed against the specific NDA and formulation. FDA Orange Book entries can change as patents expire, delist, or become irrelevant to approval timing. The commercial record indicates that Glucotrol and Glucotrol XL no longer have patent protection capable of preventing routine generic substitution (FDA, 2024a).
What is the Orange Book status of Glucotrol?
The FDA Orange Book lists approved drug products and, where applicable, patents and exclusivity information. For a mature product such as Glucotrol, the relevant status is the existence of approved reference-listed drugs and multiple therapeutically equivalent generic products.
Glucotrol and Glucotrol XL are reference products for generic glipizide approvals. Their Orange Book significance is regulatory rather than strategic: the listed products define the reference standard against which ANDAs demonstrate pharmaceutical equivalence and bioequivalence.
The presence of generic immediate-release and extended-release products means that an applicant does not need to develop a novel clinical program to enter the market. An ANDA pathway is generally sufficient when the applicant can demonstrate equivalence to the relevant reference product.
Which companies are challenging Glucotrol's market position?
Generic competition is the main challenge. The competitive field has included major generic manufacturers such as:
- Teva Pharmaceuticals.
- Mylan, now part of Viatris.
- Sandoz.
- Dr. Reddy's Laboratories.
- Lupin.
- Zydus Pharmaceuticals.
- Endo or Par Pharmaceutical operations.
- Smaller contract and regional manufacturers.
The exact active supplier set varies by dosage strength, pharmacy channel, shortage conditions, and wholesaler contracts. Generic manufacturer participation can change rapidly because glipizide is a low-margin product with limited differentiation.
Competition is more intense in immediate-release tablets because manufacturing is relatively straightforward. Extended-release glipizide has greater technical requirements involving dissolution control and release kinetics, but those requirements have not prevented multiple generic products from entering the market.
Have there been Paragraph IV challenges to Glucotrol?
Paragraph IV litigation was most relevant when Glucotrol XL patents could have delayed generic entry. A generic applicant may certify that a listed patent is invalid, unenforceable, or not infringed. That certification can trigger litigation and a potential 30-month stay under the Hatch-Waxman framework.
The commercial outcome for Glucotrol is consistent with completed generic entry. Any historic patent disputes did not preserve a durable branded monopoly. Current generic entry risk is therefore based on ordinary ANDA approval, manufacturing economics, and market supply rather than an unresolved branded patent challenge.
No active, high-value Paragraph IV dispute is known to be a material current driver of Glucotrol's market outlook. Patent litigation is not the principal determinant of present revenue.
What litigation and settlement agreements affect Glucotrol?
Glucotrol's current business profile does not depend on a major pending patent case or a settlement that materially delays generic launch. Historic settlements, if any, would have limited relevance because generic glipizide is already established in the market.
Potential legal exposure is more likely to involve:
- Product liability claims related to hypoglycemia.
- Manufacturing or quality-control issues.
- Labeling and pharmacovigilance obligations.
- Contract disputes involving supply or distribution.
- Antitrust scrutiny if a manufacturer attempts to restrict generic access.
These risks are generally less valuable to investors than patent litigation involving a newly launched diabetes product.
What is the FDA regulatory status of Glucotrol?
Glucotrol and Glucotrol XL are FDA-approved prescription medicines for type 2 diabetes. They are not biologics and do not qualify for biosimilar competition. Generic versions are approved through ANDAs, which rely on the reference product's safety and efficacy findings while requiring pharmaceutical equivalence and bioequivalence.
The key regulatory risks are clinical and manufacturing rather than approval exclusivity:
- Hypoglycemia.
- Weight gain.
- Reduced suitability in older adults or patients with irregular food intake.
- Renal or hepatic impairment considerations.
- Medication errors involving immediate-release and extended-release tablets.
- Dissolution and dose-release consistency for extended-release products.
How strong is the Glucotrol patent estate?
The patent estate is weak from a current commercial perspective.
| Strength factor |
Assessment |
| Composition-of-matter protection |
None of material current value |
| Formulation protection |
Expired or bypassed by approved generics |
| Method-of-use protection |
Limited and unlikely to block standard treatment use |
| Manufacturing protection |
No known barrier to routine supply |
| Regulatory exclusivity |
Expired |
| Generic substitution risk |
High |
| Ability to raise price |
Very low |
| Litigation leverage |
Low |
The remaining defensibility comes from manufacturing reliability, distribution, physician familiarity, and brand recognition. Those assets can support a small residual business but cannot recreate the historical value of patent exclusivity.
What generic launch scenarios exist for Glucotrol?
The most likely scenario is continued generic substitution with intermittent supplier changes. Three outcomes are commercially relevant:
| Scenario |
Probability profile |
Market impact |
| Stable generic supply |
Base case |
Brand volume remains small; prices stay low |
| Supplier consolidation or shortage |
Periodic risk |
Temporary price increases or brand substitution |
| Further clinical displacement |
Long-term trend |
Declining use as newer agents gain share |
An abrupt branded re-entry or major price recovery is unlikely without a supply disruption affecting generic manufacturers. The product has no obvious new formulation, indication, or delivery technology that would justify a premium relaunch.
How does Glucotrol compare with newer diabetes drugs?
Glucotrol's advantage is cost. Its disadvantages are hypoglycemia risk, weight gain, and the absence of the cardiovascular, kidney, or weight-loss outcomes associated with several newer classes.
| Attribute |
Glucotrol |
GLP-1 receptor agonists |
SGLT2 inhibitors |
| Drug class |
Sulfonylurea |
Incretin-based therapy |
SGLT2 inhibitor |
| Cost |
Low in generic form |
High |
High |
| Hypoglycemia risk |
Higher when used alone or with insulin |
Lower |
Low |
| Weight effect |
Gain possible |
Loss common |
Modest loss |
| Cardiovascular outcome positioning |
Limited |
Strong for selected agents |
Strong for selected agents |
| Kidney outcome positioning |
Limited |
Increasing |
Strong for selected agents |
| Supply-chain complexity |
Conventional tablets |
Often injectable or specialized oral products |
Conventional tablets |
| Patent value |
Exhausted |
Significant for leading products |
Significant for leading products |
Glucotrol remains relevant where treatment cost is the primary constraint. It is less competitive in formularies that prioritize weight management, cardiovascular risk reduction, or kidney protection.
What geographic markets matter for Glucotrol?
The United States remains important because of the size of its diabetes population and the availability of a branded reference product. International markets are more fragmented. Glipizide use varies with local clinical guidelines, generic pricing, availability of metformin and glimepiride, and national reimbursement policy.
The strongest geographic demand is likely to come from markets where:
- Generic oral diabetes medicines dominate.
- Insulin access is limited or expensive.
- Health systems use low-cost step therapy.
- Sulfonylureas remain embedded in treatment guidelines.
The brand itself has limited international pricing power. Generic glipizide is the more important global commercial product.
What manufacturing and intellectual-property barriers remain?
Manufacturing barriers are moderate for immediate-release tablets and higher for extended-release tablets. Extended-release products require validated dissolution performance, stable excipients, consistent tablet compression, and reliable quality control. These requirements can reduce the number of commercially viable suppliers, but they do not create durable patent exclusivity.
The principal operational risks are:
- Active pharmaceutical ingredient supply disruption.
- Failure to meet dissolution specifications.
- Recalls or manufacturing observations.
- Wholesaler concentration.
- Low-margin economics causing supplier exits.
- Shortages that shift demand temporarily to the brand or alternate generics.
These risks can affect short-term volume and pricing but do not materially strengthen the long-term patent position.
Key Takeaways
- Glucotrol is the branded glipizide product for type 2 diabetes.
- Immediate-release and extended-release patent protection have expired or lost practical commercial force.
- Multiple generic manufacturers compete with Glucotrol and Glucotrol XL.
- Pfizer does not publicly report standalone Glucotrol revenue.
- The product's financial trajectory is mature, low-growth, and exposed to generic substitution.
- Generic glipizide has a cost advantage but lacks the newer clinical benefits associated with GLP-1 receptor agonists and SGLT2 inhibitors.
- No biosimilar pathway applies because glipizide is a small-molecule drug.
- Current value depends on supply reliability, channel access, and residual brand demand rather than exclusivity.
- The main risks are generic price erosion, supplier consolidation, shortages, and continued therapeutic displacement.
FAQs About Glucotrol Market Dynamics
Is Glucotrol still profitable for Pfizer?
Standalone profitability is not publicly disclosed. Given generic competition and the age of the product, Glucotrol is more likely to be a small mature-product contributor than a material Pfizer growth driver.
Can a generic manufacturer still challenge Glucotrol patents?
A manufacturer can file an ANDA with appropriate patent certifications, but Glucotrol's principal patent barriers have already been overcome. Current entry risk is primarily commercial rather than patent-driven.
Is Glucotrol XL more defensible than regular Glucotrol?
Historically, Glucotrol XL had more formulation differentiation. That advantage weakened after generic extended-release glipizide products entered the market. It has no meaningful current exclusivity advantage.
Could Glucotrol prices rise during a generic shortage?
Yes. A shortage can temporarily increase demand for brand supply or alternate generic manufacturers. Such pricing effects would likely be temporary and would not restore durable patent-based pricing power.
Is glipizide likely to disappear from diabetes treatment?
No. Its use may decline as newer therapies expand, but low acquisition cost and broad clinical familiarity support continued use in cost-sensitive treatment settings.
References
-
Centers for Disease Control and Prevention. (2024). National diabetes statistics report: Estimates of diabetes and its burden in the United States. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2023). Glucotrol and Glucotrol XL prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations, 44th edition. FDA.
-
U.S. Food and Drug Administration. (2024b). Drugs@FDA: FDA-approved drugs database. FDA.