Last updated: November 3, 2026
Fentora is Teva Pharmaceutical Industries’ brand of fentanyl buccal tablet, approved in the United States for breakthrough cancer pain in opioid-tolerant adults. Its commercial trajectory has been shaped by three forces: loss of brand exclusivity, intense regulatory controls on transmucosal fentanyl, and declining use of high-risk opioid products. Fentora remains clinically differentiated by its buccal delivery system, but its economic value is primarily generic-market value rather than branded-product value.
What is Fentora and how does it work?
Fentora contains fentanyl citrate and delivers fentanyl through the buccal mucosa. The tablet is placed between the upper cheek and gum, where it dissolves and releases fentanyl for systemic absorption.
| Attribute |
Fentora |
| Active ingredient |
Fentanyl citrate |
| Dosage form |
Buccal tablet |
| Original sponsor |
Cephalon |
| Current principal owner |
Teva Pharmaceutical Industries |
| FDA approval |
September 2006 |
| Primary indication |
Breakthrough cancer pain in opioid-tolerant adults |
| Available strengths |
100, 200, 400, 600, 800 mcg |
| Regulatory category |
Schedule II controlled substance |
| Key risk program |
Transmucosal immediate-release fentanyl REMS |
| Primary competitors |
Generic fentanyl buccal tablets, Actiq, Subsys, Lazanda, Onsolis |
The FDA label limits Fentora to patients already receiving and tolerant to around-the-clock opioid therapy. It is not indicated for acute pain, postoperative pain, headache, or opioid-naive patients. The label also requires individualized titration because the relationship between Fentora dosage and other fentanyl products is not directly interchangeable.[1]
When did Fentora receive FDA approval and lose exclusivity?
Fentora received FDA approval in 2006. The product benefited from the commercial expansion of transmucosal fentanyl for cancer breakthrough pain during the late 2000s, but its exclusivity period ended well before the current market period.
FDA approval history indicates that generic fentanyl buccal tablets entered the U.S. market after the expiration or removal of relevant brand protections. Teva and other manufacturers have marketed generic equivalents, reducing the price and volume opportunity for the branded product.[2]
Fentora exclusivity timeline
| Event |
Timing |
Commercial effect |
| FDA approval |
2006 |
Launch of Fentora in the U.S. |
| Early brand expansion |
2006-2010 |
Growth in specialty oncology and pain channels |
| Safety and misuse scrutiny |
Late 2000s onward |
Tighter prescribing and distribution controls |
| Generic competition |
Mid-to-late 2010s |
Rapid erosion of branded pricing |
| Current market |
2020s |
Primarily generic and controlled specialty demand |
Fentora did not receive the type of durable market protection associated with a new chemical entity still within primary exclusivity. Its commercial decline reflects ordinary small-molecule patent expiry combined with a shrinking risk-adjusted market.
What patents protect Fentora?
Fentora’s historical protection involved patents covering fentanyl delivery through the oral mucosa, dosage forms, and methods for treating breakthrough pain. The relevant intellectual-property position included formulation and delivery claims rather than protection for a new active ingredient. Fentanyl itself is an established opioid compound.
The key patent categories were:
- Buccal delivery technology designed to improve absorption.
- Fentanyl-containing tablet compositions.
- Dosing methods for breakthrough cancer pain.
- Titration and treatment methods for opioid-tolerant patients.
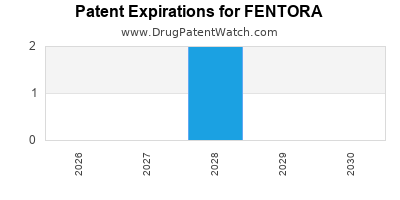
The commercial value of these patents declined as generic manufacturers secured FDA approval and as the Orange Book-listed protections expired or ceased to block abbreviated new drug applications. Current patent exposure should be verified against the live FDA Orange Book because listings, delistings, and expiration calculations can change.[3]
How strong is the Fentora patent estate?
The estate was historically meaningful but is now commercially weak for four reasons:
- The active ingredient is old and broadly available.
- The principal value was concentrated in delivery and formulation claims.
- Generic fentanyl buccal tablets have entered the market.
- A generic applicant can often challenge narrow formulation or method-of-use claims without copying every branded commercial feature.
Fentora’s remaining competitive barriers are more operational than patent-based. They include controlled-substance manufacturing, restricted distribution, pharmacovigilance, opioid REMS obligations, and limited prescriber demand.
What is the Orange Book status of Fentora?
Fentora’s Orange Book relevance is primarily historical. The FDA Orange Book identifies patents and regulatory exclusivities that can affect approval of abbreviated new drug applications. For a product such as Fentora, the commercial question is whether any listed patent remains capable of delaying an ANDA applicant.
The current market indicates that generic fentanyl buccal tablets have obtained FDA approval, which means the original brand protections no longer prevent generic entry. The Orange Book should be treated as the controlling source for current patent listings, expiration dates, and therapeutic-equivalence information.[3]
Fentora also does not have biologic exclusivity. Biosimilar litigation and the Biologics Price Competition and Innovation Act are not relevant because Fentora is a chemically synthesized small-molecule drug.
Which companies are challenging Fentora?
Generic competition has come from manufacturers able to produce fentanyl buccal tablets under the ANDA pathway. Teva has had exposure on both sides of the market: it acquired the original Cephalon brand portfolio while also operating a large generic business.
The main competitive groups are:
- Teva, through the Fentora brand and generic operations.
- Other generic manufacturers with approved fentanyl buccal tablets.
- Alternative transmucosal fentanyl suppliers.
- Compounding or unauthorized channels, which have been regulatory enforcement targets.
Public disclosures do not indicate that Fentora has a current high-value Paragraph IV litigation campaign comparable to major blockbuster products. The principal Paragraph IV risk occurred during the period when generic applicants sought approval before or around the expiration of branded patents. Once generic products entered, litigation ceased to be the primary commercial driver.
What formulation patents protect fentanyl buccal tablets?
Formulation protection is the main technical distinction between Fentora and conventional fentanyl dosage forms. Buccal tablets are designed to provide rapid systemic delivery through the oral mucosa. This creates potential patent claims around:
- Mucoadhesion.
- Drug particle size and dissolution.
- Excipients that promote absorption.
- Tablet structure and placement.
- Dose escalation and titration.
- Bioavailability relative to other fentanyl products.
Those claims can be difficult to enforce broadly because a generic applicant may use a different excipient system or manufacturing process while still demonstrating pharmaceutical equivalence. The FDA’s ANDA framework focuses on sameness of active ingredient, dosage form, strength, route, and bioequivalence, not necessarily identical excipients or manufacturing methods.[4]
What is Fentora’s FDA regulatory status?
Fentora is FDA-approved, but it is subject to an unusually restrictive risk-management environment. Immediate-release transmucosal fentanyl products are covered by a shared REMS designed to reduce accidental exposure, misuse, abuse, addiction, overdose, and death.[5]
The principal regulatory controls include:
- Use only in opioid-tolerant patients.
- Restricted indication for breakthrough cancer pain.
- Prescriber and pharmacy education.
- Controlled dispensing and patient counseling.
- Safe-storage and disposal requirements.
- Warning against conversion from other fentanyl products on a microgram-for-microgram basis.
Regulatory risk is commercially material. A new safety communication, enforcement action, manufacturing observation, or distribution restriction can reduce demand across both brand and generic products.
How has Fentora’s financial trajectory developed?
Fentora’s financial trajectory can be divided into four phases.
1. Launch and specialty growth: 2006-2010
Fentora entered a specialty market with high unit economics. The product addressed a narrow oncology population but carried a premium associated with rapid-onset transmucosal delivery. Brand revenue benefited from specialty pharmacy distribution and limited direct competition within the buccal-tablet segment.
2. Safety and compliance pressure: 2008-2012
Transmucosal fentanyl products faced growing scrutiny because of overdose risk, off-label prescribing, medication errors, and diversion. The FDA required stronger risk controls, and commercial growth became more dependent on compliant oncology prescribing.[5]
3. Generic erosion: approximately 2016 onward
Generic fentanyl buccal tablets reduced branded pricing power. Once an ANDA product became available, payers and specialty pharmacies had a direct substitution option. The product’s revenue mix shifted from branded margin to lower-margin generic volume.
4. Mature controlled-drug market: 2020s
Fentora is now a mature product in a contracting opioid environment. Teva’s public financial reporting groups many products within broader therapeutic and geographic categories, so current standalone Fentora revenue is not separately disclosed in a consistent public series.[6] That prevents a reliable current brand-revenue estimate from company filings.
The financial outlook is therefore based on market structure rather than brand growth:
| Driver |
Direction |
Effect on Fentora economics |
| Generic substitution |
Negative |
Reduces net price and brand share |
| Opioid prescribing controls |
Negative |
Limits eligible patient volume |
| Oncology specialization |
Mixed |
Preserves clinical need but narrows market |
| REMS compliance |
Negative |
Raises operating and distribution cost |
| Manufacturing complexity |
Positive for incumbents |
Creates a modest supply barrier |
| Patent protection |
Limited |
Provides little current pricing support |
| Teva scale |
Positive |
Supports production and distribution efficiency |
What generic entry risks exist for Fentora?
Generic entry risk is high because the product is a mature small-molecule drug with an established FDA pathway. The principal risks are:
- Continued conversion from brand to generic.
- Price compression among generic manufacturers.
- Reduced formulary coverage for the brand.
- Substitution at specialty pharmacies.
- Procurement pressure from hospitals and oncology practices.
- Loss of prescriber familiarity as branded promotion declines.
Supply disruption can temporarily support pricing, but it does not restore durable exclusivity. Any shortage-related benefit is likely to be episodic and dependent on FDA-recognized supply conditions.
How does Fentora compare with competing fentanyl products?
| Product |
Delivery system |
Main commercial distinction |
Current risk |
| Fentora |
Buccal tablet |
Rapid transmucosal delivery |
Generic erosion |
| Actiq |
Oral transmucosal lozenge |
Established fentanyl lozenge format |
Generic and safety pressure |
| Subsys |
Sublingual spray |
Spray-based administration |
Regulatory and legal exposure |
| Lazanda |
Intranasal spray |
Nasal delivery |
Narrow demand and competition |
| Onsolis |
Buccal film |
Film-based buccal delivery |
Limited commercial presence |
| Generic fentanyl buccal tablets |
Buccal tablet |
Lower-cost equivalent |
Price competition |
Fentora’s strongest differentiation is dosage-form familiarity and a defined oncology indication. Its weakness is that those features do not create a substantial barrier once generic buccal tablets are available.
What patent litigation and settlements affect Fentora?
Fentora’s major legal risks historically centered on generic entry, patent validity, infringement, and the commercial conduct associated with transmucosal fentanyl products. The product was also exposed to broader opioid litigation and regulatory scrutiny affecting manufacturers and distributors.
No current, widely reported settlement appears to preserve a meaningful branded monopoly for Fentora. Any historical Paragraph IV agreement should be evaluated based on its entry date, permitted launch terms, authorized-generic provisions, and whether it covered all strengths or only selected dosage forms.
What generic launch scenarios are most likely?
The base case is continued generic availability with low-to-moderate demand and limited brand pricing power.
| Scenario |
Conditions |
Expected outcome |
| Base case |
Multiple generic suppliers, stable FDA approval status |
Ongoing price erosion and mature demand |
| Upside |
Supply disruption or reduced generic participation |
Temporary price improvement |
| Downside |
Additional opioid restrictions or safety action |
Lower volume and greater compliance costs |
| Litigation-driven |
New patent assertion or delisting dispute |
Short-term uncertainty, limited long-term value |
| Manufacturing-driven |
API or controlled-substance production constraints |
Intermittent shortages and share shifts |
What is the commercial value of Fentora today?
Fentora has residual value as a regulated specialty product, but its value is unlikely to come from brand growth. The main assets are:
- An FDA-approved indication.
- Established clinical recognition.
- Existing manufacturing and distribution infrastructure.
- A known buccal delivery platform.
- Potential generic portfolio economics for Teva.
The principal liabilities are opioid-related regulatory exposure, constrained patient eligibility, generic substitution, and limited ability to expand the label without increasing safety risk.
Key Takeaways
- Fentora is a fentanyl citrate buccal tablet approved in 2006 for breakthrough cancer pain in opioid-tolerant adults.
- Its original commercial opportunity was based on rapid transmucosal delivery and specialty oncology pricing.
- Patent protection was centered on buccal formulations, delivery technology, and dosing methods, not the fentanyl molecule.
- Generic fentanyl buccal tablets have materially weakened the branded product’s pricing power.
- Fentora has no biosimilar risk because it is a small-molecule drug.
- The current market is controlled by generic substitution, REMS obligations, opioid prescribing restrictions, and specialty manufacturing requirements.
- Teva’s public filings do not provide a consistent standalone current revenue series for Fentora.
- The product’s remaining value is primarily operational and portfolio-based, not patent-monopoly-based.
FAQs
Is Fentora still commercially available?
Fentanyl buccal tablets remain available through regulated channels, but branded Fentora competes with generic products and may have limited commercial presence depending on country, supplier, and supply status.
Is Fentora interchangeable with Actiq?
No. Fentora and Actiq use different delivery systems and cannot be converted on a simple microgram-for-microgram basis. FDA labeling requires product-specific titration.[1]
Does Fentora have a new chemical entity exclusivity period?
No. Fentanyl is an established active ingredient. Fentora’s historical protection came from formulation, delivery, and method-of-use patents rather than new chemical entity exclusivity.
Can Fentora be used for non-cancer pain?
The FDA-approved indication is breakthrough cancer pain in opioid-tolerant adults. Use for other pain conditions is outside the approved indication and carries substantial safety risk.
Is Teva’s Fentora revenue separately reported?
Teva does not consistently disclose Fentora as a standalone revenue line in its public financial statements. The product is generally assessed through broader product, segment, generic, and specialty-pharmaceutical disclosures.[6]
References
- U.S. Food and Drug Administration. (2023). Fentora: Prescribing information.
- U.S. Food and Drug Administration. (2024). Drugs@FDA: Fentora and fentanyl buccal tablet approval records.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book.
- U.S. Food and Drug Administration. (2019). Abbreviated new drug application submissions: Refuse-to-receive standards.
- U.S. Food and Drug Administration. (2012). Transmucosal immediate-release fentanyl products risk evaluation and mitigation strategy.
- Teva Pharmaceutical Industries Ltd. (2024). Annual report and Form 20-F.