DETROL Drug Patent Profile
✉ Email this page to a colleague
Which patents cover Detrol, and when can generic versions of Detrol launch?
Detrol is a drug marketed by Upjohn and is included in two NDAs.
The generic ingredient in DETROL is tolterodine tartrate. There is one drug master file entry for this compound. Fifteen suppliers are listed for this compound. Additional details are available on the tolterodine tartrate profile page.
DrugPatentWatch® Litigation and Generic Entry Outlook for Detrol
A generic version of DETROL was approved as tolterodine tartrate by IVAX SUB TEVA PHARMS on February 23rd, 2015.
AI Deep Research
Questions you can ask:
- What is the 5 year forecast for DETROL?
- What are the global sales for DETROL?
- What is Average Wholesale Price for DETROL?
Summary for DETROL
| US Patents: | 0 |
| Applicants: | 1 |
| NDAs: | 2 |
| Finished Product Suppliers / Packagers: | 1 |
| Raw Ingredient (Bulk) Api Vendors: | 68 |
| Clinical Trials: | 16 |
| Patent Applications: | 531 |
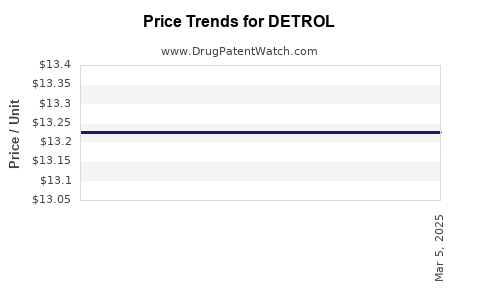
| Drug Prices: | Drug price information for DETROL |
| What excipients (inactive ingredients) are in DETROL? | DETROL excipients list |
| DailyMed Link: | DETROL at DailyMed |
Recent Clinical Trials for DETROL
Identify potential brand extensions & 505(b)(2) entrants
| Sponsor | Phase |
|---|---|
| University of California, San Francisco | Phase 4 |
| Astellas Scientific & Medical Affairs, Inc. | |
| Astellas Pharma Global Development, Inc. | Phase 4 |
Pharmacology for DETROL
| Drug Class | Cholinergic Muscarinic Antagonist |
| Mechanism of Action | Cholinergic Muscarinic Antagonists |
US Patents and Regulatory Information for DETROL
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | TE | Type | RLD | RS | Patent No. | Patent Expiration | Product | Substance | Delist Req. | Exclusivity Expiration |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Upjohn | DETROL | tolterodine tartrate | TABLET;ORAL | 020771-001 | Mar 25, 1998 | AB | RX | Yes | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Upjohn | DETROL LA | tolterodine tartrate | CAPSULE, EXTENDED RELEASE;ORAL | 021228-002 | Dec 22, 2000 | AB | RX | Yes | Yes | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Upjohn | DETROL | tolterodine tartrate | TABLET;ORAL | 020771-002 | Mar 25, 1998 | AB | RX | Yes | Yes | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Upjohn | DETROL LA | tolterodine tartrate | CAPSULE, EXTENDED RELEASE;ORAL | 021228-001 | Dec 22, 2000 | AB | RX | Yes | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >TE | >Type | >RLD | >RS | >Patent No. | >Patent Expiration | >Product | >Substance | >Delist Req. | >Exclusivity Expiration |
International Patents for DETROL
See the table below for patents covering DETROL around the world.
| Country | Patent Number | Title | Estimated Expiration |
|---|---|---|---|
| Austria | 65990 | ⤷ Start Trial | |
| Australia | 2932989 | ⤷ Start Trial | |
| Australia | 635493 | ⤷ Start Trial | |
| Canada | 1340223 | 3,3-DIPHENYLPROPYLAMINES ET LEURS COMPOSITIONS PHARMACEUTIQUES; UTILISATION DANS DES SYSTEMES CHOLINERGIQUES (3,3-DIPHENYLPROPYL AMINES AND PHARMACEUTICAL COMPOSITIONS AND CHOLINERGIC USES THEREOF) | ⤷ Start Trial |
| >Country | >Patent Number | >Title | >Estimated Expiration |
Supplementary Protection Certificates for DETROL
| Patent Number | Supplementary Protection Certificate | SPC Country | SPC Expiration | SPC Description |
|---|---|---|---|---|
| 0325571 | SPC/GB98/027 | United Kingdom | ⤷ Start Trial | PRODUCT NAME: TOLTERODINE OPTIONALLY IN THE FORM OF PHARMACEUTICALLY ACCEPTABLE SALTS THEREOF; REGISTERED: SE 13475 19970905; SE 13476 19970905; UK 00032/0222 19980203; UK 00032/0223 19980203 |
| 0325571 | 1998C0031 | Belgium | ⤷ Start Trial | PRODUCT NAME: TOLTERODINI-L-TARTRAS (=TOLTERODINUM); NATL REGISTRATION NO/DATE: 277 IS 301 F 3 19980309; FIRST REGISTRATION: SE 13475 19970905 |
| 0325571 | C980020 | Netherlands | ⤷ Start Trial | PRODUCT NAME: TOLTERODINE, DESGEWENST IN DE VORM VAN EEN ZOUT MET EEN FYSIOLO GISCH ACCEPTABEL ZUUR, IN HET BIJZONDER TOLTERODINE L-TARTRAAT; NAT. REGISTRATION NO/DATE: RVG 22148, RVG 22149 19980217; FIRST REGISTRATION: SE 13475, 13476 19970905 |
| 0325571 | 21/1998 | Austria | ⤷ Start Trial | PRODUCT NAME: TOLTERODIN, SEINE SALZE, RACEMATE UND ENANTIOMERE; NAT. REGISTRATION NO/DATE: 1-22389 UND 1-22390 19980210; FIRST REGISTRATION: SE 13475 UND 13476 19970905 |
| >Patent Number | >Supplementary Protection Certificate | >SPC Country | >SPC Expiration | >SPC Description |
More… ↓
DrugChatter Q&A for DETROL
Make Better Decisions: Try a trial or see plans & pricing
Drugs may be covered by multiple patents or regulatory protections. All trademarks and applicant names are the property of their respective owners or licensors. Although great care is taken in the proper and correct provision of this service, thinkBiotech LLC does not accept any responsibility for possible consequences of errors or omissions in the provided data. The data presented herein is for information purposes only. There is no warranty that the data contained herein is error free. We do not provide individual investment advice. This service is not registered with any financial regulatory agency. The information we publish is educational only and based on our opinions plus our models. By using DrugPatentWatch you acknowledge that we do not provide personalized recommendations or advice. thinkBiotech performs no independent verification of facts as provided by public sources nor are attempts made to provide legal or investing advice. Any reliance on data provided herein is done solely at the discretion of the user. Users of this service are advised to seek professional advice and independent confirmation before considering acting on any of the provided information. thinkBiotech LLC reserves the right to amend, extend or withdraw any part or all of the offered service without notice.
ISSN: 2162-2639
Privacy and Cookies
Terms & Conditions
Site Map
DrugPatentWatch Alternatives
LOE / Major Patent Expirations 2026 - 2027
NCE-1 Patent Challenge Dates 2026 - 2027
Friedman, Yali. "DrugPatentWatch" DrugPatentWatch, thinkBiotech, 2026, www.DrugPatentWatch.com.
See Primary Research Papers Citing DrugPatentWatch