ASTAGRAF XL Drug Patent Profile
When do Astagraf Xl patents expire, and when can generic versions of Astagraf Xl launch?
Astagraf Xl is a drug marketed by Astellas and is included in one NDA.
The generic ingredient in ASTAGRAF XL is tacrolimus. There is one drug master file entry for this compound. Thirty-six suppliers are listed for this compound. Additional details are available on the tacrolimus profile page.
DrugPatentWatch® Litigation and Generic Entry Outlook for Astagraf Xl
A generic version of ASTAGRAF XL was approved as tacrolimus by SANDOZ on August 10th, 2009.
AI Deep Research
Questions you can ask:
- What is the 5 year forecast for ASTAGRAF XL?
- What are the global sales for ASTAGRAF XL?
- What is Average Wholesale Price for ASTAGRAF XL?
Summary for ASTAGRAF XL
| US Patents: | 0 |
| Applicants: | 1 |
| NDAs: | 1 |
| Finished Product Suppliers / Packagers: | 1 |
| Raw Ingredient (Bulk) Api Vendors: | 80 |
| Clinical Trials: | 10 |
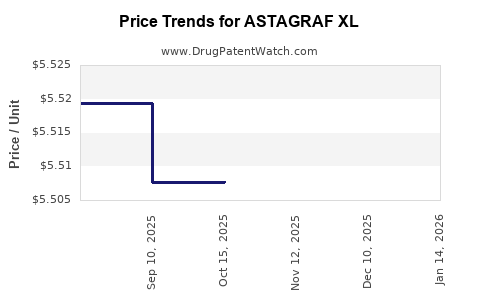
| Drug Prices: | Drug price information for ASTAGRAF XL |
| What excipients (inactive ingredients) are in ASTAGRAF XL? | ASTAGRAF XL excipients list |
| DailyMed Link: | ASTAGRAF XL at DailyMed |
Recent Clinical Trials for ASTAGRAF XL
Identify potential brand extensions & 505(b)(2) entrants
| Sponsor | Phase |
|---|---|
| Shahid Beheshti University of Medical Sciences | NA |
| University of Colorado, Denver | Early Phase 1 |
| Cedars-Sinai Medical Center | Phase 4 |
Pharmacology for ASTAGRAF XL
| Drug Class | Calcineurin Inhibitor Immunosuppressant |
| Mechanism of Action | Calcineurin Inhibitors |
Paragraph IV (Patent) Challenges for ASTAGRAF XL
| Tradename | Dosage | Ingredient | Strength | NDA | ANDAs Submitted | Submissiondate |
|---|---|---|---|---|---|---|
| ASTAGRAF XL | Extended-release Capsules | tacrolimus | 0.5 mg, 1 mg, and 5 mg | 204096 | 1 | 2013-09-24 |
US Patents and Regulatory Information for ASTAGRAF XL
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | TE | Type | RLD | RS | Patent No. | Patent Expiration | Product | Substance | Delist Req. | Exclusivity Expiration |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-001 | Jul 19, 2013 | AB | RX | Yes | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-002 | Jul 19, 2013 | AB | RX | Yes | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-003 | Jul 19, 2013 | AB | RX | Yes | Yes | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | |||
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >TE | >Type | >RLD | >RS | >Patent No. | >Patent Expiration | >Product | >Substance | >Delist Req. | >Exclusivity Expiration |
Expired US Patents for ASTAGRAF XL
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | Patent No. | Patent Expiration |
|---|---|---|---|---|---|---|---|
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-003 | Jul 19, 2013 | 6,576,259 | ⤷ Start Trial |
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-001 | Jul 19, 2013 | 8,551,522 | ⤷ Start Trial |
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-002 | Jul 19, 2013 | 8,551,522 | ⤷ Start Trial |
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-003 | Jul 19, 2013 | 6,884,433 | ⤷ Start Trial |
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-001 | Jul 19, 2013 | 6,440,458 | ⤷ Start Trial |
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-003 | Jul 19, 2013 | 6,440,458 | ⤷ Start Trial |
| Astellas | ASTAGRAF XL | tacrolimus | CAPSULE, EXTENDED RELEASE;ORAL | 204096-002 | Jul 19, 2013 | 6,440,458 | ⤷ Start Trial |
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >Patent No. | >Patent Expiration |
EU/EMA Drug Approvals for ASTAGRAF XL
| Company | Drugname | Inn | Product Number / Indication | Status | Generic | Biosimilar | Orphan | Marketing Authorisation | Marketing Refusal |
|---|---|---|---|---|---|---|---|---|---|
| Astellas Pharma Europe B.V. | Modigraf | tacrolimus | EMEA/H/C/000954Prophylaxis of transplant rejection in adult and paediatric, kidney, liver or heart allograft recipients.Treatment of allograft rejection resistant to treatment with other immunosuppressive medicinal products in adult and paediatric patients. | Authorised | no | no | no | 2009-05-15 | |
| Astellas Pharma Europe BV | Advagraf | tacrolimus | EMEA/H/C/000712Prophylaxis of transplant rejection in adult kidney or liver allograft recipients.Treatment of allograft rejection resistant to treatment with other immunosuppressive medicinal products in adult patients. | Authorised | no | no | no | 2007-04-23 | |
| Chiesi Farmaceutici S.p.A. | Envarsus | tacrolimus | EMEA/H/C/002655Prophylaxis of transplant rejection in adult kidney or liver allograft recipients. Treatment of allograft rejection resistant to treatment with other immunosuppressive medicinal products in adult patients. | Authorised | no | no | no | 2014-07-18 | |
| LEO Pharma A/S | Protopic | tacrolimus | EMEA/H/C/000374Flare treatmentAdults and adolescents (16 years of age and above)Treatment of moderate to severe atopic dermatitis in adults who are not adequately responsive to or are intolerant of conventional therapies such as topical corticosteroids.Children (two years of age and above)Treatment of moderate to severe atopic dermatitis in children (two years of age and above) who failed to respond adequately to conventional therapies such as topical corticosteroids.Maintenance treatmentMaintenance treatment of moderate to severe atopic dermatitis for the prevention of flares and the prolongation of flare-free intervals in patients experiencing a high frequency of disease exacerbations (i.e. occurring four or more times per year) who have had an initial response to a maximum of six weeks treatment of twice daily tacrolimus ointment (lesions cleared, almost cleared or mildly affected). | Authorised | no | no | no | 2002-02-27 | |
| Teva B.V. | Tacforius | tacrolimus | EMEA/H/C/004435Prophylaxis of transplant rejection in adult kidney or liver allograft recipients.Treatment of allograft rejection resistant to treatment with other immunosuppressive medicinal products in adult patients. | Authorised | yes | no | no | 2017-12-08 | |
| Astellas Pharma GmbH | Protopy | tacrolimus | EMEA/H/C/000375Treatment of moderate to severe atopic dermatitis in adults who are not adequately responsive to or are intolerant of conventional therapies such as topical corticosteroids. Treatment of moderate to severe atopic dermatitis in children (2 years of age and above) who failed to respond adequately to conventional therapies such as topical corticosteroids.Maintenance treatment of moderate to severe atopic dermatitis for the prevention of flares and the prolongation of flare-free intervals in patients experiencing a high frequency of disease exacerbations (i.e. occurring 4 or more times per year) who have had an initial response to a maximum of 6 weeks treatment of twice daily tacrolimus ointment (lesions cleared, almost cleared or mildly affected). | Withdrawn | no | no | no | 2002-02-28 | |
| >Company | >Drugname | >Inn | >Product Number / Indication | >Status | >Generic | >Biosimilar | >Orphan | >Marketing Authorisation | >Marketing Refusal |
International Patents for ASTAGRAF XL
See the table below for patents covering ASTAGRAF XL around the world.
| Country | Patent Number | Title | Estimated Expiration |
|---|---|---|---|
| Argentina | 023299 | UNA FORMULACION DE LIBERACION PROLONGADA DE UN COMPUESTO MACRoLIDO | ⤷ Start Trial |
| Austria | 269075 | ⤷ Start Trial | |
| Austria | 464900 | ⤷ Start Trial | |
| Austria | 514419 | ⤷ Start Trial | |
| Australia | 2856399 | ⤷ Start Trial | |
| Australia | 749623 | ⤷ Start Trial | |
| Brazil | 9909201 | ⤷ Start Trial | |
| >Country | >Patent Number | >Title | >Estimated Expiration |
More… ↓
Make Better Decisions: Try a trial or see plans & pricing
Drugs may be covered by multiple patents or regulatory protections. All trademarks and applicant names are the property of their respective owners or licensors. Although great care is taken in the proper and correct provision of this service, thinkBiotech LLC does not accept any responsibility for possible consequences of errors or omissions in the provided data. The data presented herein is for information purposes only. There is no warranty that the data contained herein is error free. We do not provide individual investment advice. This service is not registered with any financial regulatory agency. The information we publish is educational only and based on our opinions plus our models. By using DrugPatentWatch you acknowledge that we do not provide personalized recommendations or advice. thinkBiotech performs no independent verification of facts as provided by public sources nor are attempts made to provide legal or investing advice. Any reliance on data provided herein is done solely at the discretion of the user. Users of this service are advised to seek professional advice and independent confirmation before considering acting on any of the provided information. thinkBiotech LLC reserves the right to amend, extend or withdraw any part or all of the offered service without notice.
ISSN: 2162-2639

Privacy and Cookies
Terms & Conditions
Site Map
DrugPatentWatch Alternatives
LOE / Major Patent Expirations 2026 - 2027
NCE-1 Patent Challenge Dates 2026 - 2027
Friedman, Yali. "DrugPatentWatch" DrugPatentWatch, thinkBiotech, 2026, www.DrugPatentWatch.com.
See Primary Research Papers Citing DrugPatentWatch