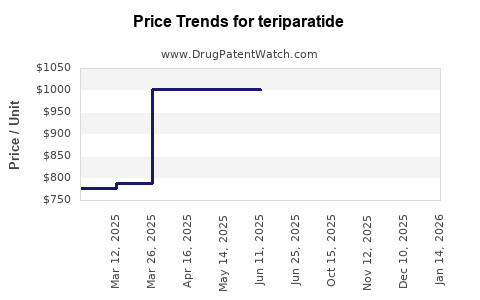
Last updated: September 11, 2026
Teriparatide has moved from a high-value branded osteoporosis product to a mature peptide market exposed to generic and follow-on competition. Eli Lilly’s Forteo remains the reference brand, but US patent expiry, FDA-approved generic teriparatide injections, lower-cost alternatives, and competition from abaloparatide have reduced commercial protection. The market retains value because teriparatide is an anabolic osteoporosis therapy used for patients at high fracture risk, but pricing and market share have shifted toward lower-cost products.
What is teriparatide and how is it used?
Teriparatide is a recombinant form of the first 34 amino acids of human parathyroid hormone, known as PTH 1-34. Intermittent administration stimulates new bone formation and increases bone mineral density.
The main approved use is treatment of osteoporosis in postmenopausal women and men at high risk of fracture. It is also used for osteoporosis associated with sustained systemic glucocorticoid therapy. Teriparatide is administered by subcutaneous injection, traditionally at 20 micrograms once daily. Treatment duration is generally limited to 24 months over a patient’s lifetime under the original US labeling framework, although FDA labeling changes and clinical practice have evolved around risk-benefit assessment.
| Product |
Active ingredient |
Sponsor or manufacturer |
Route |
Regulatory status |
| Forteo |
Teriparatide |
Eli Lilly |
Subcutaneous injection |
Reference product |
| Teriparatide injection |
Teriparatide |
Multiple generic manufacturers |
Subcutaneous injection |
FDA-approved generic products |
| Teriparatide injection delivery devices |
Teriparatide |
Multiple sponsors |
Subcutaneous injection |
Product-specific presentations |
| Tymlos |
Abaloparatide |
Radius Health, now part of Organon |
Subcutaneous injection |
Competing anabolic osteoporosis product |
Teriparatide is a peptide drug rather than a conventional small molecule. US follow-on products have generally entered through abbreviated or hybrid regulatory pathways rather than the classic abbreviated new drug application model used for many small-molecule tablets.
What patents protected Forteo and teriparatide?
The original Forteo patent estate centered on composition, formulation, therapeutic-use, and manufacturing claims. The principal commercial protection has expired or weakened substantially in the United States.
| Patent category |
Protection scope |
Commercial relevance |
| Active peptide composition |
Teriparatide sequence and related peptide claims |
Core protection was vulnerable to expiry and validity challenges |
| Pharmaceutical formulation |
Stable aqueous teriparatide formulations and excipient systems |
Could delay direct substitution where product presentation differed |
| Method of use |
Osteoporosis treatment, fracture-risk reduction, and dosing regimens |
May remain relevant to induced-infringement analysis |
| Delivery device |
Pens, cartridges, and injection systems |
Can protect product presentation after active-ingredient expiry |
| Manufacturing |
Recombinant production, purification, and formulation processes |
May create technical barriers but rarely prevents all market entry |
Historical US Forteo-related patent protection included Lilly patents associated with teriparatide formulations and uses. The key branded-product exclusivity period ended before the 2020s, allowing generic entry and reducing the practical value of remaining secondary patents.
Patent conclusions depend on the specific country, claim scope, prosecution history, terminal disclaimers, pediatric extensions, and Orange Book listing. A single expiration date does not describe the full estate.
When did teriparatide lose exclusivity in the United States?
Forteo’s principal US exclusivity expired in stages rather than on one universal date. The core composition and product protection dates were reached before or around the period when FDA-approved generic teriparatide products began entering the US market.
Lilly’s US Forteo revenue declined as generic competition developed, payer substitution increased, and the product moved into a mature-market lifecycle. The principal commercial inflection point was the period from 2019 through 2022.
US exclusivity timeline
| Period |
Market event |
Effect |
| 2002 |
FDA approves Forteo |
Lilly establishes the reference teriparatide franchise |
| 2009 |
US pediatric exclusivity extension period associated with Forteo protection |
Delays some patent-related expiry consequences |
| 2010s |
Secondary patent and formulation disputes continue |
Preserves portions of product protection but does not prevent eventual competition |
| 2017-2019 |
Core US patent and regulatory protection expires or becomes commercially less restrictive |
Generic-entry risk increases |
| 2019 onward |
FDA-approved generic and follow-on teriparatide products emerge |
Net price and branded share decline |
| 2020s |
Forteo competes in a mature multi-source market |
Revenue contracts from historical peak levels |
Forteo does not have the same commercial exclusivity profile as a newly launched biologic. Teriparatide is not generally treated as a biosimilar market in the way that monoclonal antibodies or insulin analogs may be. FDA-approved teriparatide competitors have entered under product-specific pathways, with interchangeability and substitution determined by the approved label, state pharmacy law, payer policy, and product design.
What is the FDA regulatory status of teriparatide?
FDA has approved Forteo and multiple teriparatide products for osteoporosis-related indications. The regulatory market includes the reference product and products approved through abbreviated or hybrid pathways.
The principal regulatory distinctions are:
- Whether the product is approved as a generic or a 505(b)(2) product.
- Whether the device and delivery system match the reference product.
- Whether the product has the same labeled indications and administration instructions.
- Whether automatic pharmacy substitution is permitted under applicable law.
- Whether the product has clinical or analytical differences that affect payer positioning.
A teriparatide product can compete commercially without being a legally interchangeable product in every jurisdiction. Device differences are important because patients self-administer the drug, and training, adherence, packaging, and pharmacy substitution can affect uptake.
How many patents cover teriparatide and Forteo?
The practical answer depends on the jurisdiction and whether the analysis includes expired, abandoned, granted, pending, or third-party patents. The commercial estate has included multiple patent families rather than a single blocking patent.
For US market analysis, the relevant patent categories include:
- Teriparatide peptide and analog claims.
- Recombinant production and purification.
- Stabilized aqueous formulations.
- Pen, cartridge, and injection-device components.
- Osteoporosis treatment methods.
- Dosing and treatment-sequencing methods.
- Combination and post-teriparatide antiresorptive therapy.
The risk profile is now concentrated in secondary claims. Core active-ingredient protection is no longer the main barrier to US competition. Remaining risks relate to formulation similarity, device copying, method-of-use labeling, and manufacturing-process overlap.
Which companies challenged or compete with Forteo?
The competitive field consists of generic teriparatide manufacturers, branded anabolic competitors, and antiresorptive drugs that compete for the same osteoporosis budget.
Generic and follow-on competitors
US teriparatide competition has included products associated with Teva, Alvogen, and other commercial suppliers. The precise supplier landscape can change because peptide products may be licensed, manufactured, or distributed by different entities over time.
Competition is based on:
- Wholesale acquisition price.
- Payer rebate strategy.
- Product availability.
- Pen or syringe design.
- Pharmacy substitution status.
- Distribution through specialty pharmacies.
- Contracting with Medicare Part D plans.
- Patient-support programs.
Branded therapeutic competitors
| Product |
Company |
Mechanism |
Commercial position |
| Forteo |
Eli Lilly |
PTH 1-34 anabolic agent |
Reference teriparatide brand |
| Tymlos |
Radius Health/Organon |
PTHrP analog |
Direct branded anabolic competitor |
| Evenity |
Amgen/UCB |
Sclerostin inhibitor |
Monthly anabolic-oriented therapy with different risk and administration profile |
| Prolia |
Amgen |
RANKL inhibitor |
Major antiresorptive competitor |
| Reclast |
Novartis |
Bisphosphonate |
Intravenous alternative |
| Fosamax and generic alendronate |
Merck and generics |
Bisphosphonate |
Low-cost first-line alternatives |
Tymlos is the closest branded pharmacologic competitor because it is an anabolic injectable used for patients at high fracture risk. Prolia, Reclast, and oral bisphosphonates compete for prescribing decisions but have different mechanisms, dosing schedules, safety profiles, and treatment positions.
What was Forteo’s financial trajectory?
Forteo generated peak annual sales in the mid-to-late 2010s before declining as exclusivity weakened and competition expanded. Lilly reported worldwide Forteo revenue of roughly $1 billion or more annually during the earlier mature-brand period, followed by sustained contraction in the 2020s.
| Period |
Financial direction |
Main drivers |
| 2014-2017 |
High and relatively stable revenue |
Established use, limited direct competition, strong pricing |
| 2018-2019 |
Early decline |
Patent expiry pressure and expected generic entry |
| 2020-2021 |
Accelerated decline |
Generic competition, payer management, COVID-related treatment disruption |
| 2022-2024 |
Mature-market erosion |
Lower net prices, generic substitution, branded competition, portfolio rationalization |
Public-company reporting does not always separate US and international revenue using identical definitions, and Lilly’s disclosures may present product sales differently across annual reports. The direction is clear: Forteo’s commercial peak has passed, and the product is in the harvest phase of its lifecycle.
Revenue exposure
The financial exposure is concentrated in:
- US branded Forteo price erosion.
- Loss of pharmacy and payer preference.
- Declining patient starts in favor of lower-cost teriparatide.
- Reduced duration of branded therapy.
- International tender and reimbursement pressure.
- Competition from Tymlos and Evenity.
- Lower margins after manufacturing and distribution costs.
Lilly’s broader revenue base reduces the company’s dependence on Forteo. The drug remains commercially relevant but is no longer a major driver of Lilly’s overall valuation compared with newer diabetes, obesity, oncology, and immunology products.
How strong is the teriparatide patent estate?
The estate is commercially weak against direct US active-ingredient competition but remains technically meaningful in selected areas.
Stronger elements
- Device-specific claims that require close copying.
- Formulation claims covering particular stabilizers or concentration ranges.
- Manufacturing claims where the process is difficult to reproduce.
- Method-of-use claims tied to narrow dosing or patient populations.
- Foreign patents with later expiry than corresponding US rights.
Weaker elements
- Broad claims covering teriparatide as a therapeutic peptide.
- Claims that depend on expired priority patents.
- Claims vulnerable to written-description, enablement, obviousness, or anticipation challenges.
- Claims that can be avoided through a different device or formulation.
- Method claims where generic labeling omits the patented indication.
For investors and licensing teams, the estate should be valued as a layered barrier rather than as a single exclusionary right. A generic can avoid infringement through product design, label strategy, manufacturing route, or jurisdictional sequencing.
What formulation patents protect teriparatide?
Formulation patents may cover:
- Peptide stability in aqueous solution.
- Buffer systems.
- Preservatives and tonicity agents.
- Concentration ranges.
- Storage conditions.
- Container-closure systems.
- Pen and cartridge compatibility.
- Reduced aggregation or degradation.
Formulation patents matter because teriparatide is a peptide that can be sensitive to degradation and handling conditions. They can raise development costs and create litigation risk, but they do not necessarily block all competing products. A rival may use a different excipient system, concentration, container, or device.
The highest-value formulation claims are those that are difficult to design around while preserving room-temperature stability, dose accuracy, shelf life, and patient usability.
What method-of-use patents apply to teriparatide?
Method-of-use rights may cover:
- Treatment of postmenopausal osteoporosis.
- Treatment of osteoporosis in men.
- Glucocorticoid-induced osteoporosis.
- Reduction of vertebral or nonvertebral fracture risk.
- Sequential treatment after an antiresorptive.
- Follow-on antiresorptive therapy after teriparatide.
- Treatment duration or cycling schedules.
Method-of-use patents are difficult to enforce against generic products when the generic label omits a patented indication. Litigation risk can arise if marketing, physician promotion, reimbursement coding, or product instructions encourage the patented use.
The commercial value of a method patent depends on whether the protected indication represents a large share of prescriptions and whether a generic can launch with a legally effective skinny label.
What Paragraph IV challenges and litigation affect teriparatide?
Teriparatide litigation has centered on the expected issues for a mature peptide product:
- Whether listed patents are valid.
- Whether the abbreviated product infringes formulation or use claims.
- Whether a generic can launch before patent expiry.
- Whether device differences avoid infringement.
- Whether the generic’s label induces infringement.
- Whether patent listings accurately identify the drug product or method.
Paragraph IV challenges are material because they can accelerate entry before the full expiry date of secondary patents. A first filer may obtain a period of commercial advantage, but that advantage depends on the specific product, regulatory approval, settlement terms, and litigation outcome.
Public information supports a conclusion that teriparatide’s US market has moved beyond the period when patent litigation could preserve broad branded exclusivity. Remaining disputes are more likely to concern specific formulations, devices, or indications than the entire teriparatide market.
Have teriparatide patent settlements affected generic entry?
Settlements in pharmaceutical patent cases can include:
- An agreed generic launch date.
- A license to manufacture or sell before patent expiry.
- Supply arrangements.
- Restrictions on product form or distribution.
- No-challenge provisions.
- Authorized-generic commitments.
- Royalty or milestone payments.
The commercial impact of a settlement depends on whether it permits one entrant or multiple entrants, whether the launch is exclusive, and whether the product is authorized by the brand owner. An authorized generic can reduce the economic value of a first generic launch by limiting price and share gains.
Teriparatide’s market structure indicates that entry economics, manufacturing capability, and payer contracting now matter more than broad patent exclusion.
What generic launch risks exist for teriparatide?
The principal generic-launch risks are regulatory, technical, and commercial.
| Risk |
Impact on launch |
| Peptide characterization |
Requires control of purity, impurities, aggregation, and potency |
| Device development |
Pen or cartridge differences can complicate approval and patient use |
| Formulation stability |
Shelf life and storage conditions affect product viability |
| Manufacturing scale |
Small-volume injectable production can limit supply economics |
| Patent litigation |
Secondary patents may delay or increase launch cost |
| Payer access |
Approval does not guarantee formulary placement |
| Pharmacy substitution |
Product-specific legal status may limit automatic substitution |
| Pricing pressure |
Multiple entrants can rapidly reduce net price |
| Specialty distribution |
Self-injectable products may require focused channel strategy |
Teriparatide is more difficult to commercialize than a conventional generic tablet. The market can therefore support fewer effective suppliers than the number of regulatory approvals suggests.
What biosimilar risk exists for teriparatide?
Traditional biosimilar risk is limited because teriparatide is a peptide and not a monoclonal antibody or other complex biologic of the type commonly analyzed under the US biosimilar pathway.
The relevant competitive risk is follow-on peptide competition. These products can create biosimilar-like commercial effects through:
- Lower prices.
- Payer steering.
- Therapeutic substitution.
- Comparable delivery devices.
- Specialty-pharmacy contracting.
- Increased physician comfort with nonbranded teriparatide.
The absence of a conventional biosimilar designation does not protect Forteo from market erosion. Commercial substitution can occur without formal biosimilar interchangeability.
How does teriparatide compare with Tymlos and Evenity?
| Factor |
Teriparatide/Forteo |
Tymlos |
Evenity |
| Active ingredient |
Teriparatide |
Abaloparatide |
Romosozumab |
| Mechanism |
PTH 1-34 anabolic |
PTHrP analog |
Sclerostin inhibition |
| Administration |
Daily subcutaneous injection |
Daily subcutaneous injection |
Monthly injections by healthcare professional |
| Market maturity |
Mature, generic-exposed |
Branded, competing anabolic |
Branded, newer mechanism |
| Main advantage |
Clinical familiarity and broad history |
Alternative anabolic profile and device |
Less frequent dosing |
| Main constraint |
Generic price erosion and daily dosing |
Brand cost and daily injection |
Cardiovascular risk considerations and office administration |
Teriparatide’s strongest commercial advantages are clinical familiarity, broad physician experience, and established reimbursement pathways. Its main disadvantages are daily administration, mature-brand pricing pressure, and generic competition.
What is the geographic patent and market outlook?
The US market has the most visible generic erosion. Europe, Japan, Canada, and other markets may have different patent histories, reimbursement rules, reference-product naming conventions, and substitution policies.
Geographic differences arise from:
- National patent term calculations.
- Supplementary protection certificates.
- Pediatric extensions.
- Local formulation patents.
- National reimbursement tenders.
- Prescription and substitution rules.
- Local manufacturing requirements.
- Reference-pricing systems.
A company evaluating teriparatide licensing should separate US commercialization rights from international rights. A product with weak US exclusivity can retain value in a market where reimbursement is concentrated, generic penetration is lower, or a local patent remains enforceable.
What manufacturing and intellectual-property barriers remain?
The main barriers are process control and commercial execution rather than broad composition patents.
A viable supplier needs:
- GMP peptide or recombinant manufacturing.
- Consistent impurity control.
- Validated potency assays.
- Stable formulation production.
- Reliable sterile filling.
- Device assembly and quality systems.
- Pharmacovigilance and complaint handling.
- Sufficient volume to meet payer and specialty-pharmacy demand.
Manufacturing IP can retain value where a process delivers higher yield, lower impurity levels, improved stability, or lower cost. Process patents are less likely to exclude all competition if alternative routes are available.
Key Takeaways
- Teriparatide is a mature anabolic osteoporosis market dominated historically by Eli Lilly’s Forteo.
- Core US exclusivity has expired or lost practical force, allowing generic and follow-on competition.
- Remaining patent value is concentrated in formulations, devices, manufacturing processes, and narrow methods of use.
- Forteo revenue has declined materially from its mid-to-late-2010s peak.
- Generic competition creates price and share pressure, but peptide manufacturing and delivery-device requirements limit easy entry.
- Teriparatide is not primarily a conventional biosimilar market; its competitive threat comes from follow-on peptide products and branded anabolic alternatives.
- Tymlos is the closest branded competitor, while Prolia, Evenity, Reclast, and oral bisphosphonates compete for the broader osteoporosis budget.
- Future commercial value depends on payer access, device usability, supply reliability, international reimbursement, and manufacturing economics more than on broad US patent exclusion.
FAQs
Is teriparatide still profitable after generic entry?
Yes, but profitability is lower than during Forteo’s protected-brand period. Margin pressure comes from lower prices, payer substitution, and competition among injectable suppliers.
Can a generic teriparatide product automatically substitute for Forteo?
Not necessarily. Substitution depends on the product’s regulatory designation, device characteristics, state pharmacy law, payer rules, and pharmacy policy.
Is Forteo interchangeable with Tymlos?
No. Tymlos contains abaloparatide, a different active ingredient. The products are therapeutic competitors, not interchangeable versions of the same product.
Does teriparatide require cold-chain distribution?
Product-specific storage requirements apply. Handling depends on the approved formulation, pen or cartridge, and labeling. Storage conditions can affect pharmacy logistics and product wastage.
What is the largest long-term threat to teriparatide revenue?
The largest threat is cumulative price erosion from generic and follow-on products combined with competition from less frequent or more convenient osteoporosis therapies.
References
- Eli Lilly and Company. (2018-2024). Annual reports and Form 10-K filings.
- U.S. Food and Drug Administration. (2002). Forteo prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book.
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drug products.
- U.S. Food and Drug Administration. (2017). Tymlos prescribing information.
- U.S. Food and Drug Administration. (2019). Evenity prescribing information.
- U.S. Food and Drug Administration. (2024). Purple Book: Database of licensed biological products.
- National Osteoporosis Foundation. (2022). Clinician’s guide to prevention and treatment of osteoporosis.
- U.S. Patent and Trademark Office. (2024). Patent Center and patent term adjustment resources.