Share This Page
POVIDONE-IODINE - Generic Drug Details
✉ Email this page to a colleague
What are the generic sources for povidone-iodine and what is the scope of patent protection?
Povidone-iodine
is the generic ingredient in six branded drugs marketed by Alcon Pharms Ltd, Clinipad, Allegiance Hlthcare, and Becton Dickinson, and is included in five NDAs. Additional information is available in the individual branded drug profile pages.One supplier is listed for this compound.
Summary for POVIDONE-IODINE
| US Patents: | 0 |
| Tradenames: | 6 |
| Applicants: | 4 |
| NDAs: | 5 |
| Drug Master File Entries: | 4 |
| Finished Product Suppliers / Packagers: | 1 |
| Raw Ingredient (Bulk) Api Vendors: | 60 |
| Clinical Trials: | 217 |
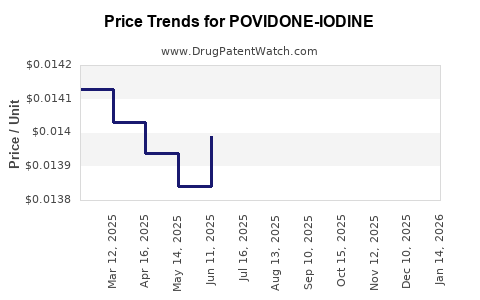
| Drug Prices: | Drug price trends for POVIDONE-IODINE |
| What excipients (inactive ingredients) are in POVIDONE-IODINE? | POVIDONE-IODINE excipients list |
| DailyMed Link: | POVIDONE-IODINE at DailyMed |
Recent Clinical Trials for POVIDONE-IODINE
Identify potential brand extensions & 505(b)(2) entrants
| Sponsor | Phase |
|---|---|
| University of Alabama at Birmingham | PHASE1 |
| Argon Medical Devices | PHASE1 |
| University of Plymouth | EARLY_PHASE1 |
Medical Subject Heading (MeSH) Categories for POVIDONE-IODINE
Anatomical Therapeutic Chemical (ATC) Classes for POVIDONE-IODINE
US Patents and Regulatory Information for POVIDONE-IODINE
| Applicant | Tradename | Generic Name | Dosage | NDA | Approval Date | TE | Type | RLD | RS | Patent No. | Patent Expiration | Product | Substance | Delist Req. | Exclusivity Expiration |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Clinipad | E-Z PREP | povidone-iodine | SOLUTION;TOPICAL | 019382-001 | Jul 25, 1989 | DISCN | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| Clinipad | E-Z PREP | povidone-iodine | SPONGE;TOPICAL | 019382-002 | Jul 25, 1989 | DISCN | No | No | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| Allegiance Hlthcare | POVIDONE IODINE | povidone-iodine | SOLUTION;TOPICAL | 019522-001 | Mar 31, 1989 | OTC | Yes | Yes | ⤷ Start Trial | ⤷ Start Trial | ⤷ Start Trial | ||||
| >Applicant | >Tradename | >Generic Name | >Dosage | >NDA | >Approval Date | >TE | >Type | >RLD | >RS | >Patent No. | >Patent Expiration | >Product | >Substance | >Delist Req. | >Exclusivity Expiration |
Povidone-Iodine Market Dynamics, Patent Exposure, and Financial Trajectory
Povidone-iodine is a mature, low-cost antiseptic with broad use in surgery, wound care, dermatology, dental care, ophthalmology, veterinary medicine, and consumer first-aid products. Its commercial trajectory is driven more by volume, manufacturing cost, regulatory compliance, and brand distribution than by exclusivity. COVID-19 produced a temporary demand spike, but the market has since normalized around hospital procedure volumes, retail first aid, and regional infection-prevention programs.
The active ingredient has no meaningful remaining composition-of-matter patent barrier. Commercial protection generally rests on trademarks, product-specific formulations, packaging, applicators, delivery systems, manufacturing know-how, and regulatory positioning. Orange Book, Paragraph IV, biosimilar, and Hatch-Waxman risks are limited because standard povidone-iodine products are generally nonprescription topical antiseptics rather than innovative prescription drugs.
What is the current market position of povidone-iodine?
Povidone-iodine is a complex of iodine and polyvinylpyrrolidone, commonly sold in concentrations from 5% to 10%. A 10% povidone-iodine solution typically contains approximately 1% available iodine, although the exact available-iodine level depends on the formulation.
| Market characteristic | Assessment |
|---|---|
| Product class | Topical antiseptic and disinfectant |
| Primary uses | Preoperative skin preparation, wound care, first aid, hand and surgical scrubbing |
| Common concentrations | 5%, 7.5%, 10% |
| Major dosage forms | Solutions, scrubs, ointments, swabs, sprays, applicators, ophthalmic preparations |
| Prescription status | Mostly OTC or institutional-use products; product-specific exceptions apply |
| Patent position | Core chemistry is long expired |
| Biosimilar exposure | Not applicable |
| Generic exposure | High for basic solutions and scrubs |
| Commercial differentiation | Brand, formulation, packaging, applicator, supply reliability, regulatory claims |
| Demand profile | Mature, recurring, procedure-sensitive, price competitive |
The market is fragmented by geography and application. Hospital antisepsis generates substantial unit demand but is exposed to procurement tenders and generic substitution. Consumer first-aid products carry higher branding potential but face private-label competition. Specialized ophthalmic, dental, veterinary, and preoperative products can achieve better margins when supported by validated formulations or proprietary delivery systems.
How large is the povidone-iodine market?
Published market-research estimates vary because reports use different definitions. Some include only povidone-iodine antiseptic products, while others include broader iodine disinfectants, hospital skin-preparation systems, or the entire topical antiseptics category. Public-company filings rarely report povidone-iodine revenue as a separate line item.
A defensible market view is that povidone-iodine is a global, multi-billion-dollar product category when hospital, consumer, veterinary, dental, and industrial applications are combined. The pharmaceutical and medical-use segment is smaller than the broad disinfectants market and is characterized by high unit volume and modest average selling prices.
Revenue visibility by segment
| Segment | Revenue quality | Margin profile | Main growth driver |
|---|---|---|---|
| Hospital skin preparation | Recurring but tender-driven | Low to moderate | Surgical procedure volume |
| Surgical scrub | Stable | Low to moderate | Hospital protocols and infection control |
| Consumer first aid | Seasonal and brand-sensitive | Moderate | Retail distribution and brand recognition |
| Wound care | Recurring | Moderate | Chronic wounds, home care, emerging markets |
| Ophthalmic use | Smaller but specialized | Moderate to high | Procedure growth and validated formulations |
| Dental and oral care | Niche | Moderate | Dental procedure volume |
| Veterinary use | Fragmented | Moderate | Companion-animal and livestock care |
| Industrial and aquaculture use | Cyclical | Low to moderate | Water treatment, hatcheries, and production activity |
The largest near-term financial variable is not innovation but procurement economics. Buyers can often switch among equivalent 5% or 10% products if the supplier maintains required quality, packaging, sterility, and documentation.
What drove the financial trajectory of povidone-iodine?
Pre-COVID period
Before 2020, povidone-iodine demand was relatively stable. Hospital consumption tracked operating-room volumes, outpatient procedures, wound-care activity, and infection-control protocols. Consumer demand was tied to first aid and household antiseptic use.
Growth was generally incremental rather than technology-driven. The category faced price pressure from chlorhexidine, alcohol-based preparations, hydrogen peroxide, hypochlorous acid products, and private-label alternatives.
COVID-19 demand shock
COVID-19 created a short-lived increase in demand for disinfectants and antiseptic products. Povidone-iodine benefited from consumer stockpiling, institutional procurement, and laboratory research into antiviral activity. In vitro studies reported activity against several viruses, including SARS-CoV-2, but laboratory findings did not automatically support new clinical or consumer claims.[1]
The demand surge produced several commercial effects:
- Higher short-term volumes for active ingredient and finished products.
- Temporary shortages and allocation pressure.
- Greater visibility for Betadine and other established brands.
- New product launches in sprays, wipes, gargles, and nasal formulations.
- Regulatory scrutiny of unsupported COVID-19 prevention or treatment claims.
The financial effect was a volume spike rather than a durable structural repricing. As household inventories normalized and pandemic procurement declined, demand returned toward surgical, wound-care, and consumer baseline levels.
Post-pandemic normalization
The current trajectory is characterized by moderate underlying growth with periodic supply and procedure fluctuations. Surgical backlogs supported procedure-related demand after the acute pandemic period, while hospitals continued to emphasize infection prevention. Consumer growth is more constrained because basic povidone-iodine solutions are easy to substitute and difficult to differentiate.
The strongest commercial opportunities are in products that combine povidone-iodine with:
- Validated applicator systems.
- Sterile single-use packaging.
- Low-irritation or reduced-staining formulations.
- Ophthalmic or dental delivery formats.
- Procedure-specific kits.
- Hospital workflow integration.
- Regional regulatory approvals and distribution.
Which companies compete in povidone-iodine?
Competition exists at several levels: branded finished products, hospital generic suppliers, active-ingredient manufacturers, private-label producers, and medical-device companies that incorporate antiseptic products into procedure kits.
Key commercial brands and suppliers
Betadine is the best-known global consumer and institutional brand, although ownership, marketing, and distribution arrangements vary by jurisdiction. In the United States, Betadine-branded products are associated with Avrio Health, while other markets have separate licensees, distributors, or local commercial arrangements.
Other competition comes from:
- Generic hospital suppliers.
- Private-label retail manufacturers.
- Contract manufacturers producing antiseptic solutions and scrubs.
- Companies selling preoperative skin-preparation kits.
- Suppliers of pharmaceutical-grade povidone-iodine raw material.
- Manufacturers of ophthalmic, dental, veterinary, and aquaculture products.
Public filings from diversified healthcare companies generally do not isolate povidone-iodine revenue. Revenue exposure is therefore most visible through category-level disclosures, hospital-procedure trends, and brand or product-line performance rather than through a standalone financial statement line.
What is the FDA regulatory status of povidone-iodine?
FDA treatment depends on the product’s indication, concentration, dosage form, claims, and intended use. Povidone-iodine should not be treated as having one uniform regulatory status across all products.
Consumer topical antiseptics
FDA has regulated topical antiseptic products through OTC monograph and rulemaking frameworks. The agency has separated consumer antiseptic washes, consumer antiseptic rubs, health-care antiseptic products, and other topical antiseptic categories. Products must comply with the applicable monograph, final rule, approved application, or enforcement position for the claims they make.[2]
A product marketed for general first aid is regulated differently from a product claiming surgical skin preparation, nasal decolonization, oral antiviral activity, or prevention of a specific infection.
Hospital products
Hospital-use products can carry different regulatory and labeling requirements based on whether they are used as a patient antiseptic, surgical scrub, skin preparation, or component of a kit. Sterility, manufacturing controls, labeling, and applicator design can affect regulatory treatment and procurement eligibility.
Ophthalmic products
Ophthalmic povidone-iodine products face stricter requirements because they are applied to or around the eye. The commercial barrier is higher than for standard external-use solutions. Sterility, excipients, container closure, preservative systems, and ocular tolerability become important differentiators.
COVID-related claims
Povidone-iodine products cannot rely on laboratory antiviral data alone to claim prevention or treatment of COVID-19. FDA has taken enforcement action against unapproved products making disease-treatment or prevention claims, including claims involving COVID-19.[3]
What patents protect povidone-iodine products?
The basic povidone-iodine active ingredient is mature. Core patents covering the complex and its broad antiseptic use expired many years ago. Standard 5% and 10% solutions therefore face substantial generic and private-label competition.
The relevant patent categories are product-specific.
| Patent category | Commercial relevance | Expected durability |
|---|---|---|
| Core povidone-iodine composition | Low for new entrants | Expired or commercially obsolete |
| Standard antiseptic solution | Low to moderate | Usually limited |
| Low-irritation formulations | Moderate | Product-specific |
| Ophthalmic formulations | Moderate to high | Depends on formulation and claims |
| Nasal or oral delivery | Moderate | Claim and regulatory dependent |
| Single-use applicators | Moderate | Often device-focused |
| Procedure kits | Moderate | Combination and packaging claims |
| Manufacturing processes | Moderate | Can protect yield, purity, or stability |
| Trademarks | High for branded products | Renewable indefinitely |
| Trade secrets | Variable | Potentially durable if controlled |
Patent strength is generally weak for commodity solutions and stronger for specialized products that combine formulation, packaging, sterility, and a defined clinical use.
Formulation patents
Formulation patents may cover:
- Available-iodine concentration.
- Buffer systems.
- Surfactants and wetting agents.
- Osmolality and pH.
- Reduced staining.
- Improved stability.
- Reduced irritation.
- Ocular tolerability.
- Compatibility with applicator materials.
- Extended shelf life.
A formulation patent has greater commercial value when the claimed composition is necessary to meet a validated product specification. A narrow formulation claim with easy design-around options provides less protection than a claim linked to a proprietary delivery system or clinical indication.
Manufacturing and process protection
Manufacturing know-how can be more important than patents. Control of iodine availability, polymer characteristics, impurity levels, stability, color, viscosity, and packaging compatibility affects product quality. A supplier with consistent pharmaceutical-grade production can retain customers despite the absence of strong composition patents.
What is the Orange Book status of povidone-iodine?
Standard OTC povidone-iodine products generally do not have a conventional Orange Book patent profile comparable to branded prescription drugs. The Orange Book primarily supports approved drug products, therapeutic-equivalence evaluations, and patent or exclusivity information for eligible applications.[4]
The practical implications are:
- No universal Orange Book-listed patent estate for povidone-iodine.
- No standard Hatch-Waxman exclusivity timetable for commodity OTC solutions.
- Paragraph IV challenges are generally not the central entry mechanism.
- Patent risk depends on the specific branded product and its approved or marketed formulation.
- An NDA-approved specialty product could create a different regulatory profile from an ordinary OTC antiseptic.
A buyer or competitor must evaluate the exact product rather than assume that all povidone-iodine products have identical regulatory or patent status.
When does povidone-iodine lose exclusivity?
Povidone-iodine has already lost practical exclusivity for its core antiseptic use. There is no single future loss-of-exclusivity date.
Exclusivity timeline
| Period | Event | Commercial effect |
|---|---|---|
| Historic development period | Povidone-iodine complex and antiseptic use commercialized | Establishment of the category |
| Pre-2000s | Core composition and broad-use patent protection expired | Generic competition expanded |
| 2010s | Greater specialization in applicators, kits, ophthalmic products, and formulations | Product-level differentiation increased |
| 2020-2021 | COVID-related demand and product claims expanded | Temporary volume and visibility increase |
| 2022 onward | Demand normalized | Competition returned to price, supply, and distribution |
| Current market | No core exclusivity | Specialty product claims and trademarks remain relevant |
Which companies are challenging povidone-iodine products?
The main challengers are not usually named Paragraph IV filers. They are generic manufacturers, private-label suppliers, contract manufacturers, and alternative antiseptic providers.
Competitive pressure comes from:
- Generic povidone-iodine solutions and scrubs.
- Chlorhexidine-based preoperative products.
- Alcohol-only skin preparations.
- Hydrogen peroxide and hypochlorous acid products.
- Silver-containing wound-care products.
- Specialty nasal, oral, or ophthalmic antiseptics.
- Hospital-owned or distributor-owned private labels.
Chlorhexidine is the most important clinical and procurement substitute in surgical skin preparation. Selection depends on procedure type, body site, residual activity, allergy risk, neonatal restrictions, mucosal use, and hospital protocol. Povidone-iodine remains relevant where broad-spectrum activity, cost, availability, or use on sensitive sites supports its selection.
What patent litigation affects povidone-iodine?
Povidone-iodine is not generally associated with major, category-wide patent litigation. Litigation risk is more likely to arise from:
- Proprietary applicator designs.
- Combination kits.
- Ophthalmic products.
- Nasal or oral formulations.
- Device-plus-drug systems.
- Trade dress and trademark disputes.
- Contract manufacturing and supply agreements.
- Regulatory claims and false-advertising disputes.
Because the active ingredient is old, a litigation strategy based only on the chemical identity of povidone-iodine is weak. Stronger cases typically depend on a narrow formulation, a defined method of use, a delivery device, or brand confusion.
Are licensing deals important in the povidone-iodine market?
Licensing is more relevant to brands and distribution than to the active ingredient. Regional licensing, contract manufacturing, and private-label agreements can determine market access, particularly for Betadine and other established brands.
The most commercially significant agreement types include:
- Trademark licenses.
- Regional marketing rights.
- Hospital-distribution agreements.
- Co-manufacturing arrangements.
- Supply contracts for pharmaceutical-grade povidone-iodine.
- Combination-kit partnerships.
- Device and applicator licenses.
Because public companies typically aggregate antiseptic sales into larger business units, deal economics are rarely disclosed at the individual-product level.
What geographic markets offer the strongest growth?
Emerging markets offer the highest unit-growth potential because of population growth, expanding hospital infrastructure, increasing surgical access, and low-cost wound-care demand. Developed markets remain important for high-value institutional procurement, branded retail products, and specialized formulations.
| Region | Market characteristics |
|---|---|
| North America | Mature, regulated, brand and hospital tender competition |
| Europe | Mature, fragmented by national procurement and medical-device rules |
| Japan and South Korea | High quality and packaging standards; specialized demand |
| China | Large manufacturing base and domestic hospital demand |
| India | Strong low-cost production and export potential |
| Southeast Asia | Expanding healthcare access and consumer demand |
| Latin America | Retail and hospital growth with currency and tender exposure |
| Middle East and Africa | Import dependence in some markets; public-health and hospital demand |
Geographic expansion is constrained by local registration, claims restrictions, GMP requirements, labeling language, import controls, and procurement qualification.
What generic launch risks exist for povidone-iodine?
Generic entry risk is high for standard products and lower for specialized systems.
High-risk products
- 10% external solutions.
- 7.5% surgical scrubs.
- Standard ointments.
- Basic swabs and bottles.
- Nonsterile consumer first-aid products.
Moderate-risk products
- Sterile single-use applicators.
- Procedure kits.
- Low-irritation formulations.
- Products with specialized packaging.
- Hospital products requiring validated supply chains.
Lower-risk or more defensible products
- Ophthalmic products.
- Formulations with difficult stability requirements.
- Products supported by proprietary devices.
- Products protected by trademarks and strong distribution.
- Products integrated into hospital protocols or bundled procedure systems.
For a new entrant, manufacturing cost and regulatory execution are usually more important than patent clearance. For an incumbent, the principal risks are price erosion, supply disruption, loss of hospital contracts, and substitution by chlorhexidine or alcohol-based products.
How strong is the povidone-iodine patent estate?
The overall patent estate is weak for commodity povidone-iodine and moderate for specialized delivery and formulation products.
| Estate component | Strength | Reason |
|---|---|---|
| Core active ingredient | Weak | Mature chemistry and expired broad protection |
| Standard solution | Weak | Easy substitution and generic manufacture |
| Branded consumer product | Moderate | Trademark, packaging, distribution |
| Surgical applicator | Moderate | Device claims may create barriers |
| Ophthalmic formulation | Moderate to strong | Higher regulatory and formulation complexity |
| Manufacturing process | Moderate | Trade secrets and process consistency matter |
| Method-of-use claims | Variable | Dependent on clinical evidence and claim scope |
| Combination kits | Moderate | Packaging and workflow integration can deter copying |
What is the financial outlook for povidone-iodine?
The base case is steady, low-to-moderate market growth with periodic volume volatility. Revenue expansion is likely to come from healthcare utilization, emerging-market penetration, specialty delivery formats, and premium institutional products rather than from higher prices for bulk solution.
Base-case financial trajectory
- Unit demand remains tied to surgical and wound-care volumes.
- Pandemic-related excess demand does not return as a permanent baseline.
- Commodity pricing remains competitive.
- Specialty products support better gross margins.
- Raw-material and packaging costs affect profitability.
- Hospital tenders limit pricing power.
- Retail brands retain a premium where consumer recognition is strong.
- Supply reliability is a commercial differentiator.
Upside factors
- Increased global surgical access.
- Growth in outpatient procedures.
- Expanded use in chronic wound care.
- Premium sterile applicators.
- Specialty ophthalmic and dental products.
- Stronger distribution in emerging markets.
- Hospital preference for broad-spectrum, low-cost antiseptics.
Downside factors
- Chlorhexidine substitution.
- Alcohol-based skin-preparation adoption.
- Procurement-driven price erosion.
- Regulatory restrictions on unsupported claims.
- Raw-material shortages.
- Reduced consumer stockpiling.
- Product recalls or contamination events.
- Weak differentiation among private-label products.
Key Takeaways
- Povidone-iodine is a mature antiseptic category with no meaningful core composition patent barrier.
- Standard solutions and scrubs face high generic and private-label competition.
- The COVID-19 demand surge was temporary and has largely normalized.
- Financial performance depends on surgical volumes, retail distribution, hospital tenders, and manufacturing efficiency.
- Specialty formulations, sterile applicators, ophthalmic products, and procedure kits offer stronger margins and more defensible positions.
- Orange Book and Paragraph IV analysis is usually limited for standard OTC products.
- Biosimilar risk does not apply because povidone-iodine is a small-molecule antiseptic, not a biologic.
- Brand trademarks, regulatory approvals, supply reliability, and hospital contracts are more important than core drug patents.
- Chlorhexidine and alcohol-based products are the principal competitive substitutes in surgical antisepsis.
- The strongest growth opportunity is in emerging healthcare markets and specialized delivery formats.
FAQs
Is povidone-iodine still commercially attractive for pharmaceutical manufacturers?
Yes, but mainly when the product has distribution scale, reliable supply, specialized packaging, or a regulated formulation. Commodity solutions have limited pricing power.
Can a company obtain new patents on povidone-iodine?
A company can seek patents on new formulations, delivery systems, manufacturing processes, combination products, and specific methods of use. A new broad patent on the basic antiseptic chemistry is unlikely to provide meaningful protection.
Does Betadine have market exclusivity?
Betadine has brand and trademark protection, not broad exclusivity over povidone-iodine. Competing manufacturers can sell equivalent products subject to applicable regulatory and labeling requirements.
Is povidone-iodine preferred over chlorhexidine?
The answer depends on the procedure, body site, patient population, and institutional protocol. Chlorhexidine often has an advantage in residual skin activity, while povidone-iodine remains important for broad use, cost, availability, and applications where chlorhexidine is unsuitable.
Can povidone-iodine products make antiviral or COVID-19 prevention claims?
Only where the claims are supported and permitted under the applicable FDA or local regulatory pathway. In vitro antiviral activity does not by itself authorize disease-prevention or treatment claims.
References
-
Eggers, M. (2019). Infectious disease management and control with povidone iodine. Journal of Hospital Infection, 102(4), 403-409. https://doi.org/10.1016/j.jhin.2019.01.009
-
U.S. Food and Drug Administration. (1994). Tentative final monograph for OTC health care antiseptic drug products. Federal Register, 59 Fed. Reg. 31402.
-
U.S. Food and Drug Administration. (2020). Warning letters and enforcement actions related to products making COVID-19 claims. FDA.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
Kenvue Inc. (2024). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934. U.S. Securities and Exchange Commission.
-
Biggar, R. J., and Håkanen, A. (2020). Povidone-iodine and infection prevention in clinical settings. Clinical Microbiology Reviews, 33(4), e00037-20.
More… ↓
