Last updated: September 8, 2026
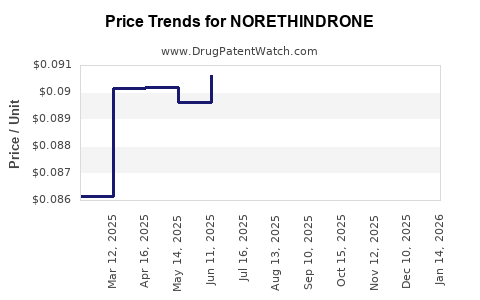
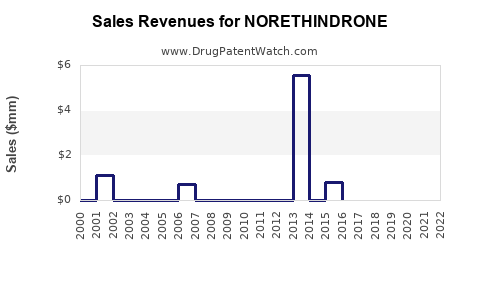
Norethindrone is a mature, predominantly generic progestin market with low molecule-level patent protection, limited pricing power, and fragmented commercial demand. Revenue is distributed across low-cost oral contraceptives, norethindrone acetate products for abnormal uterine bleeding and endometriosis, and fixed-dose hormone-replacement products. Public companies generally do not report norethindrone sales separately, so market value and company-level revenue cannot be established from audited filings alone.
What is norethindrone and which products contain it?
Norethindrone is a synthetic progestin marketed as a standalone active ingredient and as norethindrone acetate. The two names are related but should not be treated as interchangeable for regulatory, patent, or commercial analysis.
| Product category |
Active ingredient |
Typical use |
U.S. commercial status |
| Progestin-only oral contraceptive |
Norethindrone 0.35 mg |
Contraception |
Generic and branded products |
| Menstrual-disorder therapy |
Norethindrone acetate, commonly 5 mg |
Abnormal uterine bleeding, amenorrhea, endometriosis |
Generic |
| Menopausal hormone therapy |
Norethindrone acetate plus ethinyl estradiol |
Vasomotor symptoms and prevention of postmenopausal osteoporosis |
Generic and branded products |
| Combination contraceptives |
Norethindrone or norethindrone acetate plus ethinyl estradiol |
Contraception |
Multiple generic and branded products |
| Other fixed-dose products |
Norethindrone acetate plus estrogen |
Menopausal symptoms |
Generic products |
Norethindrone products are regulated prescription medicines in the United States. The FDA has approved multiple immediate-release oral dosage forms, but approval status varies by strength, combination, manufacturer and indication.[1]
How large is the norethindrone market?
There is no single reliable global market figure for norethindrone because commercial reporting divides the market by product, indication and formulation. Norethindrone is also included in broader categories such as oral contraceptives, progestins, hormone-replacement therapy and women’s health generics.
The market has five structural characteristics:
- High generic penetration.
- Low average selling prices for standalone products.
- Large prescription volumes relative to product value.
- Product-level competition among multiple abbreviated new drug application holders.
- Limited public disclosure of norethindrone-specific revenue.
The largest volume pool is likely the progestin-only contraceptive segment, which includes the 0.35 mg tablet historically marketed as Ortho Micronor and later under generic labels. Norethindrone acetate 5 mg has a smaller patient population but can command higher unit prices because it is prescribed for treatment rather than routine contraception.
Combination hormone products create a separate commercial pool. They compete with levonorgestrel, medroxyprogesterone acetate, drospirenone and micronized progesterone products. Their market position depends on indication, estrogen component, tolerability, payer coverage and prescriber preference.
What is the financial trajectory for norethindrone?
The financial trajectory is mature-to-declining at the molecule level, with periodic price increases or shortages creating temporary revenue changes for individual suppliers.
Revenue profile
Norethindrone has several characteristics associated with low long-term pharmaceutical revenue:
- The underlying active ingredient is old and widely known.
- Core products are available from multiple generic manufacturers.
- Most formulations use conventional oral tablets.
- Manufacturing technology is established.
- Regulatory exclusivity has expired for the principal legacy products.
- No single supplier controls the full norethindrone market.
Norethindrone revenue is therefore driven more by unit volume, contract awards, pharmacy-channel access and supply reliability than by innovation-based pricing.
Public disclosures from generic manufacturers generally aggregate sales into broader categories. Companies such as Amneal Pharmaceuticals, Teva Pharmaceutical Industries, Viatris and Lupin may report women’s-health or U.S. generics performance, but they do not generally disclose norethindrone revenue as a separate product line in annual reports.[2-5]
Likely revenue direction
| Period |
Market condition |
Financial effect |
| Early branded period |
Limited competition and product differentiation |
Higher unit economics |
| Generic-entry period |
Multiple ANDA approvals and price competition |
Rapid price erosion |
| Mature generic period |
Stable demand and low prices |
Volume-driven revenue |
| Shortage or supplier exit period |
Reduced supply and temporary price increases |
Volatile manufacturer revenue |
| Current long-term profile |
Established generic demand and little molecule-level innovation |
Flat-to-declining nominal revenue |
Manufacturer profitability can diverge from market revenue. A supplier with a reliable active pharmaceutical ingredient source, strong retail contracts or limited competition in a particular strength may earn attractive margins even while the overall molecule remains commoditized.
When did norethindrone lose exclusivity?
Norethindrone lost meaningful molecule-level exclusivity decades ago. The principal commercial products were introduced in the 1960s and 1970s, well before the current generic-drug market structure.[6]
The relevant commercial distinction is between:
- Active-ingredient exclusivity, which has expired.
- Product-specific patents, which have largely expired for legacy products.
- Formulation patents, which may apply to newer combinations or delivery technologies.
- Method-of-use patents, which may cover a specific indication or dosing regimen.
- Regulatory exclusivity, which is not a meaningful barrier for the long-established products.
Generic competition is therefore the central market force. Any remaining intellectual-property value is more likely to arise from a particular combination, dosage form, manufacturing process or delivery system than from norethindrone itself.
What patents protect norethindrone products?
The core norethindrone molecule is not commercially protected by a current composition-of-matter patent. Patent analysis must be conducted at the product level.
Potentially relevant patent categories include:
| Patent category |
Relevance to norethindrone |
| Composition of matter |
No meaningful current protection for the legacy active ingredient |
| Salt or ester |
Historically relevant to norethindrone acetate, but legacy protection has expired |
| Combination product |
May cover a specific estrogen-progestin combination |
| Formulation |
Could cover release profile, excipients or dosage form |
| Method of use |
Could cover a defined menopausal, contraceptive or gynecologic use |
| Manufacturing process |
May protect a particular synthesis, purification or crystallization process |
| Device or packaging |
Relevant only where the product uses a specialized delivery or dispensing system |
Norethindrone tablets are conventional oral products. That limits the commercial value of formulation patents unless they provide a meaningful clinical or regulatory advantage.
What is the Orange Book status of norethindrone?
The FDA Orange Book lists approved drug products and certain patent and exclusivity information at the product level. Norethindrone and norethindrone acetate products appear through multiple approved applications, strengths and combinations rather than through one unified listing.[7]
For an Orange Book assessment, the relevant questions are:
- Which reference listed drug is being evaluated?
- Is the product norethindrone or norethindrone acetate?
- Is it a standalone product or a combination?
- Does the listing contain active patents?
- Are any listed patents directed to the approved indication, formulation or method of use?
- Which ANDA applicants have filed Paragraph IV certifications?
Legacy standalone products generally present a low patent barrier. Combination products can have a more complex listing history because patent claims may relate to the estrogen component, treatment indication, formulation or dosing schedule.
Are there Paragraph IV challenges to norethindrone?
Paragraph IV activity is most relevant when an innovator or branded sponsor lists an unexpired patent for a reference product. Because the principal norethindrone products are old and genericized, current Paragraph IV litigation is not the primary commercial risk for the molecule.
The more relevant risks are:
- Product-specific litigation involving a combination product.
- Patent disputes over a newer formulation.
- Litigation concerning a branded hormone-therapy product containing norethindrone acetate.
- Regulatory disputes over bioequivalence or labeling.
- Supply and manufacturing disputes rather than patent disputes.
A definitive current Paragraph IV inventory requires a product-by-product review of FDA Orange Book listings, ANDA certifications and federal court dockets. No single Paragraph IV case defines the norethindrone market.
What formulation patents protect norethindrone?
Most commercial norethindrone products use immediate-release tablets. The formulation barrier is therefore weak compared with extended-release, injectable or implantable products.
Potential formulation differentiation could involve:
- Modified release.
- Reduced gastrointestinal exposure.
- Improved stability.
- Combination tablets with estrogen.
- Alternative excipients.
- Lower-dose tablets for tolerability.
- Transdermal or vaginal delivery systems.
- Long-acting contraceptive delivery.
These approaches could create patentable products, but they would not necessarily protect the conventional norethindrone market. A reformulated product would also face clinical, regulatory and payer hurdles because generic tablets are inexpensive and familiar.
Which companies compete in the norethindrone market?
Competition is distributed among generic manufacturers, specialty women’s-health companies and branded-product owners.
Relevant participants include:
- Teva Pharmaceutical Industries.
- Viatris.
- Amneal Pharmaceuticals.
- Lupin.
- Glenmark Pharmaceuticals.
- Prasco Laboratories.
- Mayne Pharma.
- Rising Pharma Holdings.
- Xiromed.
- Other ANDA holders and contract manufacturers.
The competitive set varies by product. A company may compete in norethindrone 0.35 mg contraception but not in norethindrone acetate 5 mg, or may supply a combination hormone product without selling the standalone ingredient.
The main competitive variables are:
- Retail and mail-order formulary access.
- Wholesale acquisition cost.
- Generic reimbursement.
- Manufacturing reliability.
- FDA compliance history.
- API sourcing.
- Ability to maintain multiple strengths.
- Shortage resilience.
- Contracting with pharmacy benefit managers.
What generic entry risks exist for norethindrone?
Generic-entry risk is largely historical for core products, not prospective. The market already has generic competition, and further entry would generally increase price pressure rather than create a sudden loss of exclusivity.
The principal commercial risks are different:
Price erosion
Multiple suppliers can reduce average selling prices, especially for high-volume oral contraceptive products. Price competition is less severe when only a small number of suppliers maintain a specific strength or package configuration.
Supply disruption
Norethindrone products can experience commercial volatility if manufacturers exit, API supply tightens or FDA manufacturing actions reduce available inventory. In a low-margin market, one supplier’s withdrawal can temporarily improve pricing for remaining manufacturers.
Channel concentration
Retail pharmacy and purchasing-group concentration can transfer negotiating power to large buyers. Small manufacturers may face lower margins even when prescription volume remains stable.
Substitution
Norethindrone competes with other progestins and with nonhormonal therapies. Switching can occur because of tolerability, contraindications, convenience, prescriber preference or payer formulary design.
How does norethindrone compare with competing progestins?
| Product |
Primary commercial strengths |
Main competitive limitation |
| Norethindrone |
Long clinical history, low cost, contraceptive and gynecologic uses |
Mature generic pricing and frequent dosing |
| Levonorgestrel |
Broad contraceptive use, intrauterine and emergency-contraception options |
Competition across multiple delivery systems |
| Medroxyprogesterone acetate |
Strong position in gynecologic treatment and injectable contraception |
Different safety and tolerability profile |
| Drospirenone |
Newer progestin-only contraceptive positioning |
Higher price and narrower generic availability in some markets |
| Micronized progesterone |
Established menopausal therapy use |
Different pharmacology and administration requirements |
Norethindrone remains competitive where low cost, oral administration and clinical familiarity matter. It is less differentiated where patients or prescribers prioritize long-acting delivery, newer pharmacology or simplified dosing.
What regulatory status affects norethindrone sales?
Norethindrone products are approved through both legacy new drug applications and abbreviated new drug applications. Generic products must demonstrate pharmaceutical equivalence and bioequivalence to the relevant reference product under FDA requirements.[8]
Regulatory factors affecting commercial performance include:
- FDA approval of additional strengths or package sizes.
- ANDA supplements for manufacturing-site changes.
- Labeling changes for contraindications or warnings.
- Drug-supply interruptions.
- Current Good Manufacturing Practice compliance.
- Reference-product availability.
- Bioequivalence requirements for combination products.
Norethindrone is not a biologic, so biosimilar competition is not applicable. The relevant competitive pathway is generic substitution, not the 351(k) biosimilar pathway.
What licensing deals affect norethindrone?
Norethindrone has limited strategic licensing value as a standalone molecule because it is old, generic and widely available. Licensing activity is more likely to involve:
- Commercial rights for branded women’s-health products.
- Combination products.
- Regional distribution.
- Contract manufacturing.
- Private-label supply.
- Authorized-generic arrangements.
- Portfolio transactions involving broader hormone-therapy assets.
A norethindrone licensing deal would generally have a lower valuation than a transaction involving a novel progestin, long-acting delivery system or patented combination. The principal asset would be market access, manufacturing capacity or a differentiated formulation rather than the active ingredient.
What is the outlook for norethindrone?
The base-case outlook is stable prescription demand with low molecule-level growth. Volume should remain supported by contraception, abnormal uterine bleeding and menopausal therapy, but price increases are constrained by generic substitution and payer pressure.
The most credible sources of upside are:
- Temporary supply shortages.
- A differentiated low-dose or modified-release product.
- A long-acting delivery system.
- Expansion in underserved international markets.
- Improved distribution or manufacturing reliability.
- A branded combination with clinically meaningful differentiation.
The main downside risks are:
- Additional generic entrants.
- Continued price compression.
- Manufacturing remediation.
- API concentration.
- Substitution by newer progestins.
- Declining use of selected menopausal hormone products.
Key Takeaways
- Norethindrone is a mature generic progestin, not an active-ingredient exclusivity story.
- The market includes standalone norethindrone, norethindrone acetate and estrogen combinations.
- Public companies do not generally disclose norethindrone-specific revenue.
- Financial performance is driven by prescription volume, price competition, supply reliability and channel access.
- Core products have low patent barriers; any remaining IP value is product-specific.
- Paragraph IV litigation is not the central market risk for legacy norethindrone products.
- Biosimilar risk does not apply because norethindrone is a small-molecule drug.
- Long-term molecule-level revenue is likely flat to declining, with temporary volatility from shortages or supplier exits.
- Commercial upside depends on formulation, delivery-system or combination-product differentiation.
FAQs
Is norethindrone still under patent?
The legacy norethindrone active ingredient and principal oral products are not protected by meaningful current composition-of-matter exclusivity. Specific combination, formulation or method-of-use patents must be reviewed separately.
Is norethindrone a branded or generic drug?
Both exist, but the market is predominantly generic. Historical brand names include Ortho Micronor and Aygestin, while current supply is distributed across multiple generic manufacturers and product labels.
Does norethindrone have biosimilar competition?
No. Norethindrone is a small-molecule drug. Its competitive pathway is generic substitution through ANDAs, not biosimilar approval.
Which norethindrone product has the greatest commercial value?
Commercial value depends on volume and pricing. Norethindrone 0.35 mg has broad contraceptive demand, while norethindrone acetate 5 mg can generate higher value per prescription in gynecologic treatment. No public data establishes one product as the highest-revenue formulation across all manufacturers.
Can a new norethindrone formulation obtain patent protection?
Potentially. A novel release profile, delivery system, combination, manufacturing process or clinically differentiated formulation may be patentable. A conventional immediate-release norethindrone tablet would face a weak patent position and intense generic competition.
References
-
U.S. Food and Drug Administration. (n.d.). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
-
Amneal Pharmaceuticals, Inc. (2024). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934.
-
Teva Pharmaceutical Industries Ltd. (2024). Annual report on Form 20-F.
-
Viatris Inc. (2024). Annual report on Form 10-K.
-
Lupin Limited. (2024). Annual report.
-
U.S. Food and Drug Administration. (n.d.). Orange Book: Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/
-
U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations. https://www.fda.gov/drugs/drug-approvals-and-databases/orange-book
-
U.S. Food and Drug Administration. (2024). Generic drug facts. https://www.fda.gov/drugs/generic-drugs/generic-drug-facts