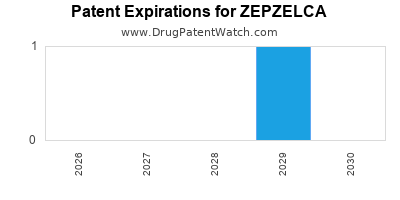
Last updated: September 29, 2026
Zepzelca, the commercial name for lurbinectedin, is an FDA-approved treatment for metastatic small-cell lung cancer after progression on platinum-based chemotherapy. Jazz Pharmaceuticals commercializes Zepzelca in the United States under a license from PharmaMar. The drug generated an estimated $480 million to $490 million in U.S. net sales in 2024, up from roughly $365 million in 2023 and about $267 million in 2022, according to Jazz financial disclosures and company earnings materials.[1][2]
The asset has a credible growth path through deeper second-line penetration, international expansion and potential first-line maintenance use. Its principal risks are the narrow approved indication, competition from platinum rechallenge and topotecan, dependence on clinical validation in earlier treatment settings, and the eventual erosion of U.S. exclusivity by generic lurbinectedin products.
What is Zepzelca and how does it work?
Zepzelca is an intravenous formulation of lurbinectedin, a synthetic tetrahydroisoquinoline derivative that binds DNA and inhibits oncogenic transcription. The drug also affects tumor-associated macrophages and suppresses transcription-dependent DNA repair mechanisms.
The approved regimen is 3.2 mg/m² by intravenous infusion every 21 days until disease progression or unacceptable toxicity. Zepzelca is indicated for adult patients with metastatic small-cell lung cancer with disease progression on or after platinum-based chemotherapy.[3]
The most commercially relevant clinical attributes are:
| Attribute |
Zepzelca |
| Active ingredient |
Lurbinectedin |
| Dosage form |
Intravenous infusion |
| Approved indication |
Metastatic small-cell lung cancer after platinum-based chemotherapy |
| FDA approval |
June 15, 2020 |
| Regulatory pathway |
Accelerated approval |
| Sponsor at approval |
PharmaMar |
| U.S. commercial partner |
Jazz Pharmaceuticals |
| Dosing interval |
Every 21 days |
| Primary use |
Second-line or later treatment |
| Orphan-drug exclusivity |
Expected through June 2027, subject to applicable regulatory conditions |
Zepzelca is not a biologic. Biosimilar competition is therefore not relevant. Future competition would come from conventional generic or 505(j) applicants, branded small-cell lung cancer therapies and new combinations.
How have Zepzelca sales changed?
Zepzelca sales have increased rapidly since Jazz assumed U.S. commercialization. The product moved from launch-stage revenue to a material oncology franchise within four years.
| Fiscal year |
Approximate Zepzelca net sales |
Year-over-year change |
| 2020 |
Launch period |
Not comparable |
| 2021 |
$90 million |
Initial commercial ramp |
| 2022 |
$267 million |
Approximately 195% |
| 2023 |
$365 million |
Approximately 37% |
| 2024 |
$480 million-$490 million |
Approximately 32%-34% |
Sources: Jazz Pharmaceuticals annual reports, earnings releases and investor materials.[1][2]
What drove Zepzelca’s revenue growth?
The growth has been driven primarily by:
- Increased physician familiarity with lurbinectedin in relapsed small-cell lung cancer.
- Wider use after platinum failure, particularly in patients who are not candidates for platinum rechallenge.
- Expansion of Jazz’s oncology sales infrastructure after the company acquired U.S. rights.
- Greater recognition of Zepzelca as an alternative to topotecan and other later-line treatments.
- Growth in treated-patient volume rather than a major change in dosing or label breadth.
Zepzelca remains a concentrated product. Jazz does not separately disclose all lurbinectedin economics, including gross-to-net adjustments, treatment duration or U.S. versus ex-U.S. revenue in a way that permits a complete margin reconstruction.[1]
What is the outlook for Zepzelca revenue?
The near-term outlook remains positive, but the product’s growth rate should moderate as it matures in second-line disease.
A reasonable commercial trajectory is:
| Period |
Market outlook |
| 2025-2026 |
Continued double-digit growth from penetration and treatment persistence |
| 2027 |
Potential peak of current second-line opportunity if first-line data remain unresolved |
| 2028 onward |
Greater exposure to generic entry risk, depending on patent litigation and approval timing |
| Longer term |
Upside depends on first-line maintenance, combination regimens and international adoption |
The central value driver is the Phase 3 IMforte program, which evaluates lurbinectedin with atezolizumab as maintenance therapy after induction treatment in extensive-stage small-cell lung cancer. A positive result could expand Zepzelca from a post-platinum rescue therapy into a larger maintenance market.[4]
The commercial impact of a successful maintenance indication would be substantial because patients could receive lurbinectedin earlier in the treatment sequence and potentially for longer periods. A negative or inconclusive result would leave the product dependent on the narrower relapsed-disease market.
How large is the addressable market for lurbinectedin?
Small-cell lung cancer represents approximately 10% to 15% of lung cancer cases. Most patients present with extensive-stage disease or develop metastatic recurrence. The population eligible for second-line therapy is smaller than the total small-cell lung cancer population because of rapid disease progression, poor performance status and treatment attrition.
Zepzelca’s current market is therefore defined by:
- Patients with metastatic disease.
- Prior platinum exposure.
- Progression after first-line therapy.
- Sufficient performance status for intravenous treatment.
- Access to an oncology practice able to administer the drug.
The market is clinically meaningful but structurally limited. The product does not currently treat the full first-line small-cell lung cancer population, and many patients do not reach a second-line treatment decision.
How does Zepzelca compare with competing small-cell lung cancer drugs?
Zepzelca competes in a market with limited effective options but significant treatment pressure.
| Therapy |
Role in small-cell lung cancer |
Commercial position |
| Zepzelca |
Later-line treatment after platinum |
Differentiated branded option with growing use |
| Topotecan |
Established second-line treatment |
Generic pricing pressure and historical standard-of-care status |
| Platinum rechallenge |
Selected patients with longer treatment-free intervals |
Low-cost alternative in appropriate patients |
| Tarlatamab |
Emerging DLL3-directed therapy |
Potentially important competitive threat if broadly adopted |
| Clinical trials |
Earlier and later lines |
Expands competition through immunotherapy and targeted approaches |
Topotecan is available in oral and intravenous forms and has a long treatment history, but its toxicity profile and modest efficacy create room for Zepzelca. Tarlatamab, an investigational or newly emerging DLL3-directed therapy depending on regulatory timing, could exert greater pressure because it targets a validated small-cell lung cancer antigen and may compete for the same relapsed population.
Zepzelca’s clinical differentiation depends on response durability, tolerability, physician experience and ease of integration into community oncology practice. Its intravenous administration and myelosuppression remain commercial disadvantages relative to therapies with less burdensome delivery models.
What is the FDA regulatory status of Zepzelca?
The FDA granted accelerated approval on June 15, 2020, based on response rate and duration of response in a single-arm clinical study of patients with metastatic small-cell lung cancer whose disease had progressed on or after platinum-based chemotherapy.[3]
Accelerated approval requires confirmatory evidence. The IMforte study is the principal commercial and regulatory catalyst. Its outcome could support a new indication, strengthen the existing product profile or create regulatory pressure if confirmatory obligations are not satisfied.
The regulatory status has four commercial implications:
- The current indication remains available for post-platinum metastatic disease.
- The label is narrower than a first-line or maintenance indication.
- Confirmatory trial performance affects long-term label durability.
- A successful combination strategy could increase both eligible patients and treatment duration.
When does Zepzelca lose exclusivity?
Zepzelca’s effective loss-of-exclusivity date cannot be reduced to a single number because regulatory exclusivity, patent rights and litigation outcomes operate separately.
FDA orphan-drug exclusivity
Zepzelca received orphan-drug designation for small-cell lung cancer. The seven-year orphan exclusivity period associated with the U.S. approval is expected to run through approximately June 2027.[3]
Orphan exclusivity blocks FDA approval of the same drug for the same orphan indication, subject to statutory exceptions. It does not prevent all competing products in the broader disease category, and it does not replace patent protection.
Patent protection
The U.S. patent estate is expected to include claims directed to lurbinectedin, pharmaceutical compositions and methods of treating cancer. Later-filed patents may extend beyond the basic compound term where they cover formulations, dosing schedules, combinations or treatment methods.
Relevant patent-risk categories include:
| Patent category |
Relevance to Zepzelca |
| Compound patents |
Protect lurbinectedin itself |
| Composition patents |
Cover injectable formulations and excipient systems |
| Method-of-use patents |
Cover treatment of small-cell lung cancer and dosing schedules |
| Combination patents |
May cover lurbinectedin with checkpoint inhibitors or other agents |
| Manufacturing patents |
Can raise process-replication and supply-chain barriers |
The most commercially important claims are likely to be composition, dosing and method-of-use claims that remain enforceable after the earliest compound claims expire. Exact generic-entry timing will depend on the Orange Book listing, patent-term adjustments, any patent-term extension, Paragraph IV litigation and the scope of approved generic labeling.
What is the Orange Book status of Zepzelca?
Zepzelca is an FDA-approved small-molecule drug that can be subject to Orange Book patent listing. The relevant entries may cover the active ingredient, drug product and approved methods of use. A generic applicant seeking approval before listed patent expiry could file an Abbreviated New Drug Application with a Paragraph IV certification against one or more listed patents.[5]
The business implications are:
- A Paragraph IV filing could trigger patent litigation within 45 days of notice.
- Litigation could impose a 30-month stay on final FDA approval, subject to statutory exceptions.
- A first substantially complete Paragraph IV applicant may qualify for 180 days of generic exclusivity.
- A generic could design around some method-of-use claims while still pursuing a carve-out for patented indications.
Jazz’s public financial filings through the 2024 reporting cycle did not identify a material Zepzelca Paragraph IV settlement or a disclosed generic launch date.[1] The absence of a disclosed challenge does not eliminate future litigation risk.
Which companies are challenging Zepzelca?
No publicly disclosed generic challenger had materially disrupted Zepzelca sales through the 2024 reporting period. The likely challenger set includes:
- Large generic manufacturers with oncology injectable capabilities.
- Specialty injectable companies seeking a niche hospital or community-oncology product.
- Companies with access to lurbinectedin manufacturing or process know-how.
- Branded competitors developing DLL3-directed or immunotherapy-based treatments.
The initial challenge is more likely to arise from a company with sterile injectable manufacturing capacity than from a conventional oral-generic specialist. Lurbinectedin is a complex oncology injectable, which raises development, analytical and manufacturing requirements.
How strong is the Zepzelca patent estate?
The estate has moderate-to-strong commercial value while the product remains protected by a combination of regulatory exclusivity, patent claims and manufacturing complexity. Its strength is lower if value is concentrated in narrow method-of-use claims that can be avoided through label carving.
Factors supporting patent strength
- Orphan-drug exclusivity extends through approximately 2027.
- Lurbinectedin is a complex active pharmaceutical ingredient.
- Injectable oncology products require specialized formulation and sterile manufacturing.
- Combination and maintenance-use patents could extend beyond the current label.
- Generic applicants may face substantial bioequivalence and product-quality work.
Factors limiting patent strength
- The active ingredient is a small molecule rather than a biologic.
- Generic applicants can use the 505(j) pathway.
- Second-line oncology indications can permit label carve-outs.
- A generic may challenge composition or formulation claims before commercial launch.
- Clinical value is concentrated in one principal indication.
Patent quality will depend less on the number of listed patents than on whether at least one enforceable claim covers the commercial product or the only practical approved use.
What manufacturing and supply barriers affect Zepzelca?
Lurbinectedin requires specialized active-ingredient synthesis, formulation development and sterile injectable production. Manufacturing barriers may delay generic competition, but they do not create permanent exclusivity.
The main barriers are:
- Complex chemical synthesis.
- Control of impurities and degradation products.
- Sterile fill-finish capacity.
- Validated analytical methods.
- Oncology supply-chain and hospital distribution requirements.
- Ability to reproduce the reference product’s quality attributes.
PharmaMar has historical expertise with lurbinectedin manufacturing, while Jazz controls U.S. commercial execution. The license arrangement gives Jazz market access without requiring it to originate the molecule.
What licensing deal governs Zepzelca?
Jazz licensed U.S. rights to lurbinectedin from PharmaMar in 2020. The transaction included an upfront payment reported at approximately $200 million, potential milestone payments of up to approximately $250 million, and royalties on sales.[6]
The deal transferred substantial commercial responsibility to Jazz while preserving PharmaMar’s economic participation. The arrangement reduced Jazz’s discovery risk but left the company dependent on:
- Royalty obligations.
- PharmaMar’s supply and technical capabilities.
- Successful regulatory expansion.
- Continued performance in a single disease area.
The agreement also gave Jazz a relatively fast route into oncology without acquiring an entire oncology platform.
What litigation and settlement risks affect Zepzelca?
The most important future litigation issue is a potential Paragraph IV challenge. If a generic applicant files against listed patents, Jazz could seek an injunction or damages while the FDA approval process proceeds.
Key litigation scenarios are:
| Scenario |
Likely commercial effect |
| No Paragraph IV filing before key patent expiry |
Continued branded sales until patent expiration |
| Paragraph IV challenge with 30-month stay |
Delayed generic approval and higher legal cost |
| Early settlement with licensed generic entry |
Predictable but earlier erosion |
| Patent invalidation or noninfringement ruling |
Accelerated generic launch |
| Narrow label carve-out |
Limited generic competition by indication |
| Successful later-use patents |
Protection for maintenance or combination sales |
No material Zepzelca patent settlement was identified in Jazz’s disclosed reporting through 2024.[1]
What are the main risks to Zepzelca’s financial trajectory?
The principal risks are commercial rather than manufacturing-driven.
Clinical and regulatory risk
Failure of IMforte would restrict the product to later-line use and reduce the probability of a larger revenue expansion. Regulatory conversion or label expansion is not assured under the accelerated-approval framework.
Competitive risk
Topotecan remains available at generic prices. New therapies directed at DLL3 or other small-cell lung cancer targets could take share, especially if they offer better response durability or less myelosuppression.
Concentration risk
Zepzelca is an important Jazz asset, but its revenue base is concentrated in one cancer type and one treatment setting. A single negative clinical result or patent event could have an outsized impact on growth.
Pricing and access risk
Payers may require sequencing after platinum therapy or prior authorization. Oncology practices may favor lower-cost generic topotecan for price-sensitive patients, particularly where comparative efficacy is uncertain.
Generic-entry risk
The highest erosion risk begins after the orphan-exclusivity period and increases as patents expire or are narrowed through litigation. A complex injectable may delay competition but is unlikely to prevent it indefinitely.
Key Takeaways
- Zepzelca is Jazz Pharmaceuticals’ lurbinectedin franchise for metastatic small-cell lung cancer after platinum failure.
- Estimated sales increased from about $267 million in 2022 to approximately $365 million in 2023 and $480 million-$490 million in 2024.
- The current market is commercially attractive but limited by the small-cell lung cancer treatment funnel and later-line positioning.
- The IMforte maintenance program is the main catalyst for a larger addressable market.
- FDA orphan-drug exclusivity is expected to run through approximately June 2027.
- Zepzelca faces future 505(j) generic risk rather than biosimilar risk.
- The patent estate’s value will depend on enforceable compound, formulation, dosing, combination and method-of-use claims.
- No material Paragraph IV settlement or generic launch was publicly disclosed through Jazz’s 2024 reporting cycle.
- Tarlatamab and other DLL3-directed therapies are the most important emerging competitive threats.
- The product’s revenue trajectory remains positive, but long-term upside depends on first-line or maintenance expansion.
FAQs About Zepzelca Market and Patent Risk
What is the peak-sales potential for Zepzelca?
Zepzelca could exceed current second-line sales if maintenance or combination use receives FDA approval. Without label expansion, the product is more likely to mature as a several-hundred-million-dollar oncology asset rather than become a multibillion-dollar franchise.
Is Zepzelca a chemotherapy drug?
Zepzelca is a cytotoxic anticancer drug that inhibits oncogenic transcription and DNA-related processes. It is administered intravenously and is used after platinum-based chemotherapy in metastatic small-cell lung cancer.
Does Zepzelca have biosimilar competition?
No. Zepzelca is a small-molecule drug, so the relevant future competitors are generic lurbinectedin products approved under the ANDA pathway, not biosimilars under the biologics framework.
Can a generic launch Zepzelca before all patents expire?
A generic could potentially launch before all listed patents expire if it prevails in litigation, obtains a favorable settlement, uses a permissible label carve-out or receives approval after a patent challenge under applicable FDA rules.
What event would most improve Zepzelca’s valuation?
A positive IMforte result followed by FDA approval of a maintenance or combination indication would have the greatest potential to improve Zepzelca’s valuation by expanding patient eligibility and increasing treatment duration.
References
- Jazz Pharmaceuticals plc. (2025). 2024 annual report and Form 10-K.
- Jazz Pharmaceuticals plc. (2024-2025). Quarterly earnings releases and investor presentations.
- U.S. Food and Drug Administration. (2020). Zepzelca approval letter and prescribing information.
- ClinicalTrials.gov. (n.d.). IMforte: A phase 3 study of lurbinectedin plus atezolizumab as maintenance therapy in extensive-stage small-cell lung cancer.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- PharmaMar. (2020). PharmaMar and Jazz Pharmaceuticals enter exclusive U.S. licensing agreement for lurbinectedin.