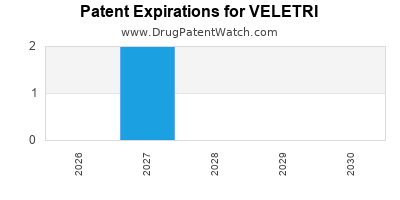
Last updated: September 24, 2026
Veletri is a branded formulation of epoprostenol sodium used by continuous intravenous infusion for pulmonary arterial hypertension. Its market is small, specialized, and hospital-centered. Demand remains supported by severe disease, treatment guidelines, and the clinical role of parenteral prostacyclin therapy, but long-term growth is constrained by oral and inhaled pulmonary hypertension medicines, generic epoprostenol products, treatment complexity, and limited standalone financial disclosure.
Veletri’s commercial value is concentrated in product reliability, formulation stability, hospital familiarity, and supply continuity rather than in broad market expansion. Johnson & Johnson does not report Veletri revenue as a separate product line, preventing a precise public revenue series. The available evidence indicates a mature, declining-to-stable branded product with continuing strategic relevance in high-acuity pulmonary arterial hypertension.
What is Veletri and how is it used?
Veletri is epoprostenol sodium for injection, administered by continuous intravenous infusion through an external pump. The FDA approved Veletri in 2008 for the treatment of pulmonary arterial hypertension, including patients in World Health Organization functional classes II through IV, to improve exercise capacity. The product is listed under U.S. New Drug Application No. 022260. [1]
Epoprostenol is a prostacyclin analogue. It produces pulmonary and systemic vasodilation and inhibits platelet aggregation. Because the molecule has a very short half-life, interruption of infusion can cause rapid clinical deterioration. That characteristic creates a high clinical dependence on infusion equipment, trained caregivers, hospital protocols, and reliable product supply.
Veletri compared with Flolan
Veletri was developed as a more stable formulation of epoprostenol than the original Flolan product. Flolan required more demanding storage and handling conditions after reconstitution. Veletri’s formulation and stability profile reduced some operational burdens for hospitals and patients, particularly in outpatient infusion settings. [1]
| Attribute |
Veletri |
Flolan |
Generic epoprostenol |
| Active ingredient |
Epoprostenol sodium |
Epoprostenol sodium |
Epoprostenol sodium |
| Delivery |
Continuous IV infusion |
Continuous IV infusion |
Continuous IV infusion |
| Primary use |
Pulmonary arterial hypertension |
Pulmonary arterial hypertension |
Pulmonary arterial hypertension |
| Commercial position |
Branded, established product |
Legacy branded product |
Lower-price alternatives |
| Main differentiation |
Formulation stability and handling |
Historical clinical familiarity |
Price and supply availability |
| Key risk |
Generic substitution and market migration |
Product discontinuation or reduced use |
Manufacturing and supply consistency |
What is the Veletri market size?
The addressable Veletri market is narrower than the overall pulmonary hypertension market. The broader pulmonary arterial hypertension market includes oral endothelin receptor antagonists, phosphodiesterase-5 inhibitors, soluble guanylate cyclase stimulators, prostacyclin receptor agonists, inhaled prostacyclins, and parenteral prostacyclin products.
Veletri is used mainly in patients with advanced or high-risk disease, including patients who require rapid and potent pulmonary vasodilation. It therefore occupies a smaller volume segment but has higher treatment intensity and greater switching friction than oral medicines.
The market is shaped by four factors:
- The number of patients progressing to parenteral prostacyclin therapy.
- The movement of newly diagnosed patients toward combination therapy with oral agents.
- Generic price competition.
- Hospital and specialty-pharmacy requirements for uninterrupted supply.
Guidelines continue to reserve intravenous epoprostenol and intravenous or subcutaneous treprostinil for selected patients with severe or high-risk pulmonary arterial hypertension. [2] That clinical role limits the risk of complete displacement, even as the overall treatment pathway becomes more oral and combination-based.
What is Veletri’s financial trajectory?
Johnson & Johnson does not disclose Veletri net sales as a standalone line item in its public financial reporting. Actelion, which originated the product, also reported its portfolio through broader pulmonary hypertension categories in later periods. A precise annual Veletri revenue trend therefore cannot be reconstructed from company filings.
The commercial trajectory can be characterized as follows:
| Period |
Market condition |
Financial implication |
| 2008 to early 2010s |
Launch and adoption of a more stable epoprostenol formulation |
Revenue growth from conversion and hospital adoption |
| Mid-2010s |
Expansion of the pulmonary hypertension portfolio, including Opsumit and Uptravi |
Veletri became a mature portfolio product rather than the primary growth engine |
| 2017 onward |
Actelion acquired by Johnson & Johnson; broader portfolio integration |
Standalone visibility declined |
| 2020 onward |
Greater generic competition and continued migration toward oral and inhaled therapies |
Pricing and volume pressure |
| Current mature phase |
Persistent use in high-risk patients and specialized centers |
Stable strategic demand with limited growth potential |
Veletri’s revenue exposure is likely more resilient than its unit growth. The product is used in a severe disease population, and switching patients who are stable on continuous infusion can carry clinical and operational risks. New starts are more price-sensitive because physicians and hospitals can evaluate branded and generic epoprostenol options before initiating therapy.
When did Veletri lose exclusivity?
Veletri does not have the exclusivity profile of a recently launched specialty medicine. Its principal regulatory exclusivity periods have expired, and the product competes with generic epoprostenol sodium injections.
The practical protection around Veletri is now based on:
- formulation and handling characteristics;
- physician and hospital familiarity;
- infusion-center protocols;
- product availability;
- manufacturing reliability;
- contractual and distribution relationships;
- patient stability on an established regimen.
The Orange Book identifies Veletri under NDA 022260 and provides the applicable patent and exclusivity information for the listed product. [3] The commercial importance of the product’s original formulation protection has diminished as the market has matured and alternative epoprostenol products have entered.
What patents protect Veletri?
Veletri’s historical intellectual-property position centered on formulation stability, preparation, and delivery of epoprostenol rather than on a new chemical entity. Because epoprostenol is an established active ingredient, the product’s patent estate has less strategic depth than the patent estates of newer pulmonary hypertension drugs.
The relevant patent categories include:
- stable epoprostenol formulations;
- storage and reconstitution methods;
- dosage forms for continuous infusion;
- manufacturing processes;
- container and delivery-system configurations;
- methods of treating pulmonary arterial hypertension with epoprostenol.
Patent-based protection is less important today than the product’s operational barriers. A competitor must supply a sterile injectable product, obtain FDA approval, demonstrate manufacturing consistency, and support hospitals that cannot tolerate supply interruptions.
What is the FDA regulatory status of Veletri?
Veletri remains an FDA-approved prescription product under NDA 022260. Its approval covers epoprostenol sodium for continuous intravenous infusion in pulmonary arterial hypertension. [1]
The regulatory profile has several implications:
- Veletri is a drug product, not a biologic, so biosimilar legislation does not apply.
- Generic competition proceeds through the abbreviated new drug application pathway.
- There is no biosimilar risk because epoprostenol is a small-molecule drug.
- FDA approval does not guarantee automatic substitution in every hospital or payer setting.
- Injectable-product manufacturing and supply controls can influence formulary decisions as much as price.
Does Veletri face biosimilar risk?
No. Veletri contains epoprostenol sodium, a small-molecule active ingredient. Competitors enter through generic drug applications rather than the biosimilar pathway under the Public Health Service Act.
The competitive risk is generic substitution, not biosimilar interchangeability. That distinction matters because generic epoprostenol can compete on price while still requiring hospitals to assess concentration, diluent, stability, packaging, device compatibility, and preparation procedures.
Which companies challenge Veletri?
The principal competitive threat comes from generic epoprostenol manufacturers and from branded alternatives in the parenteral prostacyclin class.
Competitive pressure comes from three directions:
Generic epoprostenol manufacturers
Generic suppliers compete directly with Veletri on acquisition cost. The market includes manufacturers with experience in sterile injectables and hospital products. Their ability to win share depends on FDA approval, supply reliability, hospital contracting, and compatibility with existing infusion practices.
Treprostinil products
Treprostinil, marketed in intravenous, subcutaneous, inhaled, and oral forms, competes with epoprostenol for patients who need prostacyclin-pathway therapy. Its longer half-life and multiple delivery options reduce some of the operational burdens associated with epoprostenol. Treprostinil products include Remodulin, Tyvaso, and Orenitram. [4]
Oral pulmonary hypertension therapies
Opsumit, Uptravi, Adempas, tadalafil, sildenafil, and related products compete earlier in the treatment pathway. They do not fully replace intravenous epoprostenol in high-risk patients, but they can delay or reduce the number of patients who progress to continuous infusion.
How strong is the Veletri patent estate?
Veletri has a moderate-to-weak current patent position and a stronger non-patent commercial position.
| Protection category |
Current strength |
Commercial effect |
| Active-ingredient patent |
Low |
Epoprostenol is an established molecule |
| Formulation patents |
Limited and time-dependent |
May restrict specific formulations, not the entire category |
| Method-of-use patents |
Limited |
Treatment claims face narrow practical scope |
| Regulatory exclusivity |
Expired or no longer central |
Does not block generic entry |
| Manufacturing know-how |
Moderate |
Important for sterile injectable quality |
| Supply and hospital integration |
Moderate to strong |
Creates switching friction |
| Brand recognition |
Moderate |
Supports retention in specialty centers |
The product’s defensibility is therefore operational rather than primarily patent-based. A generic entrant can erode price without immediately replacing all branded volume, especially where hospitals prioritize dual sourcing, established protocols, and supply continuity.
What formulation patents and manufacturing barriers matter?
The most important technical barriers relate to sterile injectable manufacturing and product stability.
Epoprostenol products must meet demanding requirements for:
- sterile production;
- stability after reconstitution;
- container closure integrity;
- accurate concentration and dilution;
- compatibility with infusion pumps and tubing;
- lot consistency;
- storage and shipping controls;
- continuity of supply.
Formulation differences can affect pharmacy preparation, refrigeration, room-temperature handling, replacement intervals, and nursing procedures. These differences can preserve some branded value even after patent expiry.
Manufacturing complexity also limits the number of credible suppliers. A company may obtain approval yet remain commercially weak if it cannot maintain uninterrupted inventory across hospitals, specialty pharmacies, and distributors.
What patent litigation and Paragraph IV challenges affect Veletri?
No major, widely reported Veletri-specific patent litigation or settlement has defined the product’s current commercial position in the public record through the latest broadly available company and FDA materials.
The principal legal risk is generic entry under Paragraph IV certification against any unexpired Orange Book-listed formulation or method patents. A successful Paragraph IV challenge could trigger early entry before the relevant patent expiry. Conversely, a patent infringement suit could impose a 30-month stay on FDA approval of a qualifying ANDA, subject to the statutory requirements and litigation outcome. [3, 5]
Because Veletri’s active ingredient is old and the product has a mature market, litigation value is likely concentrated in narrow formulation or product-specific claims rather than broad compound claims.
What generic launch scenarios exist for Veletri?
Scenario 1: Gradual generic conversion
Hospitals adopt generic epoprostenol for new patients first. Existing Veletri patients remain on the branded product where clinicians value continuity or where switching requires pharmacy and pump changes. This produces gradual price erosion without an immediate collapse in branded demand.
Scenario 2: Rapid formulary substitution
Large hospital systems and specialty pharmacies select a generic supplier based on price and guaranteed supply. Veletri loses new starts and a significant portion of maintenance volume. This scenario requires a generic product with dependable availability and operational equivalence.
Scenario 3: Dual-source market
Hospitals retain Veletri and one or more generic suppliers to reduce shortage risk. Price pressure increases, but Veletri preserves a residual share through brand familiarity and supply diversification.
Scenario 4: Supply-driven branded retention
Generic manufacturers experience shortages, manufacturing interruptions, or limited distribution. Veletri retains share because uninterrupted treatment is more valuable than the nominal acquisition-price discount.
The most likely long-term structure is a dual-source or multi-source market, with generic products taking price-sensitive volume while Veletri retains a specialty and continuity-based position.
What licensing deals affect Veletri?
Veletri originated in Actelion’s pulmonary hypertension portfolio. Johnson & Johnson acquired Actelion in 2017 and retained the pulmonary hypertension assets through its Innovative Medicine operations. [6]
The Actelion transaction was strategically important because it placed Veletri alongside Opsumit and Uptravi. Veletri contributes portfolio depth and physician access, but it is less likely to drive growth than newer products with broader treatment-line opportunities.
No major publicly disclosed recent licensing transaction appears to have changed Veletri’s core commercial ownership or materially altered its competitive position.
How does Veletri compare with competing prostacyclin therapies?
| Product |
Active ingredient |
Route |
Commercial advantage |
Main limitation |
| Veletri |
Epoprostenol |
IV |
Established efficacy, stable formulation, high-acuity use |
Continuous infusion and short half-life |
| Generic epoprostenol |
Epoprostenol |
IV |
Lower price |
Supplier reliability and product-specific handling |
| Remodulin |
Treprostinil |
IV or subcutaneous |
Longer half-life and broader administration options |
Site pain with subcutaneous delivery and ongoing infusion burden |
| Tyvaso |
Treprostinil |
Inhaled |
Avoids continuous IV infusion |
Repeated inhalation sessions and device dependence |
| Orenitram |
Treprostinil |
Oral |
Oral administration |
Less suitable for patients requiring parenteral prostacyclin intensity |
| Uptravi |
Selexipag |
Oral |
Prostacyclin-pathway therapy without infusion |
Not a direct substitute for high-risk IV epoprostenol |
Veletri remains strongest in patients for whom parenteral prostacyclin intensity is clinically necessary. It is weakest in patients who can be managed with oral or inhaled therapies and in new patients for whom hospitals can choose a lower-cost generic.
What is the investment outlook for Veletri?
Veletri is a mature cash-generation product rather than a high-growth asset. Its positive attributes are clinical necessity in a narrow population, high switching friction, and manufacturing barriers. Its negative attributes are expired market exclusivity, generic competition, limited patient expansion, and portfolio substitution by oral and inhaled products.
Revenue should be expected to depend on:
- retention of existing infusion patients;
- generic price and supply behavior;
- the rate of progression to high-risk pulmonary arterial hypertension;
- hospital formulary decisions;
- manufacturing reliability;
- the ability of the owner to maintain specialty distribution.
The absence of standalone revenue disclosure limits valuation precision. Veletri should be modeled as a specialty maintenance product with declining or flat branded volume, rather than as a growth medicine. Upside would require supply disruption among competitors, successful retention of high-acuity accounts, or pricing resilience. Downside would come from broad formulary conversion to generic epoprostenol and continued reduction in new IV starts.
Key Takeaways
- Veletri is a branded epoprostenol sodium product for continuous intravenous treatment of pulmonary arterial hypertension.
- Its FDA approval under NDA 022260 dates to 2008.
- The product’s main commercial advantage is formulation stability, clinical familiarity, and supply reliability.
- Regulatory exclusivity and broad compound protection are no longer the central barriers to competition.
- Generic epoprostenol is the primary direct threat.
- Treprostinil and oral pulmonary hypertension therapies constrain new-patient growth.
- Veletri is not exposed to biosimilar competition.
- Johnson & Johnson does not disclose standalone Veletri revenue, so an exact public financial trajectory is unavailable.
- The product is best characterized as a mature specialty medicine with resilient but limited revenue potential.
- Manufacturing quality, hospital protocols, and supply continuity are more important current defenses than a broad patent estate.
FAQs
Is Veletri still commercially important after generic epoprostenol entry?
Yes. It remains relevant in high-risk pulmonary arterial hypertension, where physicians and hospitals value established protocols, product stability, and reliable supply.
Can a generic epoprostenol automatically replace Veletri?
Not necessarily. Substitution depends on the product’s FDA status, state substitution rules, hospital policy, formulation, concentration, infusion-device compatibility, and prescriber or pharmacy decisions.
Is Veletri covered by a composition-of-matter patent?
The key commercial protection is not a current broad composition-of-matter patent on epoprostenol. Epoprostenol is an established active ingredient, so remaining protection is more likely to involve formulation, manufacturing, or product-specific claims.
Does Veletri have orphan-drug protection?
Veletri benefits from its use in a rare disease area, but orphan-drug exclusivity is time-limited and does not provide permanent market protection. Generic entry depends on applicable FDA exclusivity and patent barriers.
What would most improve Veletri’s financial outlook?
The strongest positive drivers would be reliable supply during competitor shortages, continued use in high-risk patients, retention in specialty centers, and slower-than-expected conversion to generic epoprostenol.
References
- U.S. Food and Drug Administration. (2008). Veletri (epoprostenol sodium) for injection: Prescribing information.
- Humbert, M., Kovacs, G., Hoeper, M. M., Badagliacca, R., Berger, R. M. F., Brida, M., Carlsen, J., Coats, A. J. S., Escribano-Subias, P., Ferrari, P., Ferreira, D. S., Ghofrani, H. A., Giardino, G., et al. (2022). 2022 ESC/ERS Guidelines for the diagnosis and treatment of pulmonary hypertension. European Heart Journal, 43(38), 3618-3731.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- United Therapeutics Corporation. (2023). Annual report on Form 10-K.
- U.S. Food and Drug Administration. (2024). ANDA approvals and patent certification requirements.
- Johnson & Johnson. (2017). Johnson & Johnson completes acquisition of Actelion Ltd.