Last updated: September 27, 2026
Staxyn is the orally disintegrating tablet formulation of vardenafil hydrochloride, a phosphodiesterase-5 inhibitor for erectile dysfunction. Bayer developed Staxyn as an alternative to conventional Levitra tablets, using a formulation that dissolves on the tongue without water. Its commercial opportunity was limited by competition from Viagra, Cialis and Levitra, narrow differentiation within the PDE5 class, and the loss of branded pricing after vardenafil patent protection weakened.
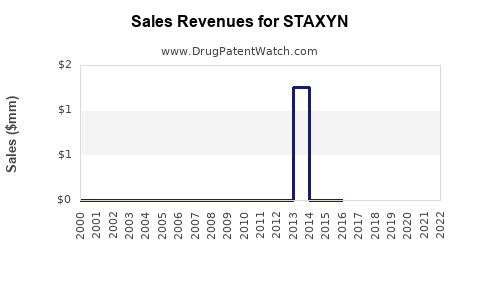
Staxyn has no separately reported public revenue stream. Bayer’s financial disclosures generally grouped Levitra and related vardenafil products within broader prescription-pharmaceutical or regional product categories. The available public record supports a declining, late-lifecycle product profile rather than a separately valued growth asset.
What is Staxyn and how does it compare with Levitra?
Staxyn contains vardenafil hydrochloride and is marketed in 10-mg orally disintegrating tablets. Levitra contains the same active ingredient in conventional tablet form. Both products inhibit PDE5 and are indicated for the treatment of erectile dysfunction in adult men.
| Attribute |
Staxyn |
Levitra |
| Active ingredient |
Vardenafil hydrochloride |
Vardenafil hydrochloride |
| Dosage form |
Orally disintegrating tablet |
Conventional film-coated tablet |
| Typical marketed strength |
10 mg |
2.5 mg, 5 mg, 10 mg, 20 mg |
| Administration |
Placed on the tongue; no water required |
Swallowed with water |
| Original sponsor |
Bayer |
Bayer and GlaxoSmithKline commercial alliance |
| FDA application |
NDA 022406 |
NDA 021400 |
| Therapeutic class |
PDE5 inhibitor |
PDE5 inhibitor |
| Primary competitors |
Viagra, Cialis, generic sildenafil and tadalafil |
Viagra, Cialis, generic sildenafil and tadalafil |
The formulation offered convenience, but it did not materially change the core clinical proposition. Staxyn remained a short-acting PDE5 inhibitor with dosing and safety limitations similar to Levitra. The FDA label warned against use with nitrates and identified cardiovascular, visual, auditory and priapism-related risks associated with PDE5 inhibitors. (U.S. Food and Drug Administration, 2010a, 2010b)
Staxyn’s main commercial differentiation was administration convenience. It did not provide the longer duration associated with tadalafil or the first-mover recognition associated with sildenafil.
When did Staxyn receive FDA approval?
The FDA approved Staxyn in June 2010 under NDA 022406. The product was approved as an orally disintegrating formulation of vardenafil hydrochloride for erectile dysfunction. The approval followed the earlier U.S. approval of Levitra in 2003. (U.S. Food and Drug Administration, 2010a)
Staxyn entered a mature PDE5 market:
- Viagra had been approved in 1998.
- Cialis had been approved in 2003.
- Levitra had been approved in 2003.
- Staxyn launched in 2010 as a formulation extension rather than a new pharmacologic class.
This timing reduced the potential for premium pricing. Physicians, patients and payers already had several recognized PDE5 options, and the underlying vardenafil molecule had been commercially established for approximately seven years before Staxyn approval.
What patents protected Staxyn and vardenafil?
Staxyn’s protection depended on a combination of vardenafil compound patents, formulation patents and regulatory exclusivity. The underlying compound estate was more important to commercial protection than the Staxyn formulation alone.
The key patent categories were:
- Vardenafil compound patents covering the active pharmaceutical ingredient.
- Salt and crystalline-form patents covering specific chemical forms.
- Orally disintegrating formulation patents covering the Staxyn dosage form.
- Method-of-use patents covering treatment of erectile dysfunction and related dosing methods.
- Manufacturing and formulation-process patents that could create barriers even where the core compound patent had expired.
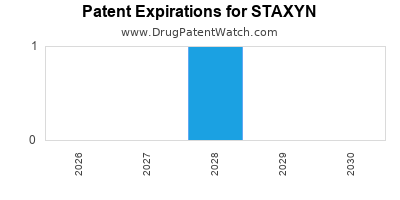
The principal U.S. vardenafil compound patent commonly associated with Levitra was U.S. Patent No. 5,250,534. That patent had an expiration date in the late 2010s after applicable patent-term adjustments and extensions. The exact enforceable date depended on the patent-term calculation and any regulatory patent-term extension.
The FDA’s Orange Book is the controlling source for active listed patents and use codes. Patent listings for Staxyn and Levitra changed over time, and the products did not have the same patent profile because Staxyn was approved under a separate NDA and used a distinct dosage form. (U.S. Food and Drug Administration, 2024a)
Did Staxyn have formulation patents?
Yes. Staxyn’s orally disintegrating tablet created a potential formulation-protection layer separate from the basic vardenafil compound. Formulation claims can cover excipient composition, tablet manufacture, dissolution performance and dosage-form architecture.
The commercial value of those patents was narrower than the value of the compound patent. A generic company could potentially avoid an asserted formulation patent by marketing a conventional vardenafil tablet rather than an orally disintegrating product. Conversely, an ODT generic could challenge the formulation claims through an Abbreviated New Drug Application and a Paragraph IV certification.
The practical strength of the formulation estate depended on claim scope, prosecution history, Orange Book listing status and whether a proposed generic product used the claimed excipients or manufacturing process.
When did Staxyn lose exclusivity?
Staxyn’s effective exclusivity declined in stages rather than ending on one single date.
| Milestone |
Commercial effect |
| 2010 FDA approval |
Staxyn entered with branded formulation protection and any remaining vardenafil exclusivity |
| Mid-2010s |
PDE5 competition and payer pressure reduced differentiation |
| Late 2010s |
Core vardenafil patent protection began to expire or weaken |
| 2020s |
Generic and low-cost vardenafil competition limited brand pricing |
| Current lifecycle |
Staxyn is a mature or discontinued commercial product with limited standalone value |
The key commercial loss was the erosion of brand-level pricing after generic vardenafil became available. Generic vardenafil tablets do not necessarily replicate Staxyn’s orally disintegrating formulation, but they compete for the same active ingredient and therapeutic indication.
Staxyn also faced substitution from generic sildenafil and tadalafil. Those products created broader price pressure than a direct Staxyn generic alone could have created.
What is the Orange Book status of Staxyn?
The FDA Orange Book records approved products, patent information and regulatory exclusivity associated with approved drug applications. Staxyn was approved under NDA 022406, while Levitra was approved under NDA 021400. The two applications should be reviewed separately for patent-listing and marketing-status analysis. (U.S. Food and Drug Administration, 2024a, 2024b)
For commercial diligence, three distinctions matter:
- A patent can remain listed even after a product has limited commercial activity.
- A product can remain approved while no longer being actively marketed.
- A listed patent does not establish that every claim is valid or infringed.
Staxyn’s regulatory value is therefore lower than its historical approval status might suggest. The product’s FDA approval supports abbreviated-development pathways for a generic equivalent, but it does not guarantee that an ODT generic would be commercially attractive.
Were there Paragraph IV challenges to Staxyn?
Public generic litigation involving vardenafil has been more commercially significant for Levitra and conventional vardenafil tablets than for Staxyn specifically. A Paragraph IV certification can challenge an Orange Book-listed patent as invalid, unenforceable or not infringed. If the NDA holder sues within the statutory period, the FDA generally applies a 30-month stay to ANDA approval, subject to statutory exceptions. (U.S. Food and Drug Administration, 2024c)
The principal risk structure was:
- Compound-patent challenges affecting all vardenafil products.
- Formulation-patent challenges affecting ODT products.
- Non-infringement strategies based on conventional tablets rather than ODTs.
- Paragraph III certifications delaying launch until patent expiry.
- At-risk launches after patent litigation or settlement.
Because the underlying compound was mature, the commercial dispute centered on the remaining scope of formulation and method-of-use claims. A challenger did not need to reproduce Staxyn exactly to compete with vardenafil.
What patent litigation affected Staxyn and Levitra?
The main litigation exposure involved vardenafil patents, generic entry and the scope of patent protection for Levitra-related products. Publicly reported disputes were generally tied to generic vardenafil ANDAs and Levitra patent rights rather than a large, standalone Staxyn litigation program.
The absence of high-profile Staxyn-specific litigation does not mean the product lacked patent risk. It means the economic prize was likely insufficient to justify extensive litigation compared with larger products such as Viagra or Cialis.
Staxyn’s litigation value was constrained by:
- The small size of the ODT segment.
- Competition from inexpensive generic PDE5 inhibitors.
- The ability to launch conventional vardenafil tablets.
- The declining value of the Levitra franchise.
- The limited likelihood of preserving a large premium for a convenience formulation.
How did Staxyn compare with Viagra and Cialis?
| Product |
Active ingredient |
Key commercial advantage |
Main lifecycle risk |
| Viagra |
Sildenafil |
First major branded PDE5 inhibitor; strong recognition |
Generic sildenafil price erosion |
| Cialis |
Tadalafil |
Longer duration of action |
Generic tadalafil and broad substitution |
| Levitra |
Vardenafil |
Established efficacy and Bayer brand |
Generic vardenafil and competition from Viagra/Cialis |
| Staxyn |
Vardenafil ODT |
Water-free administration |
Narrow differentiation and weak standalone pricing |
Staxyn’s commercial position was weaker than Cialis because it lacked tadalafil’s duration advantage. It was weaker than Viagra in brand recognition and prescription familiarity. It also inherited Levitra’s underlying vardenafil competition without offering a major clinical improvement.
The ODT format may have appealed to patients who had difficulty swallowing tablets or wanted discreet administration. That segment was not large enough to offset broad therapeutic substitution.
What was Staxyn’s financial trajectory?
Bayer did not publicly report Staxyn revenue as a distinct material line item. The product was generally part of broader pharmaceutical reporting, with revenue disclosures organized by business segment and selected major brands. Therefore, no reliable standalone annual revenue series can be constructed from Bayer’s public filings.
The likely financial trajectory was:
- Initial launch revenue from formulation novelty and brand distribution.
- Gradual erosion from competition with Levitra, Viagra and Cialis.
- Accelerated price pressure after generic vardenafil and other generic PDE5 inhibitors.
- Declining prescription volume as physicians shifted to lower-cost alternatives.
- Low residual value as a commercial brand, even if regulatory approval or patent rights remained.
Staxyn’s value was likely concentrated in its first several years after launch. As the PDE5 category matured, the product’s incremental convenience did not support sustained premium pricing.
What was the revenue exposure for Bayer?
Staxyn was unlikely to represent a material proportion of Bayer’s consolidated revenue. Bayer’s largest pharmaceutical revenue drivers have historically been products in areas such as cardiovascular disease, oncology, ophthalmology and women’s health, rather than erectile-dysfunction products. Bayer’s annual reports did not identify Staxyn as a major standalone revenue contributor. (Bayer AG, 2010-2023)
The financial exposure was more relevant at the franchise level, including Levitra and related vardenafil rights. Even there, the product’s contribution was modest relative to Bayer’s largest prescription brands.
What licensing deals affected Staxyn?
Bayer and GlaxoSmithKline commercialized Levitra through a regional alliance. Rights and commercial responsibilities varied by geography and changed over the product lifecycle. These arrangements affected marketing economics, revenue recognition and control of litigation or generic-entry decisions.
The relevant commercial structure was more important for Levitra than for Staxyn. Staxyn was a later formulation extension of the vardenafil franchise, and its economics were linked to the underlying rights, manufacturing arrangements and regional commercialization strategy.
Public company disclosures do not establish a separately reported Staxyn royalty stream or transaction valuation. Any assessment of licensing economics must therefore remain at the Levitra or vardenafil-franchise level.
What generic launch scenarios exist for Staxyn?
Three generic-entry scenarios are commercially plausible.
Conventional vardenafil tablets
This is the strongest competitive threat because conventional generic vardenafil can substitute for the active ingredient without reproducing the Staxyn ODT format. It competes on price and physician familiarity.
Generic orally disintegrating vardenafil
An ODT generic would compete most directly with Staxyn. Its commercial opportunity is smaller because the addressable market is limited and patients can substitute conventional tablets.
Therapeutic substitution
Generic sildenafil and tadalafil can capture prescriptions even without a vardenafil-equivalent launch. This is the most important long-term threat because substitution expands beyond the specific Staxyn formulation.
How strong is the Staxyn patent estate?
Staxyn’s patent estate is best characterized as moderate at launch and weak in the current late-lifecycle market.
| Factor |
Assessment |
| Core compound protection |
Historically meaningful, now expired or materially eroded |
| ODT formulation protection |
More targeted, with narrower commercial reach |
| Method-of-use patents |
Potentially limited by claim scope and prescribing behavior |
| Manufacturing patents |
Relevant if difficult to design around, but rarely sufficient alone |
| Regulatory exclusivity |
Limited because Staxyn launched after Levitra |
| Litigation leverage |
Constrained by modest market size |
| Current commercial moat |
Low |
The estate could delay a direct ODT competitor, but it could not prevent generic sildenafil, generic tadalafil or conventional vardenafil from taking market share.
What is the current commercial outlook for Staxyn?
Staxyn has limited standalone commercial potential. Its active ingredient is mature, its formulation differentiation is narrow, and its pricing power is constrained by multiple generic alternatives. The product’s remaining value is primarily residual:
- Brand recognition in selected markets.
- Existing regulatory approval.
- Potential niche demand for water-free administration.
- Any surviving formulation or manufacturing rights.
- Possible regional commercialization value where generic penetration remains lower.
The product is unlikely to justify major new clinical investment. A buyer would generally value Staxyn as a low-cost lifecycle or regional asset rather than as a growth product.
Key Takeaways
- Staxyn is Bayer’s orally disintegrating vardenafil product, approved by the FDA in 2010.
- It entered a mature PDE5 market dominated by Viagra, Cialis and Levitra.
- Its commercial differentiation was convenience, not a new mechanism or major clinical benefit.
- Core vardenafil patent protection was more valuable than the narrower ODT formulation estate.
- Generic vardenafil, sildenafil and tadalafil created overlapping price and substitution pressure.
- Bayer did not separately disclose Staxyn revenue, preventing a reliable standalone sales history.
- Staxyn’s current patent and commercial position is weak relative to its launch position.
- The most likely generic threat is therapeutic substitution and conventional vardenafil competition, not necessarily a direct ODT copy.
- Staxyn has limited value as a growth asset but may retain niche or regional lifecycle value.
FAQs About Staxyn Patents, Generics and Market Value
Is Staxyn still sold in the United States?
Staxyn’s U.S. commercial availability has been limited in the late lifecycle, and FDA approval status should be distinguished from active commercial marketing. An approved NDA does not establish that product is currently supplied.
Is generic Staxyn available?
Generic vardenafil tablets create therapeutic competition, but a conventional vardenafil tablet is not necessarily an exact generic equivalent of Staxyn’s orally disintegrating dosage form.
Does Staxyn have the same active ingredient as Levitra?
Yes. Both products contain vardenafil hydrochloride. Their principal difference is dosage form and administration.
Can tadalafil or sildenafil replace Staxyn?
Yes. Physicians can prescribe sildenafil or tadalafil as alternative PDE5 inhibitors, subject to patient-specific contraindications, drug interactions and clinical judgment.
Is Staxyn a valuable licensing opportunity?
Only in limited circumstances. Its value would most likely depend on regional rights, manufacturing cost, remaining patent scope and niche demand for orally disintegrating vardenafil rather than on broad global revenue growth.
References
-
Bayer AG. (2010-2023). Annual reports and financial statements. Bayer AG.
-
U.S. Food and Drug Administration. (2010a). Staxyn prescribing information, NDA 022406. FDA.
-
U.S. Food and Drug Administration. (2010b). Levitra prescribing information, NDA 021400. FDA.
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
U.S. Food and Drug Administration. (2024b). Drugs@FDA: FDA-approved drugs, Staxyn and Levitra application records. FDA.
-
U.S. Food and Drug Administration. (2024c). Abbreviated new drug application approvals and patent certifications. FDA.