Last updated: October 15, 2026
Izervay, Astellas Pharma’s avacincaptad pegol, is one of two FDA-approved complement inhibitors for geographic atrophy (GA) secondary to age-related macular degeneration. Its commercial trajectory depends on treatment adoption, monthly injection capacity, reimbursement, the Syfovre competitive response, and the size of the treatable GA population. Astellas acquired Izervay through its $5.9 billion purchase of Iveric Bio in 2023, making the product a strategic ophthalmology asset rather than a standalone biotechnology launch. [1]
The product has meaningful revenue potential but faces a structurally difficult market. GA treatment requires repeated intravitreal administration, patients may need indefinite treatment, and physicians must balance modest visual-function benefits against injection burden, monitoring requirements, and ocular safety risks.
What is Izervay and what FDA indication does it have?
Izervay is an intravitreal formulation of avacincaptad pegol, a pegylated RNA aptamer designed to inhibit complement component 5, or C5. The FDA approved Izervay on August 4, 2023, for the treatment of geographic atrophy secondary to age-related macular degeneration. [2]
| Item |
Izervay details |
| Active ingredient |
Avacincaptad pegol |
| Brand |
Izervay |
| Developer at approval |
Iveric Bio |
| Current commercial owner |
Astellas Pharma |
| FDA indication |
Geographic atrophy secondary to AMD |
| FDA approval date |
August 4, 2023 |
| Administration |
Intravitreal injection |
| Initial approved regimen |
2 mg every month |
| Therapeutic class |
Complement C5 inhibitor |
| NDA |
217225 |
| Primary competitor |
Syfovre, pegcetacoplan |
| Disease area |
Retina and ophthalmology |
The approval was based primarily on the GATHER1 and GATHER2 clinical programs. In GATHER2, the treatment reduced the mean rate of GA lesion growth over the prespecified assessment period, supporting the biological effect of C5 inhibition. The commercial question is whether slowing lesion expansion produces sufficient long-term functional value to support broad and sustained use.
How large is the Izervay market opportunity?
The addressable population is large, but the immediately treatable population is smaller than the epidemiological population.
Geographic atrophy affects millions of people globally, particularly older adults with advanced AMD. A substantial proportion of patients have bilateral disease, but not every patient is diagnosed, referred to a retina specialist, considered suitable for treatment, or able to maintain monthly or every-other-month visits.
Key market filters include:
- Diagnosis and referral to a retina specialist.
- Confirmation that the patient has GA rather than another late-AMD phenotype.
- Lesion location, growth rate, and proximity to the fovea.
- Patient willingness to accept repeated injections.
- Payer authorization and site-of-care economics.
- Retina-clinic capacity.
Izervay’s commercial opportunity is therefore best modeled as a treated-patient and injection-volume market rather than as a simple prevalence calculation.
What is the U.S. price of Izervay?
Astellas launched Izervay at a list price of approximately $2,190 per single-dose vial. A monthly treatment schedule implies a gross annualized drug cost of roughly $26,000 before discounts, payer rebates, buy-and-bill adjustments, and administration costs. [3]
Actual net revenue per patient is lower than list price and depends on:
- Medicare Part B reimbursement;
- commercial payer contracts;
- physician acquisition cost;
- gross-to-net discounts;
- vial utilization and wastage;
- treatment frequency;
- patient discontinuation.
The product’s economics are more attractive to manufacturers than to healthcare systems when the drug can be administered in a high-volume retina practice with efficient scheduling and limited waste.
What is the financial trajectory for Izervay?
Astellas does not report Izervay as an independent public company segment with the level of detail formerly available from Iveric Bio. The product is included within Astellas’ commercial portfolio reporting, which limits precise assessment of quarterly net sales, gross margin, and contribution profit.
The principal financial milestones are:
| Date |
Financial or commercial milestone |
| April 2023 |
Astellas agreed to acquire Iveric Bio for approximately $5.9 billion |
| June 2023 |
Acquisition completed |
| August 2023 |
FDA approved Izervay |
| Late 2023 |
Commercial launch began in the United States |
| Fiscal 2024 |
First full post-launch period for Astellas, with sales ramp driven by retina adoption |
| 2024 onward |
Growth depended on injection volume, reimbursement, and competition with Syfovre |
Iveric had no established commercial revenue base comparable with a mature pharmaceutical company before approval. The acquisition therefore transferred launch risk to Astellas. Astellas paid for a late-stage ophthalmology asset with a potentially large market, but the return profile depends on whether Izervay becomes a standard treatment rather than a niche option.
What drives Izervay revenue growth?
Izervay revenue is primarily a function of five variables:
| Revenue driver |
Commercial effect |
| Treated patient count |
Expands the recurring revenue base |
| Injection frequency |
Determines annual revenue per patient |
| Persistence |
Converts initial starts into durable sales |
| Market share |
Determines performance against Syfovre |
| Net price |
Controls revenue after discounts and reimbursement effects |
The product can generate recurring revenue because GA is chronic and treatment is administered repeatedly. The same feature creates commercial friction. Patients and physicians must commit to a long treatment course, while retina clinics must absorb additional injection volume.
The most important leading indicators are new patient starts, repeat injections, discontinuation rates, bilateral treatment, and the percentage of eligible patients receiving therapy.
How does Izervay compare with Syfovre?
Syfovre, pegcetacoplan, is Izervay’s principal direct competitor. The FDA approved Syfovre in February 2023, several months before Izervay. Both products target the complement pathway but act at different points.
| Attribute |
Izervay |
Syfovre |
| Active ingredient |
Avacincaptad pegol |
Pegcetacoplan |
| Complement target |
C5 |
C3 |
| FDA approval |
August 2023 |
February 2023 |
| Indication |
Geographic atrophy secondary to AMD |
Geographic atrophy secondary to AMD |
| Administration |
Intravitreal |
Intravitreal |
| Commercial owner |
Astellas |
Apellis Pharmaceuticals |
| Core competitive issue |
Treatment adoption and safety profile |
Earlier launch and broader dosing options |
Syfovre initially had a first-mover advantage. It also encountered significant postmarketing attention concerning retinal vasculitis and occlusive vasculitis reports, which affected physician perceptions and prescribing behavior. [4] Izervay has competed by emphasizing its clinical data, C5 mechanism, and safety experience, but it remains exposed to the same category-level concerns associated with chronic complement inhibition.
The market is likely to support differentiated prescribing rather than a single winner. Physicians may select between products based on lesion characteristics, prior experience, payer access, safety perceptions, dosing preference, and patient adherence.
What is the reimbursement and access outlook for Izervay?
Izervay is primarily a physician-administered product reimbursed through medical benefits, especially Medicare Part B in the United States. This differs from a conventional retail pharmacy product.
Coverage decisions depend on:
- FDA-labeled use;
- payer medical policies;
- documentation of GA;
- step-therapy requirements;
- site-of-care rules;
- reimbursement for drug and administration;
- coding and claims-processing policies.
Medicare coverage supports access for the older population most affected by GA, but reimbursement does not eliminate provider-level economic concerns. Retina specialists must finance inventory, manage prior authorization, schedule injections, and monitor adverse events.
The drug’s commercial penetration is likely to be fastest in large retina practices and integrated ophthalmology networks. Smaller practices may adopt more slowly because of working-capital requirements, staff capacity, and operational complexity.
What safety issues affect Izervay’s commercial potential?
The main safety and adoption concerns for GA complement inhibitors include:
- intraocular inflammation;
- endophthalmitis risk inherent to intravitreal injection;
- increased risk of conversion to neovascular AMD;
- retinal vasculitis or vascular occlusive events;
- treatment burden;
- uncertain magnitude of functional benefit.
The FDA label warns of increased risk of neovascular AMD and injection-related complications. [2] The conversion risk is commercially important because patients may require anti-VEGF therapy in addition to GA treatment, increasing both clinical complexity and total treatment burden.
Izervay’s long-term positioning will depend on real-world evidence showing that lesion-growth reduction translates into clinically meaningful preservation of vision and that safety outcomes remain manageable over extended treatment.
What patents protect Izervay?
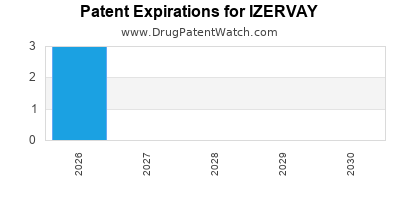
Izervay is protected by a portfolio covering the avacincaptad pegol molecule, aptamer sequence, pegylation or conjugation architecture, pharmaceutical compositions, and methods of treating geographic atrophy and related retinal disorders.
The relevant intellectual-property categories are:
Composition-of-matter protection
Composition claims may cover the C5-binding aptamer, modified nucleotides, linker chemistry, and polyethylene glycol conjugation. These claims are typically the most commercially important because they can block substitution with the same active ingredient.
Formulation protection
Formulation claims may cover sterile injectable compositions, concentration ranges, excipients, pH, storage conditions, and delivery characteristics. Formulation patents can be important after basic molecule claims become vulnerable, although their enforceability depends on claim scope and the design of a competing product.
Method-of-use protection
Method claims may cover the treatment of GA, dosing schedules, injection intervals, patient selection, or treatment of retinal disease associated with complement activation. Method-of-use patents are relevant to labeling and induced-infringement theories, but they generally create more complex enforcement questions than composition claims.
Manufacturing and process protection
Manufacturing claims may cover oligonucleotide synthesis, PEG conjugation, purification, analytical controls, and sterile production. These patents can increase development and scale-up costs for a challenger but do not necessarily prevent all noninfringing manufacturing routes.
Because patent listings and expiration estimates can change through patent-term adjustment, patent-term extension, terminal disclaimers, continuation applications, and regulatory listing updates, the FDA Orange Book and USPTO records should control any transaction or litigation analysis. A reliable commercial forecast should not treat a single nominal patent expiry as the entire Izervay exclusivity period.
When does Izervay lose exclusivity?
Izervay’s commercial exclusivity is governed by several layers:
| Exclusivity layer |
Relevance |
| New chemical entity exclusivity |
FDA approval of a new active ingredient may provide five years of U.S. NCE exclusivity, subject to the applicable regulatory rules |
| Orphan-drug exclusivity |
Not generally the primary protection for the GA indication |
| Patent protection |
May extend beyond regulatory exclusivity |
| Pediatric exclusivity |
Could add six months if granted after qualifying studies |
| Formulation and method patents |
May delay or complicate competing entry |
| Manufacturing patents |
Can raise development barriers without guaranteeing market exclusion |
The five-year NCE period generally prevents submission of an ANDA or 505(b)(2) application referencing the product during the first four years, unless the challenger files a Paragraph IV certification against a listed patent. [5] Patent litigation, settlement, and court decisions can alter the practical entry date.
Izervay is a large-molecule oligonucleotide drug administered by injection. A conventional small-molecule generic pathway may not fully describe future competition. A follow-on product could face analytical, clinical, manufacturing, and regulatory issues that make a simple low-cost generic launch less likely.
Are biosimilars or generics a near-term risk to Izervay?
Traditional biosimilar risk is limited because Izervay is not a monoclonal antibody or conventional protein biologic. Avacincaptad pegol is a pegylated oligonucleotide aptamer, and future competitors may require a complex 505(b)(2), abbreviated biologic, or other FDA pathway depending on the product and applicable regulatory interpretation.
Near-term competition is therefore more likely to come from:
- Syfovre;
- next-generation complement inhibitors;
- alternative retinal therapies;
- improved diagnostics and monitoring that change treatment selection;
- physician reluctance to treat slowly progressing GA.
A follow-on competitor would need to establish comparable molecular identity, potency, sterility, delivery performance, and clinical behavior. The injectable route and chronic dosing increase the practical barrier to substitution.
Which companies are challenging Izervay commercially?
The principal competitive companies are:
| Company |
Asset or position |
Competitive relevance |
| Astellas Pharma |
Izervay |
Current product owner |
| Apellis Pharmaceuticals |
Syfovre |
Direct approved competitor |
| Roche |
Retina portfolio and AMD infrastructure |
Potential commercial and clinical competition |
| Regeneron and Bayer |
Anti-VEGF franchises |
Compete for retina-clinic capacity and patient treatment burden |
| Emerging biotech companies |
Complement and neuroprotection programs |
Longer-term pipeline risk |
Anti-VEGF products do not directly treat GA, but they compete for the same physician time, injection capacity, and patient willingness to undergo intravitreal treatment.
What generic launch scenarios exist for Izervay?
Three scenarios are commercially relevant.
Early patent challenge
A challenger could file a Paragraph IV certification against Orange Book-listed patents after the applicable regulatory restriction period. Litigation would create a 30-month stay in certain circumstances, subject to statutory exceptions and court developments. A settlement could provide a licensed entry date earlier than patent expiry.
At-risk launch
A challenger could launch before final resolution of patent litigation. This would expose it to damages, injunction risk, and potential withdrawal if the patent holder prevails. The expected value depends on claim strength, market size, manufacturing readiness, and litigation duration.
Post-patent or negotiated entry
The most likely competitive entry path for a complex ophthalmic product may be a negotiated or post-expiry launch. Patent expiry alone would not guarantee rapid substitution because development, manufacturing, clinical evidence, reimbursement, and physician adoption would remain barriers.
What litigation and settlement issues affect Izervay?
The Izervay risk profile should be monitored across four areas:
- Paragraph IV certifications against Orange Book-listed patents;
- patent-infringement complaints filed by Astellas or its subsidiaries;
- disputes involving Iveric’s acquired intellectual property;
- settlements granting delayed entry or manufacturing rights.
Publicly disclosed litigation status can change rapidly. The relevant databases are FDA Orange Book records, PACER, district-court dockets, Federal Circuit decisions, USPTO prosecution histories, and Astellas’ securities filings.
No litigation event should be treated as commercially decisive until the asserted claims, venue, requested relief, settlement terms, and regulatory consequences are confirmed.
How strong is the Izervay patent estate?
The estate is strategically stronger than a single formulation patent because it is based on multiple protection layers: an engineered aptamer, PEG conjugation, injectable composition, retinal indications, and manufacturing know-how.
Its main strengths are:
- technical complexity of the active ingredient;
- difficulty of developing an identical pegylated aptamer;
- chronic-use value of the product;
- potential protection across composition, use, and process claims;
- regulatory and manufacturing barriers to substitution.
Its main vulnerabilities are:
- patent-term limits;
- obviousness or written-description challenges;
- narrow method-of-use claims;
- design-around opportunities for alternative complement inhibitors;
- the possibility that a competitor uses a different molecule rather than copying avacincaptad pegol.
The estate is therefore commercially meaningful but does not eliminate category competition.
What is the outlook for Izervay revenue?
Izervay has a credible path to a multibillion-dollar market opportunity across the GA population, but the timing of that opportunity is uncertain. Revenue growth is likely to be front-loaded in high-volume retina centers, followed by slower expansion as physicians assess long-term outcomes and payers refine coverage.
The most important valuation variables are:
- annual treated patients;
- average injections per patient;
- net price after discounts;
- persistence beyond the first year;
- share against Syfovre;
- incidence of adverse events;
- conversion to neovascular AMD;
- international reimbursement;
- competition from pipeline therapies.
Astellas’ acquisition price created high expectations. Izervay does not need to dominate the GA market to become material to Astellas, but it must achieve durable treatment persistence and maintain pricing in a two-product market.
Key Takeaways
- Izervay is Astellas’ avacincaptad pegol product for geographic atrophy secondary to AMD.
- The FDA approved it on August 4, 2023.
- Astellas acquired the product through its approximately $5.9 billion acquisition of Iveric Bio.
- Syfovre is the principal direct competitor.
- Revenue depends on treated-patient growth, injection frequency, persistence, reimbursement, and retina-clinic capacity.
- The product has recurring-revenue potential because GA treatment is chronic.
- Patent protection likely spans the aptamer, PEG conjugate, formulations, methods of treatment, and manufacturing processes.
- Traditional biosimilar risk is limited, but complex follow-on products could emerge through nonstandard regulatory pathways.
- Safety, treatment burden, and uncertain long-term functional benefit are the main commercial constraints.
- The acquisition has shifted launch and execution risk to Astellas, while the size of the GA population provides substantial upside.
FAQs
What is the active ingredient in Izervay?
Izervay contains avacincaptad pegol, a pegylated RNA aptamer that inhibits complement component C5.
Is Izervay a biologic?
Izervay is a complex injectable oligonucleotide product rather than a conventional monoclonal antibody biologic. Its follow-on regulatory pathway may differ from a standard generic or biosimilar pathway.
How often is Izervay administered?
The FDA-approved regimen is intravitreal administration at regular intervals, with the initial label supporting monthly dosing. Treatment frequency may be adjusted only within the scope of the approved labeling and physician judgment.
Does Izervay cure geographic atrophy?
No. Izervay is intended to slow the progression of GA lesions. It does not restore retinal tissue that has already been lost.
Who owns the Izervay intellectual property?
Astellas owns the commercial rights through its acquisition of Iveric Bio. The relevant patent assets originated with Iveric and related predecessor research programs.
References
- Astellas Pharma Inc. (2023). Astellas completes acquisition of Iveric Bio.
- U.S. Food and Drug Administration. (2023). Izervay prescribing information.
- Astellas Pharma Inc. (2023). Astellas announces U.S. launch of Izervay for geographic atrophy.
- U.S. Food and Drug Administration. (2023). FDA alerts health care professionals of risks associated with Syfovre.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.