Last updated: November 3, 2026
Diabeta is the former branded formulation of glyburide, also known as glibenclamide, an oral sulfonylurea for type 2 diabetes. Its commercial value has largely migrated from the brand to low-cost generic glyburide products. Diabeta has no meaningful current patent moat, no material regulatory exclusivity, and limited disclosed brand-level revenue. The drug remains commercially available through generic channels, but its market is structurally declining as prescribers favor metformin, GLP-1 receptor agonists, SGLT2 inhibitors, and insulin products with stronger cardiovascular, renal, or weight-loss profiles.
What is Diabeta and how is it positioned in the diabetes market?
Diabeta contains glyburide, an insulin secretagogue that lowers blood glucose by stimulating pancreatic beta cells to release insulin. It is approved for adults with type 2 diabetes as an adjunct to diet and exercise. The product is available in tablet strengths including 1.25 mg, 2.5 mg, and 5 mg formulations under the historical U.S. Diabeta label.[1]
Glyburide belongs to the second-generation sulfonylurea class, along with glipizide and glimepiride. The class is inexpensive and effective at reducing blood glucose, but it has a higher hypoglycemia risk than several newer therapies. Glyburide also can cause weight gain and does not provide the cardiovascular, renal, or weight-loss benefits associated with selected newer diabetes medicines.[2]
Diabeta product profile
| Attribute |
Diabeta |
| Active ingredient |
Glyburide |
| Drug class |
Second-generation sulfonylurea |
| Primary indication |
Type 2 diabetes |
| U.S. dosage forms |
Immediate-release oral tablets |
| Historical brand owner |
Sanofi and predecessor companies |
| Current commercial status |
Generic-dominated market |
| U.S. patent position |
No material active composition-of-matter protection |
| FDA exclusivity |
Expired |
| Primary competitors |
Generic glyburide, glipizide, glimepiride, metformin, newer branded diabetes products |
The drug has retained a niche among cost-sensitive patients and clinicians familiar with sulfonylureas. Its market position is weaker in treatment guidelines and formulary strategy than it was during the period before broad adoption of newer drug classes.
When did Diabeta lose exclusivity?
Diabeta lost its commercial exclusivity decades ago. Glyburide was developed and commercialized before the modern wave of pharmaceutical patent litigation and regulatory exclusivity that surrounds newer diabetes products.
The brand's key commercial protections have expired, and generic glyburide products are available in the United States. No current regulatory exclusivity period materially restricts generic competition.
Diabeta exclusivity timeline
| Event |
Approximate status |
| Glyburide introduced into clinical use |
1960s |
| U.S. Diabeta approval |
1980s historical approval period |
| Original product patent protection |
Expired |
| Generic glyburide entry |
Long established |
| Current FDA exclusivity |
None |
| Current branded market protection |
None of commercial significance |
The historical Diabeta approval is associated with NDA 017532 in FDA product records and labeling materials.[1] Because the relevant patents and regulatory exclusivities expired long ago, generic manufacturers do not need to wait for a future loss-of-exclusivity event.
What patents protect Diabeta and glyburide?
No active U.S. patent estate of commercial significance protects the original Diabeta molecule. Glyburide is an established small-molecule active ingredient, and the relevant compound, formulation, and use protections have expired.
The Orange Book does not provide a current patent barrier that would prevent approval or marketing of ordinary generic glyburide tablets.[3] The commercial opportunity therefore depends on manufacturing cost, product availability, wholesaler access, pharmacy contracts, and reimbursement rather than patent exclusivity.
Are formulation patents still relevant to Diabeta?
Routine glyburide tablets are not protected by a current branded formulation moat. Historical patents may have covered specific compositions, manufacturing techniques, or dosage forms, but those protections do not create a meaningful present-day barrier for standard immediate-release generic tablets.
A manufacturer could seek protection for a new glyburide delivery system, fixed-dose combination, modified-release product, or clinically differentiated formulation. Such protection would apply to the new product rather than revive exclusivity for ordinary Diabeta tablets.
What is the FDA regulatory status of Diabeta?
The FDA regulatory framework for glyburide is mature. Generic manufacturers can rely on the established safety and efficacy profile of the reference product and seek approval through the abbreviated new drug application pathway, subject to applicable bioequivalence and quality requirements.[4]
The principal regulatory risks are manufacturing quality, supply continuity, labeling compliance, and pharmacovigilance. The drug does not face the development uncertainty associated with a new molecular entity.
FDA and clinical considerations
The FDA-approved labeling identifies hypoglycemia as a major risk of glyburide. The risk is higher in older adults, patients with impaired renal or hepatic function, patients with irregular food intake, and patients receiving other glucose-lowering therapies.[1]
The American Diabetes Association and other clinical guidance sources generally place greater emphasis on therapies selected according to cardiovascular disease, chronic kidney disease, heart failure, obesity, and hypoglycemia risk. Sulfonylureas remain possible options, particularly where cost is a dominant consideration, but glyburide is often less attractive than glipizide because of prolonged hypoglycemia concerns.[2]
How many patents cover Diabeta?
The commercially relevant answer is zero active U.S. patents blocking ordinary generic glyburide tablets.
| Patent category |
Current commercial impact |
| Glyburide active-ingredient patent |
Expired |
| Original Diabeta formulation patents |
Expired |
| Method-of-use patents for ordinary glyburide treatment |
Expired or non-blocking |
| FDA-listed Orange Book patents |
No material active barrier identified for standard product |
| Generic glyburide approval pathway |
Open under ANDA procedures |
Patent litigation is therefore not a meaningful current market variable for Diabeta. There is no active Paragraph IV campaign comparable to litigation involving recently launched diabetes products with billions of dollars in annual sales.
Which companies are challenging Diabeta exclusivity?
No company needs to challenge a meaningful Diabeta exclusivity position. Generic glyburide manufacturers entered the market years ago, and competition is established.
The relevant competitors include manufacturers of generic glyburide tablets and suppliers of therapeutically substitutable products. Depending on the distribution channel and period, generic products may be supplied by companies such as Amneal, Ascend Laboratories, Hikma, Major Pharmaceuticals, Par Pharmaceutical, Rising Pharmaceuticals, and other authorized generic or private-label suppliers. Product availability can change as manufacturers enter or exit low-margin markets.
Competition also comes from other diabetes drugs rather than only from glyburide equivalents:
- Metformin, usually the first-line low-cost oral therapy.
- Glipizide and glimepiride, competing sulfonylureas.
- DPP-4 inhibitors, including sitagliptin and linagliptin.
- SGLT2 inhibitors, including empagliflozin and dapagliflozin.
- GLP-1 receptor agonists, including semaglutide and dulaglutide.
- Insulin products for patients requiring intensified treatment.
What generic entry risks exist for Diabeta?
Generic entry risk is already realized rather than prospective. Diabeta operates in a post-exclusivity market where generic substitution is the principal commercial condition.
The main risks are:
- Continued price compression from multiple suppliers.
- Pharmacy substitution away from any remaining branded inventory.
- Contracting pressure from wholesalers and pharmacy benefit managers.
- Manufacturing exits caused by low margins.
- Periodic shortages if production becomes concentrated among a small number of suppliers.
- Therapeutic substitution toward newer diabetes medicines.
- Declining use in older adults because of hypoglycemia concerns.
A generic supplier can still earn a modest return if it maintains reliable supply, qualifies for favorable contracts, or serves a shortage-sensitive channel. The opportunity is operational rather than patent-driven.
How has the competitive landscape changed?
Diabeta's competitive position has weakened in two stages.
First, the drug lost brand exclusivity and became interchangeable with low-priced generic glyburide. This eliminated the ability to sustain premium branded pricing.
Second, clinical practice shifted toward drugs with outcome benefits beyond glucose lowering. Empagliflozin and dapagliflozin gained use in patients with heart failure or chronic kidney disease. Semaglutide and related GLP-1 therapies expanded in obesity and diabetes care. These therapies have higher prices, larger commercial markets, and stronger product differentiation.[2]
Diabeta compared with competing diabetes drugs
| Drug or class |
Relative cost position |
Hypoglycemia risk |
Weight effect |
Outcome differentiation |
| Glyburide |
Very low |
Higher |
Gain |
Limited |
| Glipizide |
Very low |
Moderate |
Gain |
Limited |
| Metformin |
Very low |
Low when used alone |
Neutral or modest loss |
Broad first-line use |
| SGLT2 inhibitors |
High before discounts |
Low when used alone |
Modest loss |
Heart and kidney benefits for selected patients |
| GLP-1 receptor agonists |
High |
Low when used alone |
Meaningful loss |
Cardiometabolic benefits for selected agents |
| Insulin |
Variable |
High |
Gain |
Essential for insulin-deficient patients |
Diabeta retains an advantage only in narrow situations, principally low acquisition cost and familiarity. Those advantages do not support substantial brand revenue.
What is the financial trajectory for Diabeta?
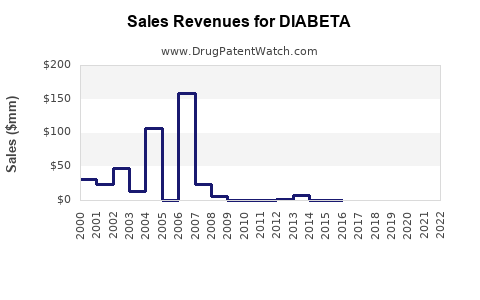
No current public financial disclosure isolates Diabeta revenue. Sanofi's public reporting does not identify Diabeta as a material separately reported product, and generic manufacturers generally do not disclose product-level sales for low-cost glyburide tablets.[5]
The financial trajectory is therefore best characterized as:
- Peak commercial value during the branded era.
- Rapid erosion after generic entry.
- Long-term decline in branded sales.
- Residual low-margin revenue in generic and institutional channels.
- Further volume pressure from therapeutic substitution.
- Limited probability of a branded revenue recovery without a new formulation or combination product.
Revenue exposure
| Revenue source |
Current outlook |
| Original Diabeta brand |
Minimal or immaterial public-company contribution |
| Generic glyburide tablets |
Low-price, fragmented revenue pool |
| Institutional purchasing |
Stable in selected cost-sensitive settings |
| Retail pharmacy |
Vulnerable to substitution and declining utilization |
| New formulation opportunity |
Possible but requires new clinical and commercial investment |
| Licensing revenue |
No major publicly disclosed active Diabeta licensing stream |
The product should not be valued using the revenue multiples applicable to protected diabetes medicines. Its economic value is closer to that of a mature generic product with limited differentiation.
What manufacturing and intellectual-property barriers affect glyburide?
Manufacturing barriers are modest but not nonexistent. Glyburide is a well-established small molecule, so the core synthesis and tablet production processes are mature. The main barriers are compliance and economics:
- FDA-compliant active pharmaceutical ingredient sourcing.
- Validated content uniformity and dissolution processes.
- Control of impurities and degradation products.
- Reliable supply of low-volume active ingredient.
- Compliance with current good manufacturing practices.
- Bioequivalence documentation for generic approval.
- Ability to maintain production at low selling prices.
The strongest commercial barrier may be supply economics. If too many manufacturers compete for a small market, one or more may exit. That can create temporary supply tightness without creating sustainable pricing power.
What patent litigation affects Diabeta?
No material active U.S. patent litigation affecting standard Diabeta or generic glyburide tablets is publicly central to the market. The product's litigation profile is fundamentally different from that of newer diabetes products with live patents covering active ingredients, delivery devices, combination therapies, or methods of treatment.
There is also no meaningful current Paragraph IV litigation narrative around Diabeta. Generic glyburide products are established products, not recent challengers seeking first market entry against a protected reference drug.
What licensing deals involve Diabeta?
No major current licensing transaction involving Diabeta is publicly material to valuation. The product's historical ownership passed through predecessor companies and established pharmaceutical commercialization arrangements, but its commercial position no longer depends on an active licensing network.
A new license could become relevant only if a company developed a differentiated glyburide product, such as a modified-release tablet, a combination therapy, or a delivery system designed to reduce hypoglycemia or improve adherence. Such a product would face substantial clinical and commercial competition.
When could Diabeta or glyburide launch a new commercial product?
A new glyburide product would require more than reformulation. It would need a clear clinical or economic advantage over generic tablets and competing diabetes therapies.
Potential development concepts include:
- Modified-release glyburide to reduce peak exposure.
- A fixed-dose combination with metformin.
- A lower-dose formulation for selected older patients.
- A patient-specific delivery system.
- A formulation designed to address adherence or dosing frequency.
The investment case is weak unless the product demonstrates a clinically meaningful reduction in hypoglycemia or a material adherence benefit. Low generic pricing would make premium positioning difficult.
How strong is the Diabeta patent estate?
The Diabeta patent estate is weak for current commercial purposes. It has no meaningful composition-of-matter protection, no active exclusivity, and no apparent patent barrier to standard generic glyburide tablets.
| Patent-strength factor |
Assessment |
| Core molecule protection |
None remaining |
| Brand formulation protection |
Expired |
| Method-of-use protection |
No material current barrier |
| Orange Book blocking patents |
None of commercial significance |
| Generic substitution protection |
None |
| Litigation leverage |
Minimal |
| New-product patent potential |
Available only through new innovation |
Key Takeaways
- Diabeta is the historical branded version of glyburide, a mature sulfonylurea.
- Its original patents and regulatory exclusivities have expired.
- The U.S. market is generic-dominated, with no meaningful current brand premium.
- No active Paragraph IV or patent litigation materially shapes the market.
- Revenue is not separately disclosed and is likely immaterial at the original brand-owner level.
- Generic glyburide remains available but faces price pressure, low margins, and declining clinical preference.
- Metformin, SGLT2 inhibitors, GLP-1 receptor agonists, insulin, and competing sulfonylureas constrain growth.
- Any commercial revival would require a differentiated formulation or combination product supported by new intellectual property.
FAQs About Diabeta Market Value and Exclusivity
Is Diabeta still sold in the United States?
Glyburide remains available through generic products. The original Diabeta brand has limited commercial visibility and does not hold a meaningful current market position.
Is glyburide a generic drug?
Yes. Glyburide is widely available as a generic oral tablet. Generic products compete primarily on price, manufacturing reliability, pharmacy access, and reimbursement.
Does Diabeta have an active Orange Book patent?
No material active Orange Book patent is understood to block standard generic glyburide tablets. The original protections have expired.
Is glyburide still recommended for older adults?
Glyburide is used cautiously in older adults because of prolonged hypoglycemia risk. Clinicians often prefer alternatives with lower hypoglycemia risk, depending on the patient's clinical profile.[2]
Could a company still patent a new glyburide product?
A company could seek patents for a novel formulation, delivery system, combination product, or manufacturing process. Such patents would protect the new product or process, not the unmodified Diabeta product.
References
-
U.S. Food and Drug Administration. (n.d.). Diabeta (glyburide) tablets: Prescribing information. FDA. https://www.accessdata.fda.gov/drugsatfda_docs/label/
-
American Diabetes Association Professional Practice Committee. (2024). 9. Pharmacologic approaches to glycemic treatment: Standards of care in diabetes-2024. Diabetes Care, 47(Supplement_1), S158-S178. https://doi.org/10.2337/dc24-S009
-
U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations, Orange Book. FDA. https://www.accessdata.fda.gov/scripts/cder/ob/
-
U.S. Food and Drug Administration. (n.d.). Abbreviated new drug application process. FDA. https://www.fda.gov/drugs/types-applications/abbreviated-new-drug-application-anda
-
Sanofi. (2024). Universal registration document and annual financial report. Sanofi. https://www.sanofi.com/en/investors/financial-results-and-events/annual-reports