Last updated: November 4, 2026
CAPLYTA, the brand name for lumateperone tosylate, has become Intra-Cellular Therapies’ primary commercial asset and its main source of revenue. FDA approvals in schizophrenia, bipolar depression, and adjunctive major depressive disorder expanded the addressable market from a narrow antipsychotic segment into a broader mood-disorder franchise. Annual net product sales increased from about $285.9 million in 2022 to $537.3 million in 2023 and approximately $658.5 million in 2024. [1][2]
The commercial outlook remains favorable, but the valuation case depends on continued prescription growth, broader use in major depressive disorder, payer access, and the durability of CAPLYTA’s patent estate. Generic entry is unlikely before the early 2030s under the principal composition-of-matter patent, although Paragraph IV litigation or settlements could alter the launch date.
What is CAPLYTA and how does it generate revenue?
CAPLYTA is an oral atypical antipsychotic containing lumateperone tosylate. Intra-Cellular Therapies commercializes the product in the United States, where the company derives virtually all of its product revenue.
CAPLYTA has three principal FDA-approved uses:
| FDA indication |
Approval timing |
Commercial significance |
| Schizophrenia in adults |
December 2019 |
Initial market entry |
| Depressive episodes associated with bipolar I or bipolar II disorder |
December 2021 |
Expanded use in bipolar depression |
| Adjunctive treatment of major depressive disorder in adults |
December 2024 |
Large incremental market opportunity |
The product acts through modulation of dopamine D1 and D2 receptors, serotonin 5-HT2A receptors, and other neurotransmitter pathways. Its positioning emphasizes efficacy across depressive symptoms with a comparatively favorable profile for weight gain, extrapyramidal symptoms, and metabolic effects relative to some competing antipsychotics. Those attributes are commercially relevant because tolerability often affects persistence in chronic psychiatric treatment.
CAPLYTA is sold as capsules in 10 mg, 21 mg, 42 mg, and 60 mg strengths. The 42 mg dose is the standard dose for most approved indications, while lower strengths are used for dose adjustment and selected drug-interaction scenarios.
How fast have CAPLYTA sales grown?
CAPLYTA sales have grown at a rate well above the broader antipsychotic market.
| Fiscal year |
Intra-Cellular Therapies total revenue |
CAPLYTA commercial position |
| 2021 |
Approximately $128 million |
Early bipolar-depression launch |
| 2022 |
Approximately $286 million |
Expansion after full-year bipolar indication |
| 2023 |
Approximately $537 million |
Strong prescription and market-share growth |
| 2024 |
Approximately $659 million |
Continued growth before full MDD contribution |
Sources: Intra-Cellular Therapies annual reports and earnings disclosures. [1][2]
From 2022 to 2024, revenue increased by roughly 130%. Growth has been driven by:
- Expansion of the treated population beyond schizophrenia.
- Increased physician familiarity with CAPLYTA.
- Prescription growth in bipolar depression.
- Product differentiation on weight and metabolic tolerability.
- Increasing use by psychiatrists and other prescribers.
- FDA approval for adjunctive major depressive disorder.
The 2024 revenue base largely predates the full commercial effect of the MDD approval. The MDD indication therefore represents the largest near-term volume opportunity, but it also places CAPLYTA into a more competitive and payer-sensitive category.
What is the CAPLYTA market opportunity in major depressive disorder?
The adjunctive MDD indication substantially expands CAPLYTA’s addressable market. Major depressive disorder is far larger than schizophrenia or bipolar depression by patient count, but most patients do not require an atypical antipsychotic. CAPLYTA competes within the treatment-resistant or partially responsive segment, where an antidepressant is combined with an antipsychotic.
The relevant competitive set includes:
| Product |
Company |
MDD role |
Key competitive issue |
| CAPLYTA |
Intra-Cellular Therapies |
Adjunctive therapy |
Differentiated tolerability and single-product focus |
| Rexulti |
Otsuka and Lundbeck |
Adjunctive therapy |
Established commercial presence |
| Abilify |
Otsuka |
Adjunctive therapy |
Generic competition and broad physician familiarity |
| Seroquel XR |
AstraZeneca |
Adjunctive or related psychiatric use |
Generic erosion |
| Vraylar |
AbbVie |
Bipolar depression and schizophrenia |
Strong bipolar franchise; MDD development relevance |
| Quetiapine generics |
Multiple manufacturers |
Off-label and approved psychiatric use |
Low cost and broad availability |
CAPLYTA’s MDD opportunity is commercially attractive because the drug can be prescribed after inadequate response to an antidepressant without requiring a new molecular entity launch. The principal risks are formulary restrictions, prior authorization, step therapy, and competition from lower-cost generic aripiprazole and quetiapine.
When does CAPLYTA lose exclusivity?
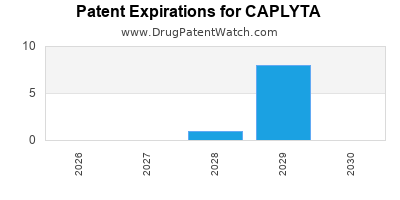
The principal CAPLYTA composition-of-matter patent is commonly associated with U.S. Patent No. 8,598,233, which has a listed expiration in 2031, subject to patent-term adjustment and any applicable regulatory exclusivity. The Orange Book should be treated as the controlling source for listed patents, expiration dates, and use codes. [3]
Key exclusivity considerations include:
| Protection type |
Approximate timing |
Commercial effect |
| Original FDA approval exclusivity |
Expired or substantially consumed |
Does not independently block ANDA filing today |
| Bipolar-depression approval |
No separate NCE period |
Expanded labeling rather than new molecular exclusivity |
| Composition patent |
Approximately 2031 |
Primary barrier to generic launch |
| Later formulation or method patents |
Potentially extending into the 2030s |
May create additional litigation or launch constraints |
| Patent-term extension |
Potentially available, subject to statutory limits |
Could extend effective protection beyond nominal expiration |
CAPLYTA’s loss-of-exclusivity date will depend on the specific patents asserted against an ANDA, the validity and enforceability of those patents, and the outcome of any Paragraph IV litigation. A nominal 2031 patent expiration does not guarantee market exclusivity until that date, and it does not establish that every listed patent expires simultaneously.
What patents protect CAPLYTA?
CAPLYTA’s protection is based primarily on patents covering lumateperone, pharmaceutical compositions, dosage forms, and therapeutic use.
Composition-of-matter protection
The core patent family protects lumateperone and related chemical subject matter. Composition patents generally provide the strongest protection because an ANDA applicant cannot avoid infringement merely by changing inactive ingredients.
U.S. Patent No. 8,598,233 is associated with the lumateperone franchise and is listed in public drug-patent databases with an expiration around 2031. [3][4]
Formulation and dosage-form protection
Formulation patents can cover:
- Lumateperone tosylate compositions.
- Oral capsules.
- Specific dose ranges.
- Stability characteristics.
- Pharmaceutical excipient combinations.
- Manufacturing or crystallization processes.
The practical strength of these patents depends on whether a generic applicant can design around the claims while maintaining bioequivalence. Formulation patents are usually more vulnerable to design-around strategies than composition patents, but they can increase litigation costs and delay commercial launch.
Method-of-use protection
Method patents can cover treatment of:
- Schizophrenia.
- Bipolar depression.
- Major depressive disorder.
- Patients with particular metabolic or tolerability characteristics.
- Specific dosing regimens or combination treatments.
Use patents may not block a generic product for all indications if the generic label uses carve-outs or omits protected indications. This creates a potential skinny-label pathway, particularly where the composition patent has expired but method patents remain active.
Is CAPLYTA listed in the Orange Book?
Yes. FDA Orange Book records identify CAPLYTA-related patents and use codes that can be relevant to ANDA certification and Paragraph IV litigation. [3]
Orange Book-listed patents affect:
- Whether an ANDA applicant must submit a Paragraph IV certification.
- Whether the reference sponsor can file a patent-infringement action.
- The potential 30-month stay of ANDA approval.
- The scope of any generic label carve-out.
- The timing of tentative or final approval.
The Orange Book does not determine patent validity. A listed patent can be challenged for invalidity, noninfringement, or unenforceability in federal court.
Which companies are challenging CAPLYTA patents?
Publicly available patent records and litigation databases should be monitored for ANDA filings by large generic manufacturers, including Teva, Viatris, Sandoz, Dr. Reddy’s Laboratories, Sun Pharmaceutical, Zydus, and Hikma. A company becomes a formal Paragraph IV challenger only after submitting an ANDA certification and triggering the statutory notice process.
No broad generic market entry has occurred, and there is no established commercial generic equivalent to CAPLYTA as of the latest reported commercial period. The principal near-term risk is not immediate substitution but a future ANDA filing that initiates a patent case.
A Paragraph IV challenge would create three possible outcomes:
| Outcome |
Likely market effect |
| Sponsor wins litigation |
Generic launch is delayed until patent expiry or settlement date |
| Generic wins invalidity or noninfringement ruling |
Early entry becomes possible |
| Settlement |
Entry date depends on the negotiated terms and antitrust constraints |
What patent litigation affects CAPLYTA?
CAPLYTA’s patent risk is concentrated in future ANDA litigation rather than biosimilar litigation. Lumateperone is a small molecule, so the relevant pathway is an ANDA under Section 505(j), not a biosimilar application under the Public Health Service Act.
The most important potential litigation targets are:
- The core lumateperone composition patent.
- Patents covering lumateperone tosylate or crystalline forms.
- Capsule and oral dosage-form patents.
- Treatment patents for bipolar depression or MDD.
- Patents covering specific dosing and administration methods.
A sponsor lawsuit filed within 45 days of a Paragraph IV notice would generally trigger the Hatch-Waxman 30-month stay, unless the court resolves the case earlier or another statutory event ends the stay.
What is the FDA regulatory status of CAPLYTA?
CAPLYTA is FDA-approved for three psychiatric indications. The December 2024 approval for adjunctive MDD was based on positive Phase 3 studies evaluating lumateperone added to existing antidepressant therapy. [5]
The approval changes the product’s regulatory and commercial profile in four ways:
- It expands the prescriber base beyond schizophrenia and bipolar specialists.
- It increases exposure to primary-care referral and general psychiatry channels.
- It provides a larger pool of patients for lifecycle-management studies.
- It may support broader payer discussions based on treatment-resistant depression.
CAPLYTA remains an oral branded product. It is not a biologic and does not face biosimilar substitution.
How strong is the CAPLYTA patent estate?
CAPLYTA has a strong commercial patent position through the early 2030s because the core chemical protection is more important than the later use patents. The estate is less secure after the core composition patent expires because generic manufacturers may use label carve-outs and formulation design-arounds.
| Patent category |
Relative strength |
Reason |
| Core chemical composition |
High |
Difficult to design around while preserving the same active ingredient |
| Salt or crystalline form |
Moderate to high |
Can delay entry if claims are technically robust |
| Formulation |
Moderate |
Potential design-around and bioequivalence strategies |
| Method of use |
Moderate |
Vulnerable to skinny-label approaches |
| Manufacturing process |
Variable |
Strong only when commercially necessary and difficult to replicate |
The estate’s commercial value also depends on whether additional patents are listed after the MDD approval. New patents cannot automatically restore composition-level protection, but they can increase the cost and complexity of generic entry.
How does CAPLYTA compare with Vraylar and Rexulti?
| Metric |
CAPLYTA |
Vraylar |
Rexulti |
| Active ingredient |
Lumateperone |
Cariprazine |
Brexpiprazole |
| Main commercial owner |
Intra-Cellular Therapies |
AbbVie |
Otsuka and Lundbeck |
| Schizophrenia |
Yes |
Yes |
Yes |
| Bipolar depression |
Yes |
Yes |
No |
| Adjunctive MDD |
Yes |
Not the principal established label through the comparison period |
Yes |
| Generic competition |
No commercial generic |
No commercial generic in the core period |
No commercial generic in the core period |
| Key differentiation |
Tolerability and depressive symptom positioning |
Bipolar and psychosis franchise |
MDD and tolerability positioning |
CAPLYTA’s main commercial vulnerability is that its strongest growth market, MDD, includes products with established reimbursement and physician familiarity. Its main advantage is that it has a clear depressive-disorder narrative across bipolar depression and adjunctive MDD.
What generic launch risks exist for CAPLYTA?
A realistic launch framework has three stages:
Before 2031
Generic entry would require a successful Paragraph IV challenge, settlement, or invalidation of the relevant core patents. An early launch would materially change Intra-Cellular Therapies’ revenue trajectory because CAPLYTA accounts for nearly all product sales.
Around the core patent expiration
The first generic entrant could receive 180-day exclusivity if it is the first valid Paragraph IV filer and meets statutory requirements. Market erosion would depend on the number of approved ANDAs and the timing of authorized-generic supply.
After composition-patent expiry
Multiple manufacturers could enter, producing rapid price compression. Psychiatric branded products can retain some share after generic entry, but payer substitution usually accelerates once interchangeable generics are available.
The highest financial risk is therefore a successful early Paragraph IV challenge. The second-largest risk is a launch near nominal patent expiry that prevents the company from converting the MDD opportunity into a long-duration growth platform.
What is CAPLYTA’s financial trajectory and revenue exposure?
CAPLYTA is the central asset in Intra-Cellular Therapies’ valuation. Revenue concentration is high, but the company has historically maintained a strong cash position and a lower operating-risk profile than diversified pharmaceutical companies because it does not depend on a large multi-product commercial infrastructure.
The financial trajectory has four phases:
- Initial schizophrenia commercialization after 2019.
- Acceleration after the 2021 bipolar-depression approval.
- Rapid prescription growth through 2023 and 2024.
- Potential MDD-driven expansion beginning in 2025, followed by patent-risk concentration in the early 2030s.
The main operating variables are net price, gross-to-net deductions, payer coverage, prescription persistence, sales-force efficiency, and the proportion of new prescriptions coming from MDD.
Revenue growth could slow even while prescriptions increase if payers impose stricter prior authorization or if discounting rises in the MDD market. Conversely, stronger adoption among commercial plans and Medicare could support continued top-line expansion.
What licensing deals affect CAPLYTA?
CAPLYTA is primarily an internally commercialized Intra-Cellular Therapies product. The company has not depended on a major external commercialization partner for the U.S. franchise. That preserves economics but places sales, marketing, regulatory, and post-approval obligations on the company.
The absence of a major U.S. licensing partner also means that any future regional licensing or co-commercialization transaction would be strategically important. Potential deal value would depend on geographic rights, development obligations, royalty rates, and whether the counterparty can improve access outside the United States.
What is the competitive outlook for CAPLYTA?
CAPLYTA has a favorable near-term competitive position but faces structural pressure from generic antipsychotics and established branded products.
Key market forces are:
- Expansion of adjunctive MDD use.
- Continued demand for psychiatric drugs with lower metabolic burden.
- Increasing scrutiny of antipsychotic safety and persistence.
- Generic price competition from aripiprazole and quetiapine.
- Payer management of branded adjunctive therapies.
- Competition from Vraylar, Rexulti, and future psychiatric launches.
- Dependence on U.S. commercial execution.
The product’s market share can grow without taking patients directly from other branded atypical antipsychotics because a large portion of the opportunity is untreated, undertreated, or managed with generic therapies. That same market structure limits pricing power.
Key Takeaways
- CAPLYTA is Intra-Cellular Therapies’ dominant commercial asset.
- Revenue rose from about $285.9 million in 2022 to approximately $658.5 million in 2024.
- FDA approval for adjunctive MDD materially expanded the product’s addressable market.
- The core patent estate provides protection into approximately 2031, subject to the exact Orange Book listing and patent-term calculations.
- Generic entry before 2031 would most likely require a successful Paragraph IV challenge or settlement.
- CAPLYTA has no biosimilar risk because lumateperone is a small-molecule drug.
- The largest commercial upside is MDD adoption; the largest downside is payer restriction or early generic litigation.
- Revenue concentration creates substantial exposure to CAPLYTA’s prescription trajectory and eventual loss of exclusivity.
FAQs
Does CAPLYTA have biosimilar competition?
No. CAPLYTA is a small-molecule oral drug, so future competition would proceed through the ANDA generic pathway rather than the biosimilar pathway.
Is lumateperone available as a generic?
No commercial generic lumateperone product had entered the U.S. market through the latest reported period. The timing of future entry depends on Orange Book patents, ANDA filings, and Paragraph IV litigation.
Which indication drives CAPLYTA’s future growth?
Adjunctive major depressive disorder is the largest incremental growth opportunity because the patient population is materially larger than the schizophrenia and bipolar-depression populations.
Does CAPLYTA have a new chemical entity exclusivity period?
CAPLYTA received FDA approval as a new molecular entity, but the original five-year NCE exclusivity period has elapsed. Current protection depends mainly on patents and any indication-specific regulatory protections.
What would happen to Intra-Cellular Therapies after generic CAPLYTA entry?
Generic entry would likely reduce net price, market share, and revenue, with the magnitude depending on entry timing, the number of approved manufacturers, payer substitution, and the company’s ability to commercialize replacement products.
References
-
Intra-Cellular Therapies, Inc. (2024). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 for the fiscal year ended December 31, 2023. U.S. Securities and Exchange Commission.
-
Intra-Cellular Therapies, Inc. (2025). Fourth-quarter and full-year 2024 financial results and business updates. Company press release.
-
U.S. Food and Drug Administration. (2025). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
United States Patent and Trademark Office. (2013). U.S. Patent No. 8,598,233: Lumateperone-related pharmaceutical compounds and compositions. USPTO.
-
U.S. Food and Drug Administration. (2024). CAPLYTA approval for adjunctive treatment of major depressive disorder in adults. FDA.